
2027 Banking and Capital Markets Outlook
US banks enter 2027 well-positioned to invest for growth as AI and digital assets reshape the industry
US banks are expected to enter 2027 from a position of strength. However, macroeconomic and policy uncertainty will likely remain high in the coming months, compounded by a complex set of questions about what artificial intelligence advancement could mean for the financial system.
AI is also reshaping the economics and architecture of banking, including by creating new demand for financing. Agentic AI could redefine how work is organized and decisions are made, both within enterprises and among consumers. At the same time, digital assets and tokenization are beginning to change how money and assets move through the financial system, paving the way for a new financial architecture.
For bank leaders, one challenge is to convert today’s momentum into tomorrow’s advantage: proving AI investment pays off, building new engines of growth around AI and digital assets, and strengthening resilience to keep up with emerging risks.
US banks poised to build on growth momentum in 2027
US banks should face a favorable macroeconomic backdrop in 2027, with GDP growth at 2.1%.1 As a result, lending will likely continue to expand, and could boost net interest income. However, this outlook remains sensitive to inflation and the trajectory of AI-related investments. Deloitte forecasts2 the effective federal funds rate should remain close to 3.63% through 2027. The US 10-year Treasury yield rose to above 5.00% in late September, its highest level since late 2002.3 The 2-year yield also increased, reflecting investor expectations regarding higher rates.4 Deloitte’s baseline has the 10-year holding above 4.5% through the end of 2027.5
Despite a higher-rate environment, loan growth should stay positive but uneven.6 Consumer lending will likely be more measured, with credit cards roughly steady and auto lending edging lower. Elevated interest rates and soft wage growth are having an impact on household balance sheets, weighing on spending and increasing debt burdens.7
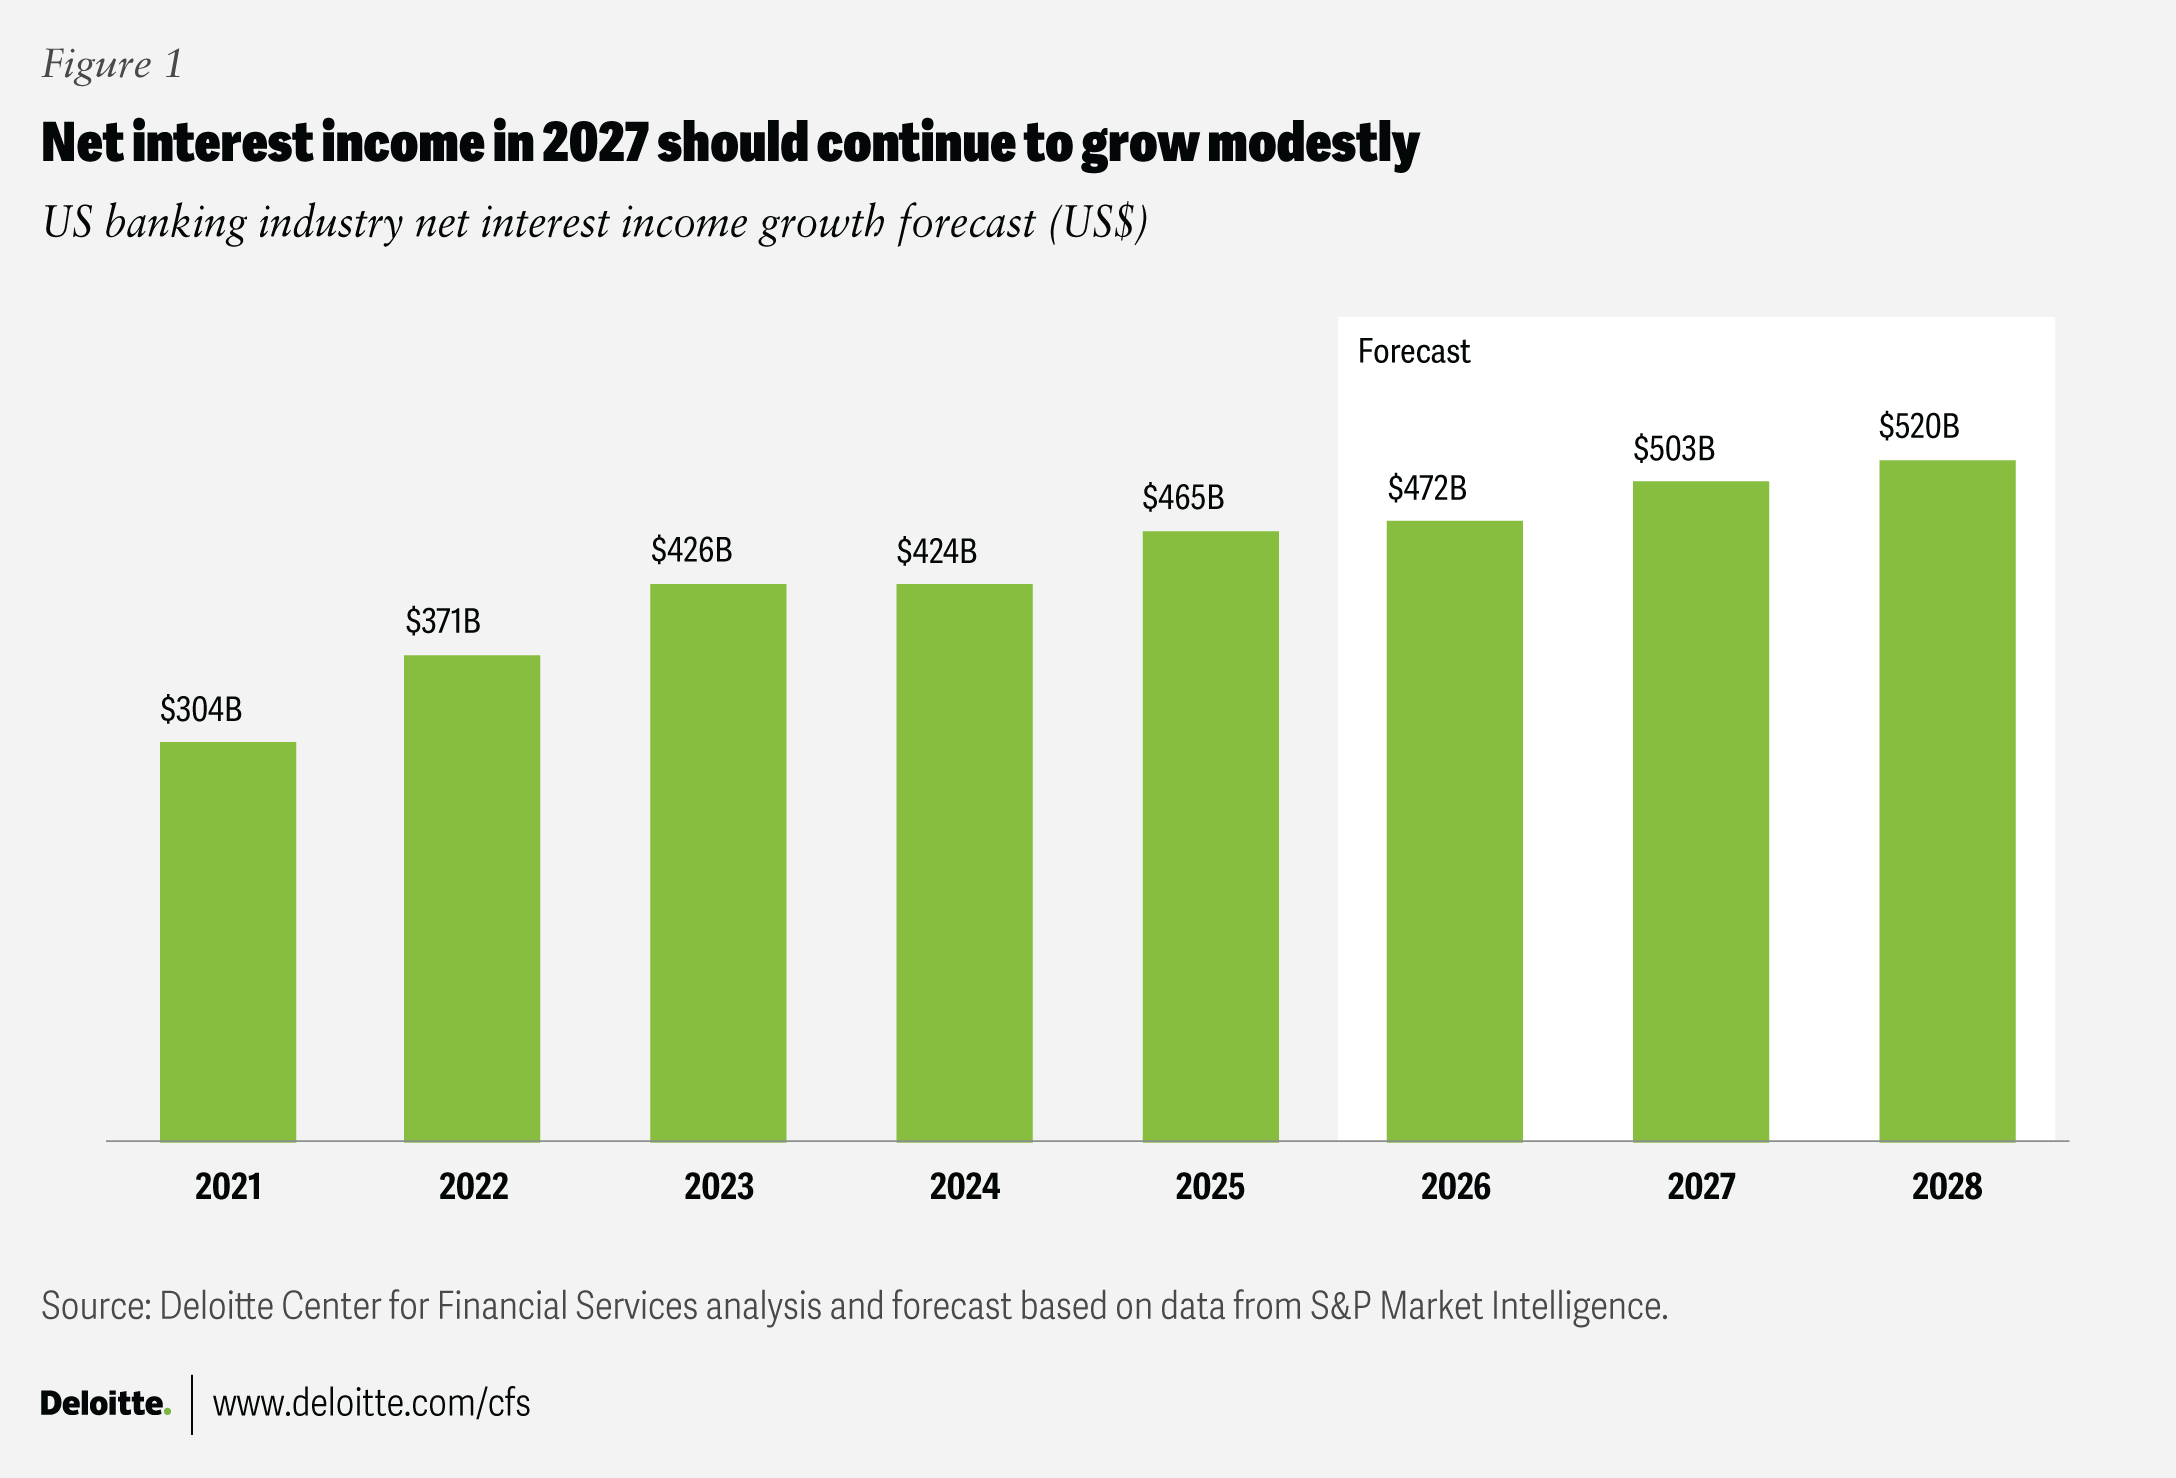
By contrast, corporations have sound balance sheets and continue to spend on AI projects.8 Commercial and industrial loans should remain resilient as banks benefit from a broad pool of corporate borrowers.9 While net interest income is expected to grow only modestly as rates stay high (figure 1), fee income could continue to be a growth driver in 2027,10 led by dealmaking, equity trading, and wealth management.11
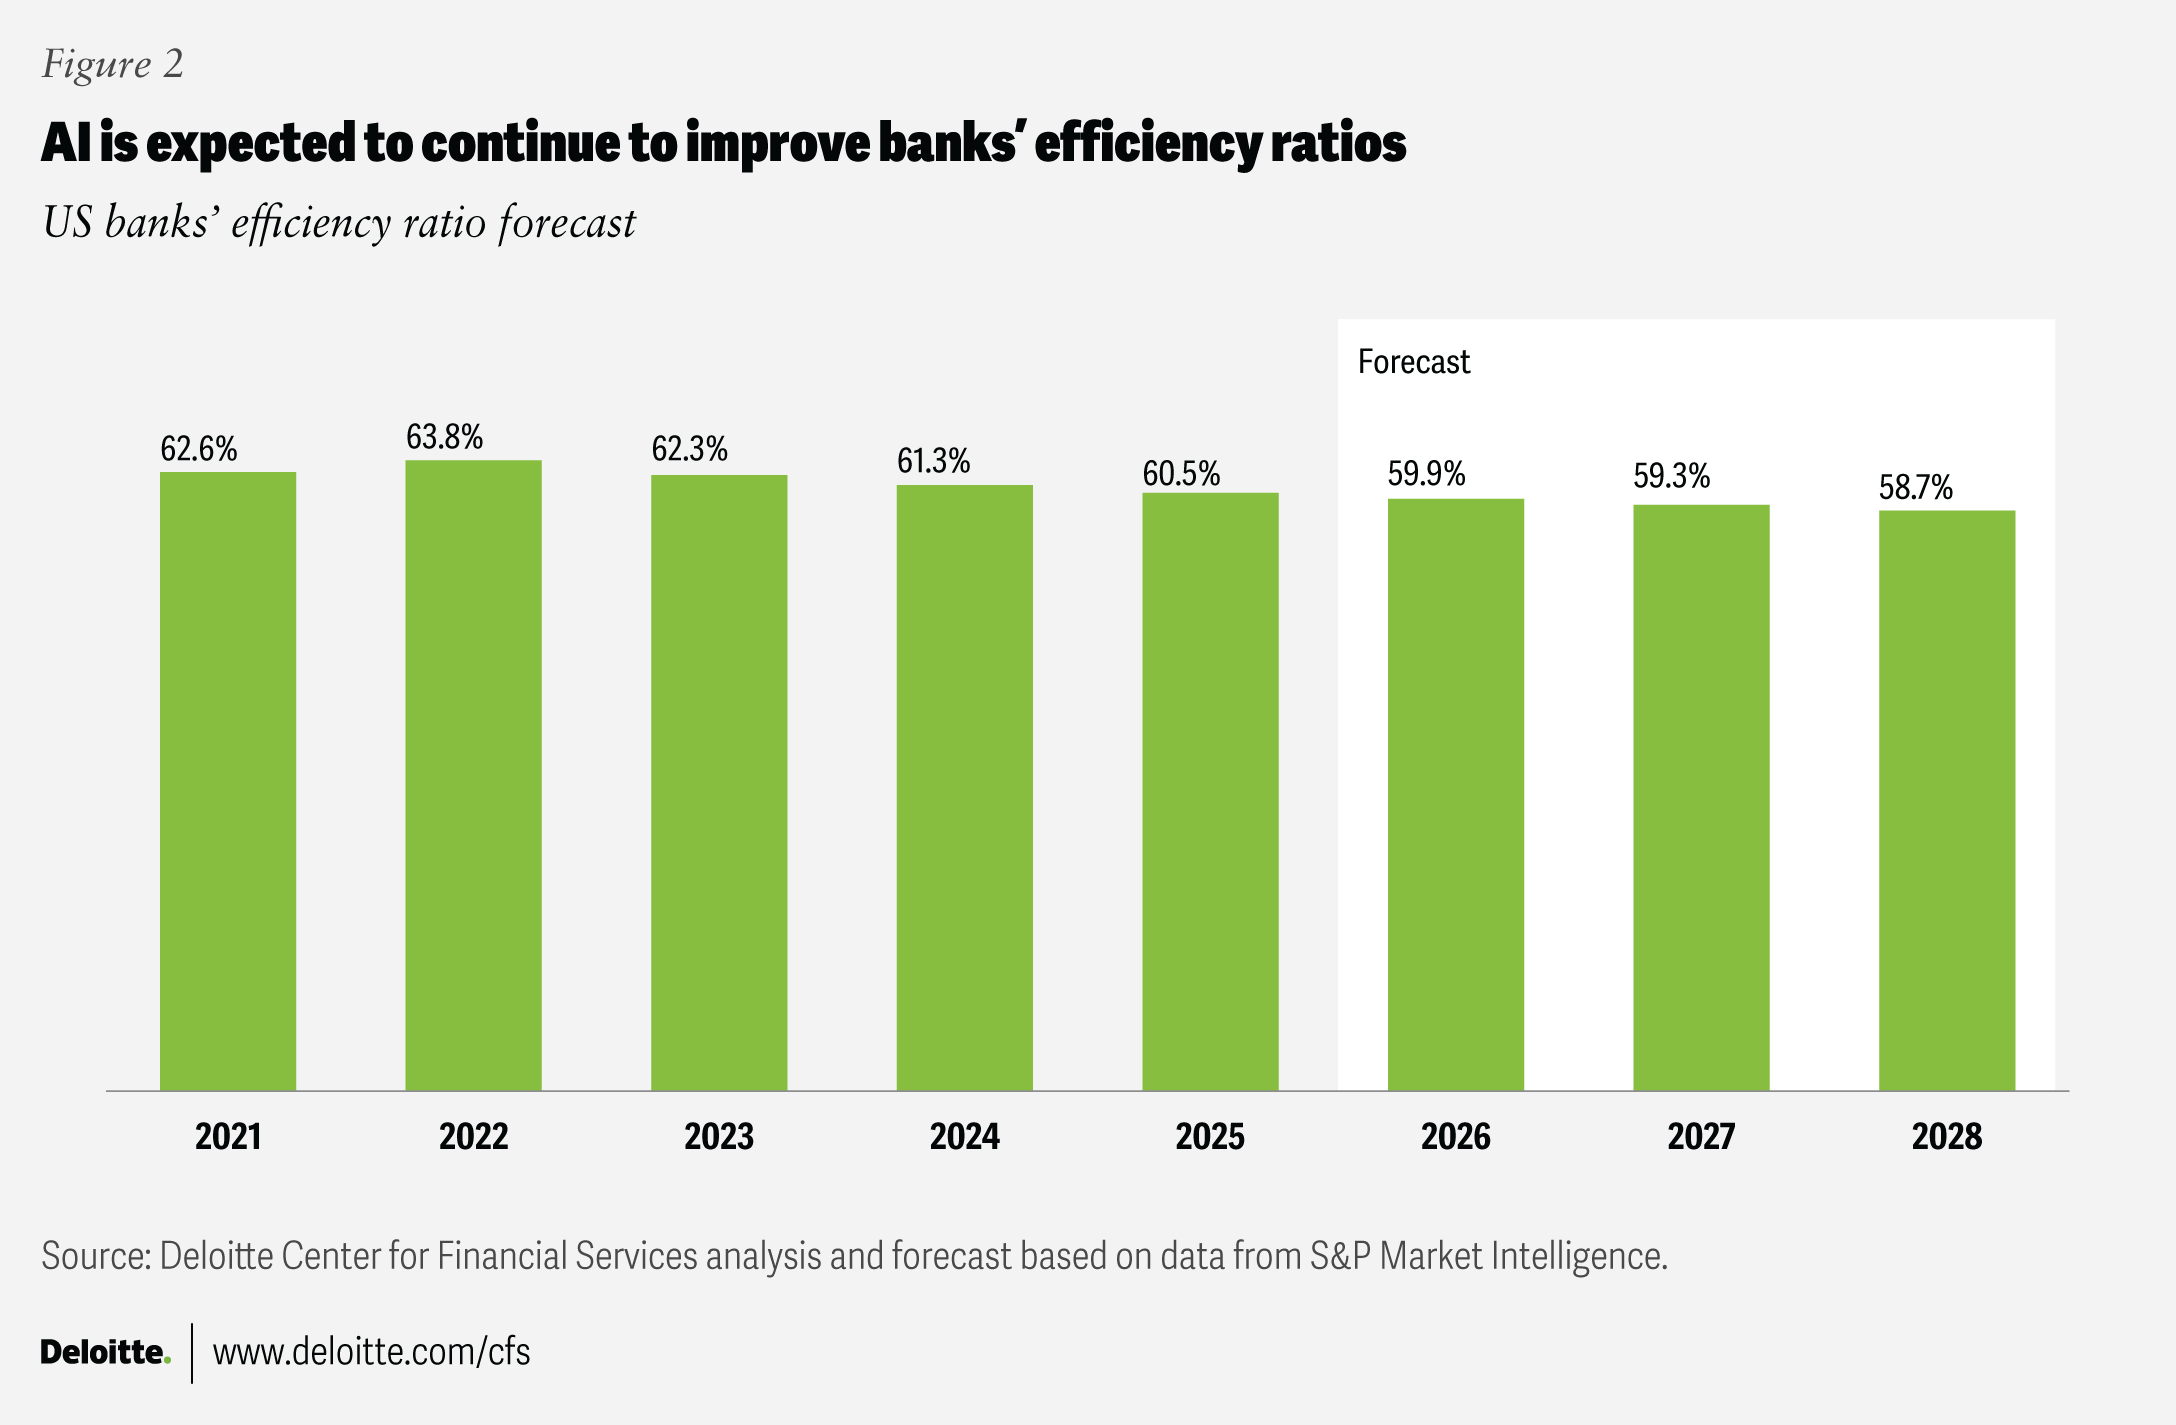
More broadly, AI’s growing influence on the economy will likely remain a key uncertainty for banks in 2027.12 A slowdown in AI-related capital spending could curb loan growth, weaken credit quality, and weigh on broader economic growth. At the same time, banks that deploy AI at scale may be able to lower efficiency ratios and improve operating leverage (figure 2).
Digital assets are poised to gain momentum in 2027, led by tokenized deposits, broader bank stablecoin offerings, and tokenized equities.13 Industry consortia and partnerships could provide a practical entry point for many banks. The emerging financial architecture could create new opportunities in payments, settlement, custody, and cash management, while intensifying competition for deposits as stablecoins redirect some balances outside traditional bank accounts.14
Converting AI investment into measurable value
Some banks have already seen value from AI investments in areas such as software engineering, know your customer, and fraud detection.15 Still, some executives will likely need to demonstrate the payoff from those investments in 2027.
Some banks appear focused on longer-term outcomes and may view AI as a sweeping rebuild of how they operate. These institutions may not be as concerned with short-term results. Whether they are focused on short- or long-term outcomes, banks can realize AI’s potential when they clearly articulate and prioritize their goals.
Banks may need stronger cost discipline as AI scales
The payoff from AI can be hard to demonstrate without rigorous cost discipline. Some chief financial officers and chief technology officers are focused on surging costs, and some banks anticipate a “meaningful acceleration” in token consumption.16 Industry estimates suggest that those costs will expand as agentic AI goes mainstream.17
To help address rising AI costs, banks could consider the following actions. Engineering can focus on model routing, prompt caching, batching, and context window management, using the combination of techniques that best fits each task’s cost and performance criteria. And finance departments can build a stronger discipline through financial operations: metering usage, charging costs back to the business units generating them, and forecasting spending by use case. Also, banks could consider setting AI access by employee role, making the most advanced models available only to those who need them to manage licensing costs.
From pay-per-token to owned infrastructure
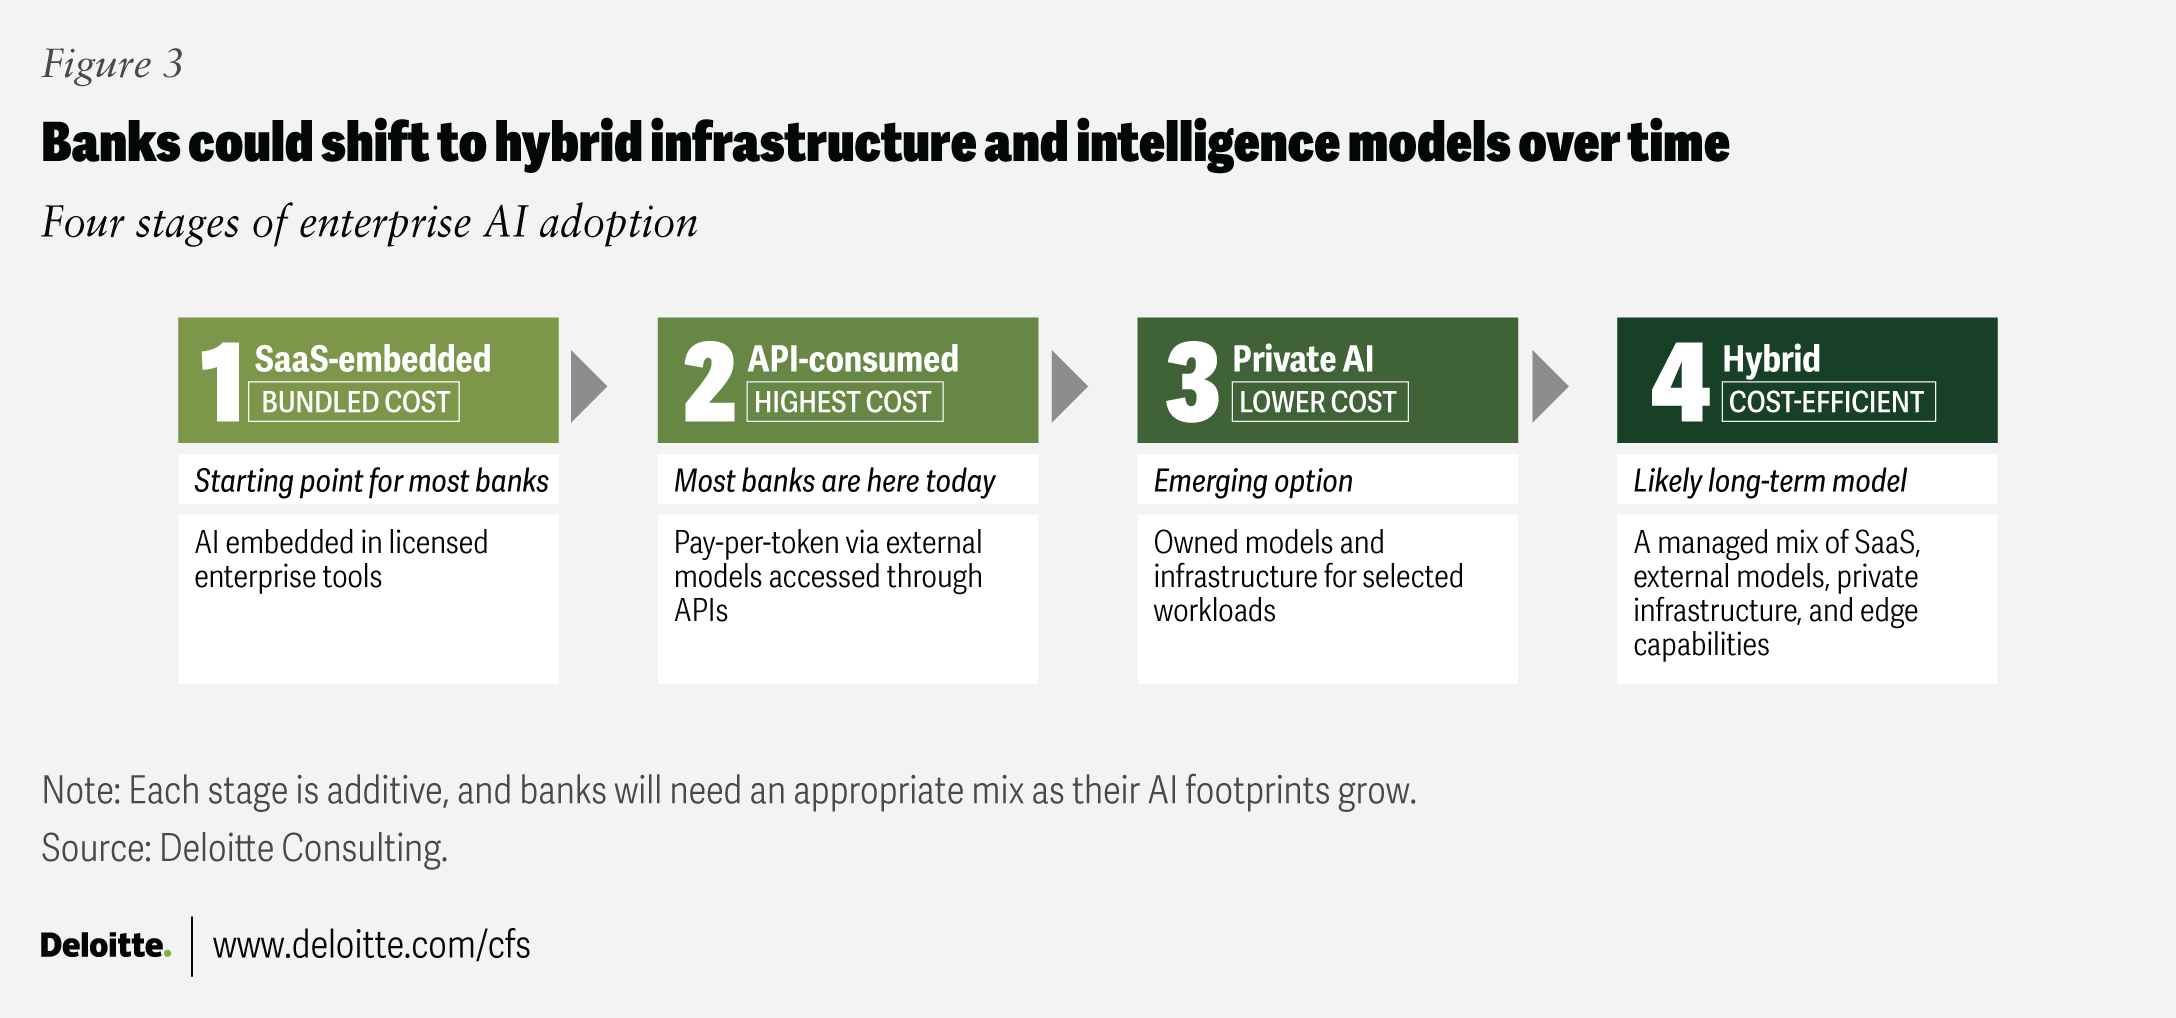
Banks’ AI adoption could follow a similar pattern to their use of cloud computing. Pay-as-you-go pricing could evolve into hybrid and private setups (figure 3), with banks running their own fine-tuned models on infrastructure they control: AI factories. Many banks are still in the pay-per-token stage,18 but this trend could shift.19
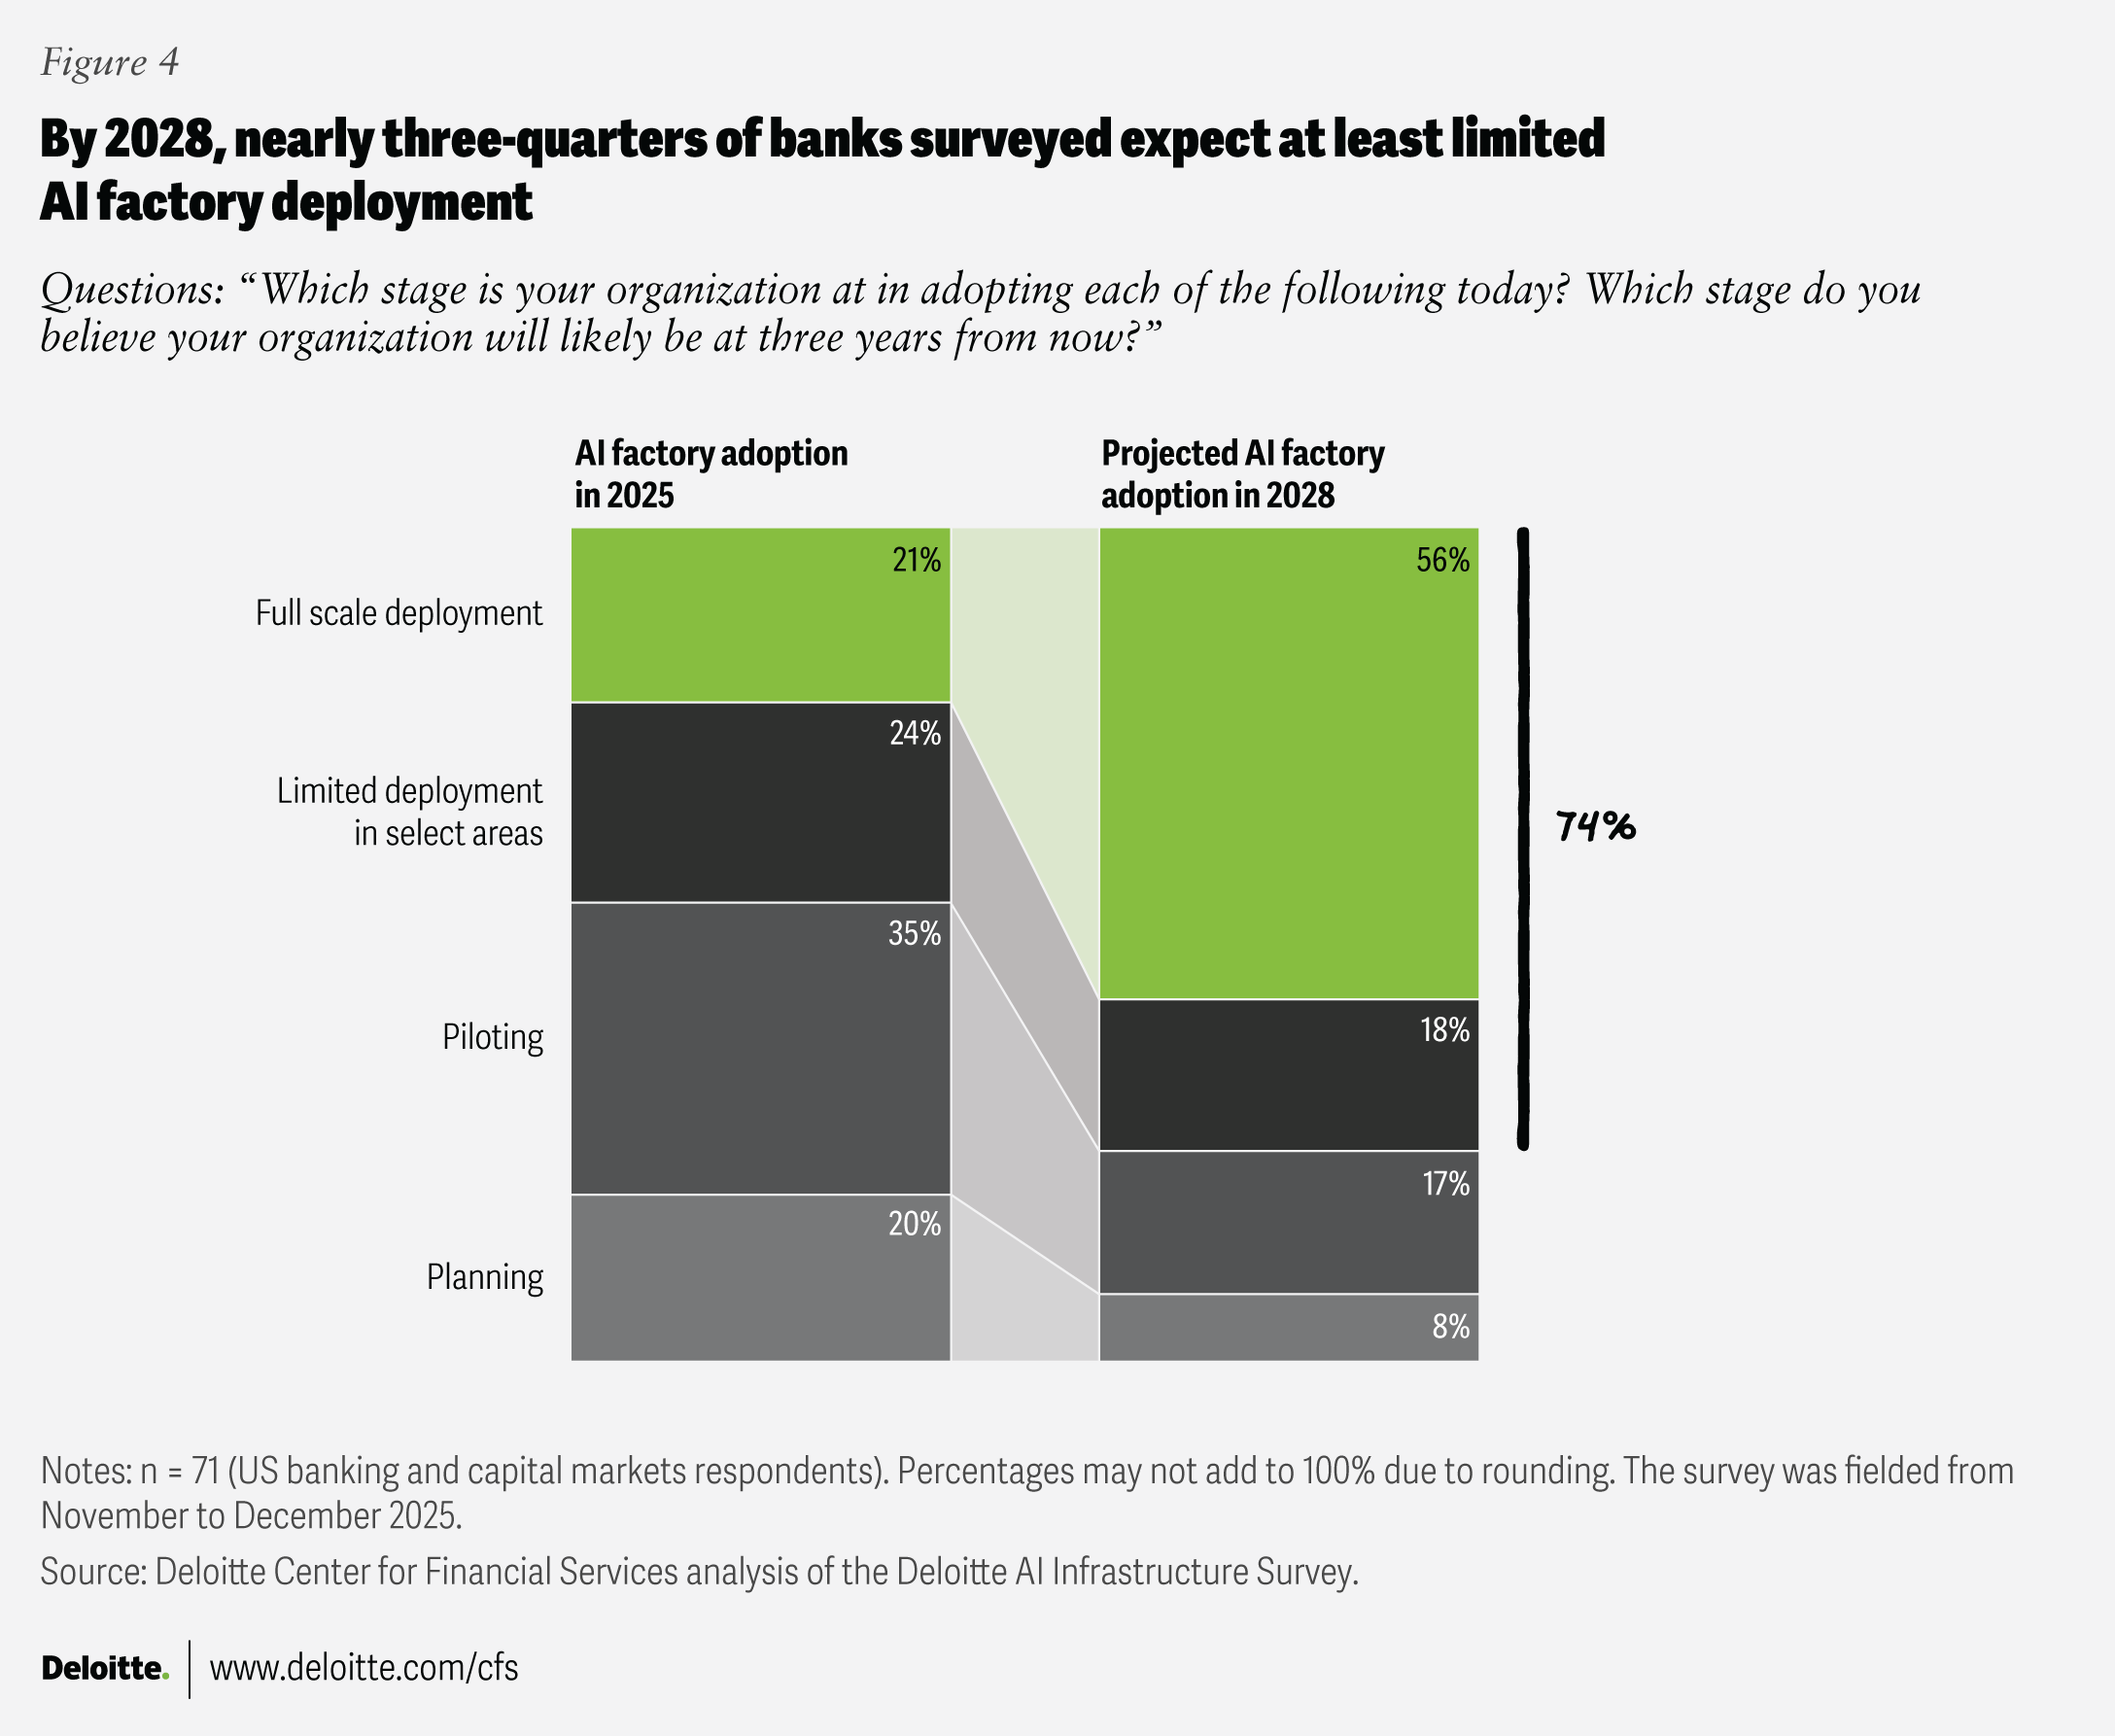
A Deloitte survey found that 74% of banking technology leaders surveyed expect to operate private AI infrastructure by 2028 (figure 4).21 A self-hosted AI factory could deliver more than 50% cost savings over three years compared with application programming interfaces (APIs), according to Deloitte forecasts.22
As token consumption expands, banks that want real control over costs, data, security, and performance should be deliberate about the infrastructure mix. This could mean moving beyond existing software-as-a-service and API-based arrangements, and in some cases bringing back some of the workloads they may have migrated to public clouds. Banks can choose between several models: capital-intensive on-premises infrastructure, on-premises infrastructure consumed on an operating-expense basis, or private infrastructure delivered through a cloud provider.
Ways banks can prepare for an agentic world
Some banks are already deploying AI agents.23 But for some, broader adoption may be impacted by legacy systems and fragmented data, lack of proper controls and governance, and internal resistance to changing existing workflows.
Also, some current agentic use cases appear to be internal, potentially due to risk and compliance concerns, and truly autonomous agents are rare for banks.24 Some banks seem to be bolting agent workflows onto existing processes, which could limit the advantages of these tools.25
Banks can extend existing risk frameworks through the agent harness: the layer of infrastructure wrapped around each model that handles identity and auditability, governs orchestration, and enforces the rules for when an agent can take action. Controls can include unique identities, least-privilege access, accountable owners, and defined transaction limits. Autonomy should be introduced gradually based on performance and risk.
Rewriting the growth playbook for the age of AI and digital assets
AI is already contributing to US economic growth,26 and it appears to be creating new growth paths for banks. While some are already participating in this expansion, what are some ways they could take advantage of future opportunities?
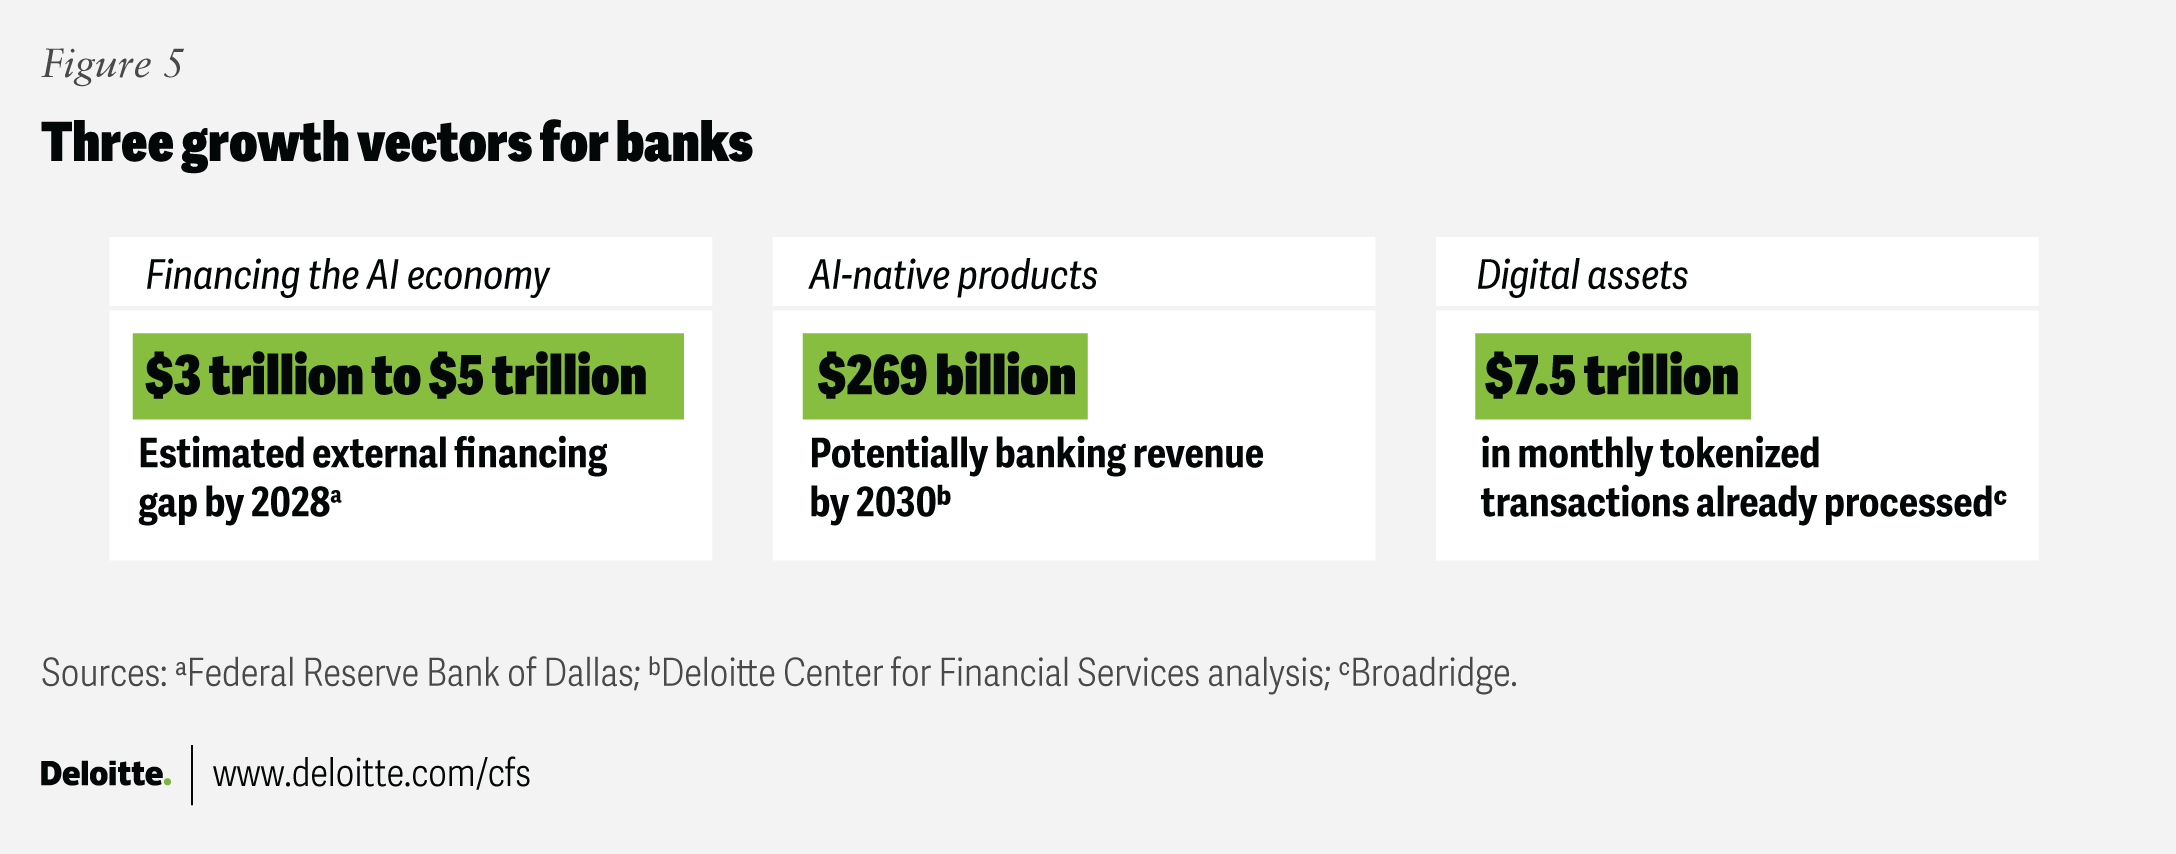
Banks can seek new opportunities to finance the expanding AI economy. They can also embrace AI-driven product and service innovation. And they can create value through digital assets (figure 5).
Financing the AI economy
Banks could help finance the AI economy. So far, AI financing—ranging from financing graphics processing units (GPUs) to underwriting compute contracts and structuring power infrastructure deals—has been led by large banks. For example, Goldman Sachs and JPMorgan Chase have served as the joint lead managers for close to US$3.6 billion in GPU-backed financing.27 Yet the potential financing need is far larger: Some estimates put the external financing gap for AI infrastructure between US$3 trillion to US$5 trillion in 2028.28
Such financing will likely demand new underwriting and structuring approaches. GPU depreciation—along with the risk that committed compute contracts end early, are not renewed, or go unpaid—does not fit neatly within traditional credit frameworks. And because AI capital spending is happening across industries, AI financing expertise should span multiple sector verticals within a bank and not sit in a single AI technology-coverage team.
The opportunity includes seed-stage relationships, growth-stage lending, structured facilities before initial public offerings (IPOs), post-IPO treasury, and mergers and acquisitions.
Embracing AI-driven product and service innovation
Banks could use AI to help accelerate innovation and create new products and services with AI built in from the start. Deloitte estimates AI-native products could play a major part in generating over $75 billion in revenues in institutional banking by 2030.29 AI is also changing how banks serve retail customers through hyper-personalization and agentic finance.
Banks should be selective in creating AI-native products. They could focus on offerings that are ready for AI, do not have high regulatory risk, and already have market demand, such as treasury orchestration platforms, intra-day liquidity optimizers, and continuous credit monitoring tools.
Another opportunity is using AI for hyper-personalization and tailored pricing to help banks to reach new segments. Similarly, advice can be offered proactively in the moment a customer actually needs it.
Agentic finance is another possible growth area, but it starts with verifying that customers have control over transactions. A recent Deloitte survey of US retail banking customers found that more than three-quarters said they would feel anxious about an AI agent taking action on their finances without their approval.30
These AI innovation opportunities will likely play out in a more contested market as nonbanks compete for the customer interface. Banks should focus on maintaining their role as trusted financial partners: A major data or AI failure could erode that trust and create advantages for competitors.
Creating value through digital assets
Digital assets are impacting financial architecture, from how money is held and moved to how assets are issued, settled, and financed. This shift could also create new growth opportunities for banks.31
Institutions that define how programmable money and tokenized assets are issued, exchanged, and settled are likely to benefit from this transition. On the money side, banks may pursue both tokenized deposits, which retain clients’ insured deposits, and stablecoins, which protect market share on rails that nonbank issuers would otherwise control. Reserve banking for stablecoin issuers can be an attractive place to start. On the asset side, there are opportunities in custody, servicing, and moving collateral in real time. For example, Broadridge’s Distributed Ledger Repo platform processed $7.5 trillion in repo transactions in June 2026.32
Strengthening resilience for a machine-speed world
Banks face three converging resilience challenges heading into 2027: Cyber threats are outpacing remediation cycles, forcing banks to move faster; operational resilience frameworks need rethinking; and the regulatory shift toward principles-based risk management.
Accelerating cyber remediation
Some banks have moved to address cyber risks from Frontier AI models, but the work is in progress. As AI adoption expands vulnerabilities and increasingly capable frontier and open-weight models equip adversaries just as quickly, cyber efforts will likely remain a priority for banks in 2027.
They should focus on four fronts: prioritize vulnerabilities based on exploitability and business impact, automate low-risk remediation, deploy compensating controls while fixes are underway, and enable faster decisions without weakening oversight.33 However, few banks have the in-house engineering capabilities to implement these measures alone, making third-party alliances important to help bolster cyber defense.
Rebuilding resilience for a different kind of failure
Many banks have built resilience capabilities over the past decade. But today’s threats, dependencies, and speed of disruption require those capabilities to evolve to address a very different set of risks.
Many banks have mature testing programs. But mature testing does not always mean real-world readiness. Some tests demonstrate compliance rather than how systems, teams, and third parties may respond to a live disruption. Banks should implement realistic exercises, continuous validation, and fast feedback loops.
Accountability should be stronger. Cyber incidents require a coordinated response across technology, operations, business continuity, and risk, with clear decision rights, handoffs, and escalation paths. Senior management and the board should remain accountable for the overall response.
Many banks have immutable backups, yet coverage of critical systems and recovery testing can still fall short. Banks should focus backup investment on the systems that matter most and test their recovery capabilities before an actual incident occurs.
AI adoption is moving faster than governance. Heavy reliance on a small group of models and vendors can create shared points of failure across banks. Managing this concentration risk, model access, and data lineage should be a core resilience priority.
Redefining the three-lines model
US regulators appear to be giving banks more flexibility in how they manage risk while holding them accountable for resilience across their full ecosystem, including third parties.34 This more principles-based approach can allow institutions to build scalable risk-management frameworks suited to their operating models and risk profiles.35
Under this tailored approach, business owners in the first-line function embed risk management into day-to-day operations. Second-line teams, including risk, compliance, and control functions, focus on enterprise exposure, challenge key decisions, monitor outcomes, and target independent testing rather than re-verifying the same controls.
Internal audit, as the third line, serves as an independent validator of regulatory remediation and provides rigorous challenge to the first and second lines. It should also take a forward-looking view, helping assess changes to risk frameworks and identify emerging risks early.
Examiners are raising the bar for what warrants a formal finding, with greater focus on financial materiality than issue volume. Banks that proactively identify and remediate issues before examinations may be better positioned to stay ahead of supervisory expectations.
Bold choices for a new era
Banks will likely be challenged by uneven growth in 2027. Corporations and AI firms could fuel business, while consumer demand may become more muted. In this environment, banks may need to be selective about capital deployment, AI investments, and growth areas.
A question for bank leaders to consider is how to turn investments into durable advantage. AI is increasingly transforming banks’ businesses, as well as the broader economy, and digital assets are playing a role in reshaping financial infrastructure. Banks that can convert capital and technology investment into growth, while strengthening resilience along the way, may be well positioned to pull ahead in 2027.
Continue the conversation
Meet the industry leaders
Michelle Gauchat
Lananh Nguyen
Val Srinivas
By
Michelle Gauchat
Val Srinivas
Samia Hazuria
Shivalik Srivastav
The authors would like to thank the following Deloitte professionals for sharing their insights and perspectives during the development of this outlook:
Across chapters: Garrett O’Brien and George Black
Macroeconomics: Ira Kalish and Michael Wolf
AI chapter: Prakul Sharma, Matt Jacobs, Jatin Dave, Anshul Wadhawan, and Vaibhav Sathe
Growth chapter: Jim Delbridge and Nick Cowell
Risk and resilience chapter: Cliff Goss, Anish Srivastava, Maxwell Kruger, Deepak Goyal, Paul Meynen, Dineshbabu Dhandapani, Jason Kwak, Nandhakumar Thangavelu, and Shaun Nabil
Additionally, the authors would like to acknowledge and thank the Deloitte Insights, marketing excellence and public relations teams.
Editorial (including production and copyediting): Aditi Rao, Arpan Saha, Aparna Prusty, and Cintia Cheong
Cover image by: Alexis Werbeck; Adobe Stock
Design: Molly Piersol
Knowledge services: Rishitha Bichapogu
Visit the Deloitte Center for Financial Services
Access more insights for the banking & capital markets, commercial real estate, insurance, and investment management sectors.