
More Gen Z borrowers report carrying credit card debt while investing in stocks
A tougher entry-level job market and easier access to credit and investing apps are among the forces reshaping how Gen Z manages money
Many young people in the United States are racking up interest on their credit cards at the same time as wanting to buy more stocks, according to Deloitte’s ConsumerSignals survey, an online consumer panel fielded monthly that highlights the financial priorities of 1,000 US-based respondents.
Gen Z isn’t the first generation to juggle debt and the desire to build wealth. But they are carrying balances more than other generations did at the same age.1 Their financial life is taking shape in an uncertain entry-level job market. Recent college graduates have faced higher unemployment than the national average since 2019. This year, that gap widened to one of its largest since 1990.2 What’s different, too, is timing: “Buy now, pay later” and low-friction investing apps were already mainstream by the time most of Gen Z started managing their money.
The survey results illustrate the unique money habits of Gen Z adults, which are prompting financial firms to change their approach to appeal to younger consumers. “Gen Z is trying to balance financial discipline and optimism,” says Stephen Rogers, managing director of the Deloitte Consumer Industry Center at Deloitte Services LP, which fields the ConsumerSignals survey. “The job market has made the short term feel unstable, so they’re borrowing to get through it. The long term still feels investable, so they’re funding that too. That’s not a paradox. That’s what rational behavior looks like when you’re uncertain about the next 12 months but still believe in the next 20 years.”
Adds Michelle Gauchat, Deloitte’s US banking and capital markets leader at Deloitte Consulting LLP: “Gen Z is spending, saving, and investing differently than other generations in part because they grew up with smartphones at their fingertips. Our clients are really focused on how to serve this group of digital-savvy customers.”
More Gen Z consumers are holding credit card balances for more than a month
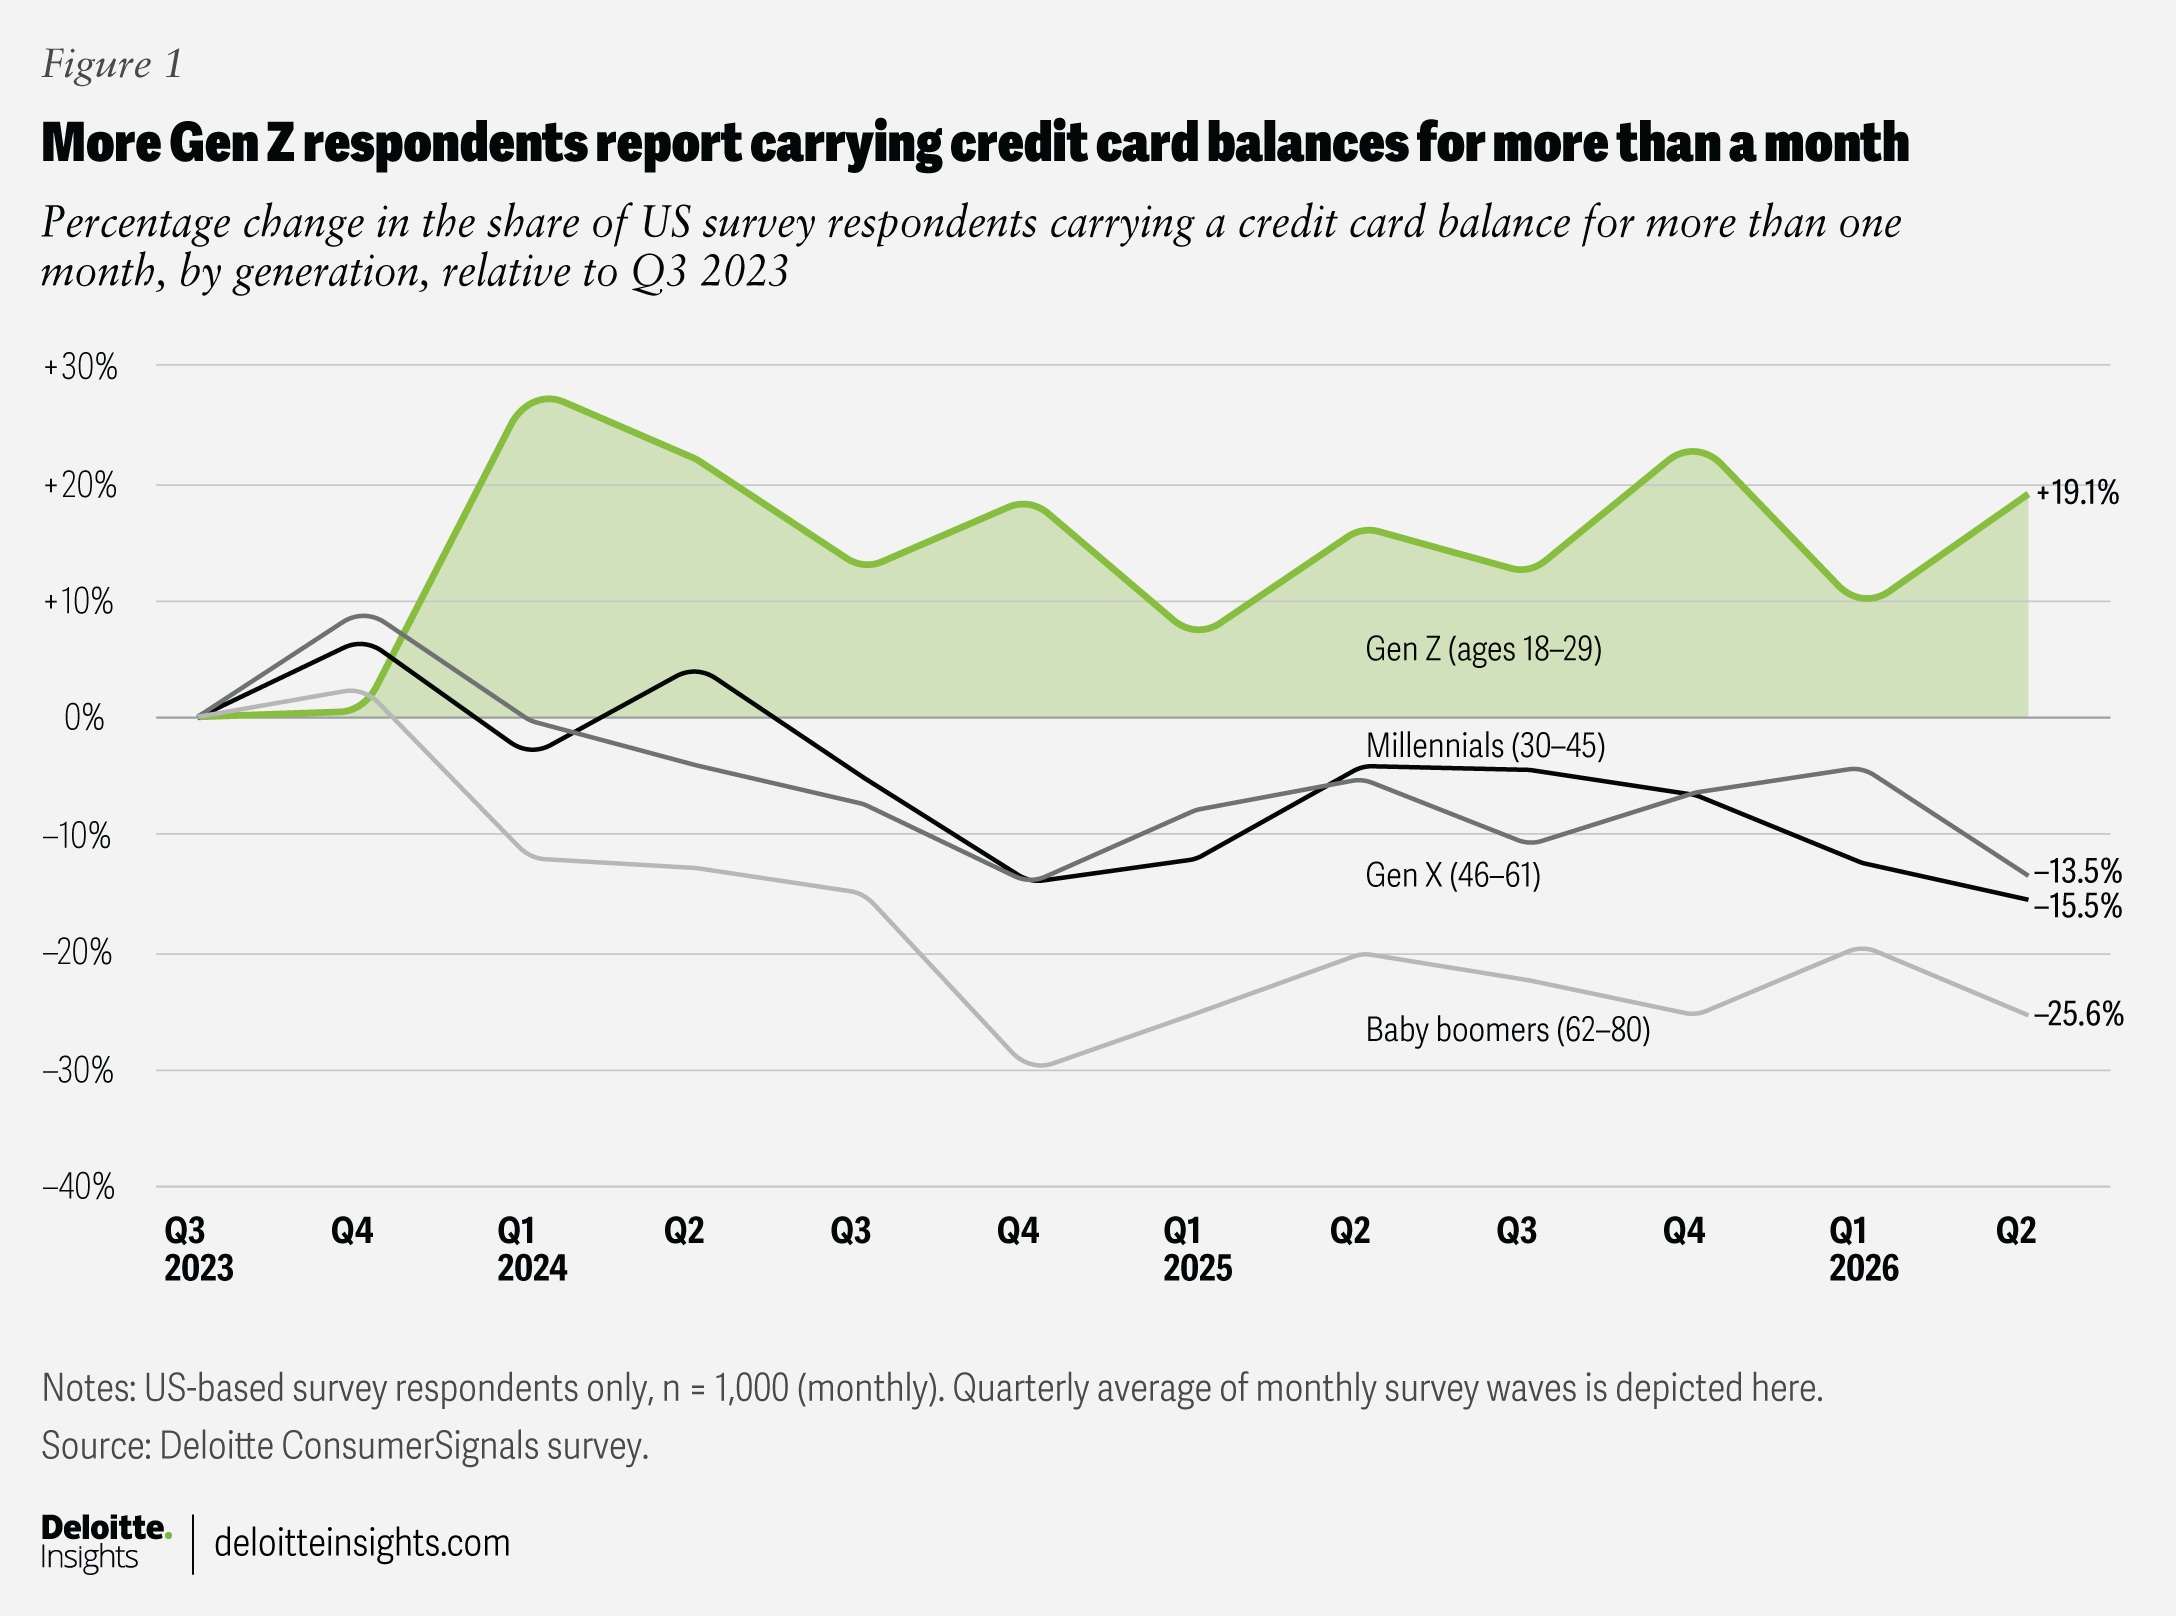
While respondents from other generations appear to be more actively managing their debt, our June 2026 survey findings indicate that an increasingly larger share of US-based Gen Z borrowers age 18 and up are carrying credit card balances for more than a month (figure 1). From Q3 2023 to Q2 2026, that share rose almost 20% for Gen Z while declining across all other generations.
Gen Z is also the fastest-growing segment of BNPL borrowers
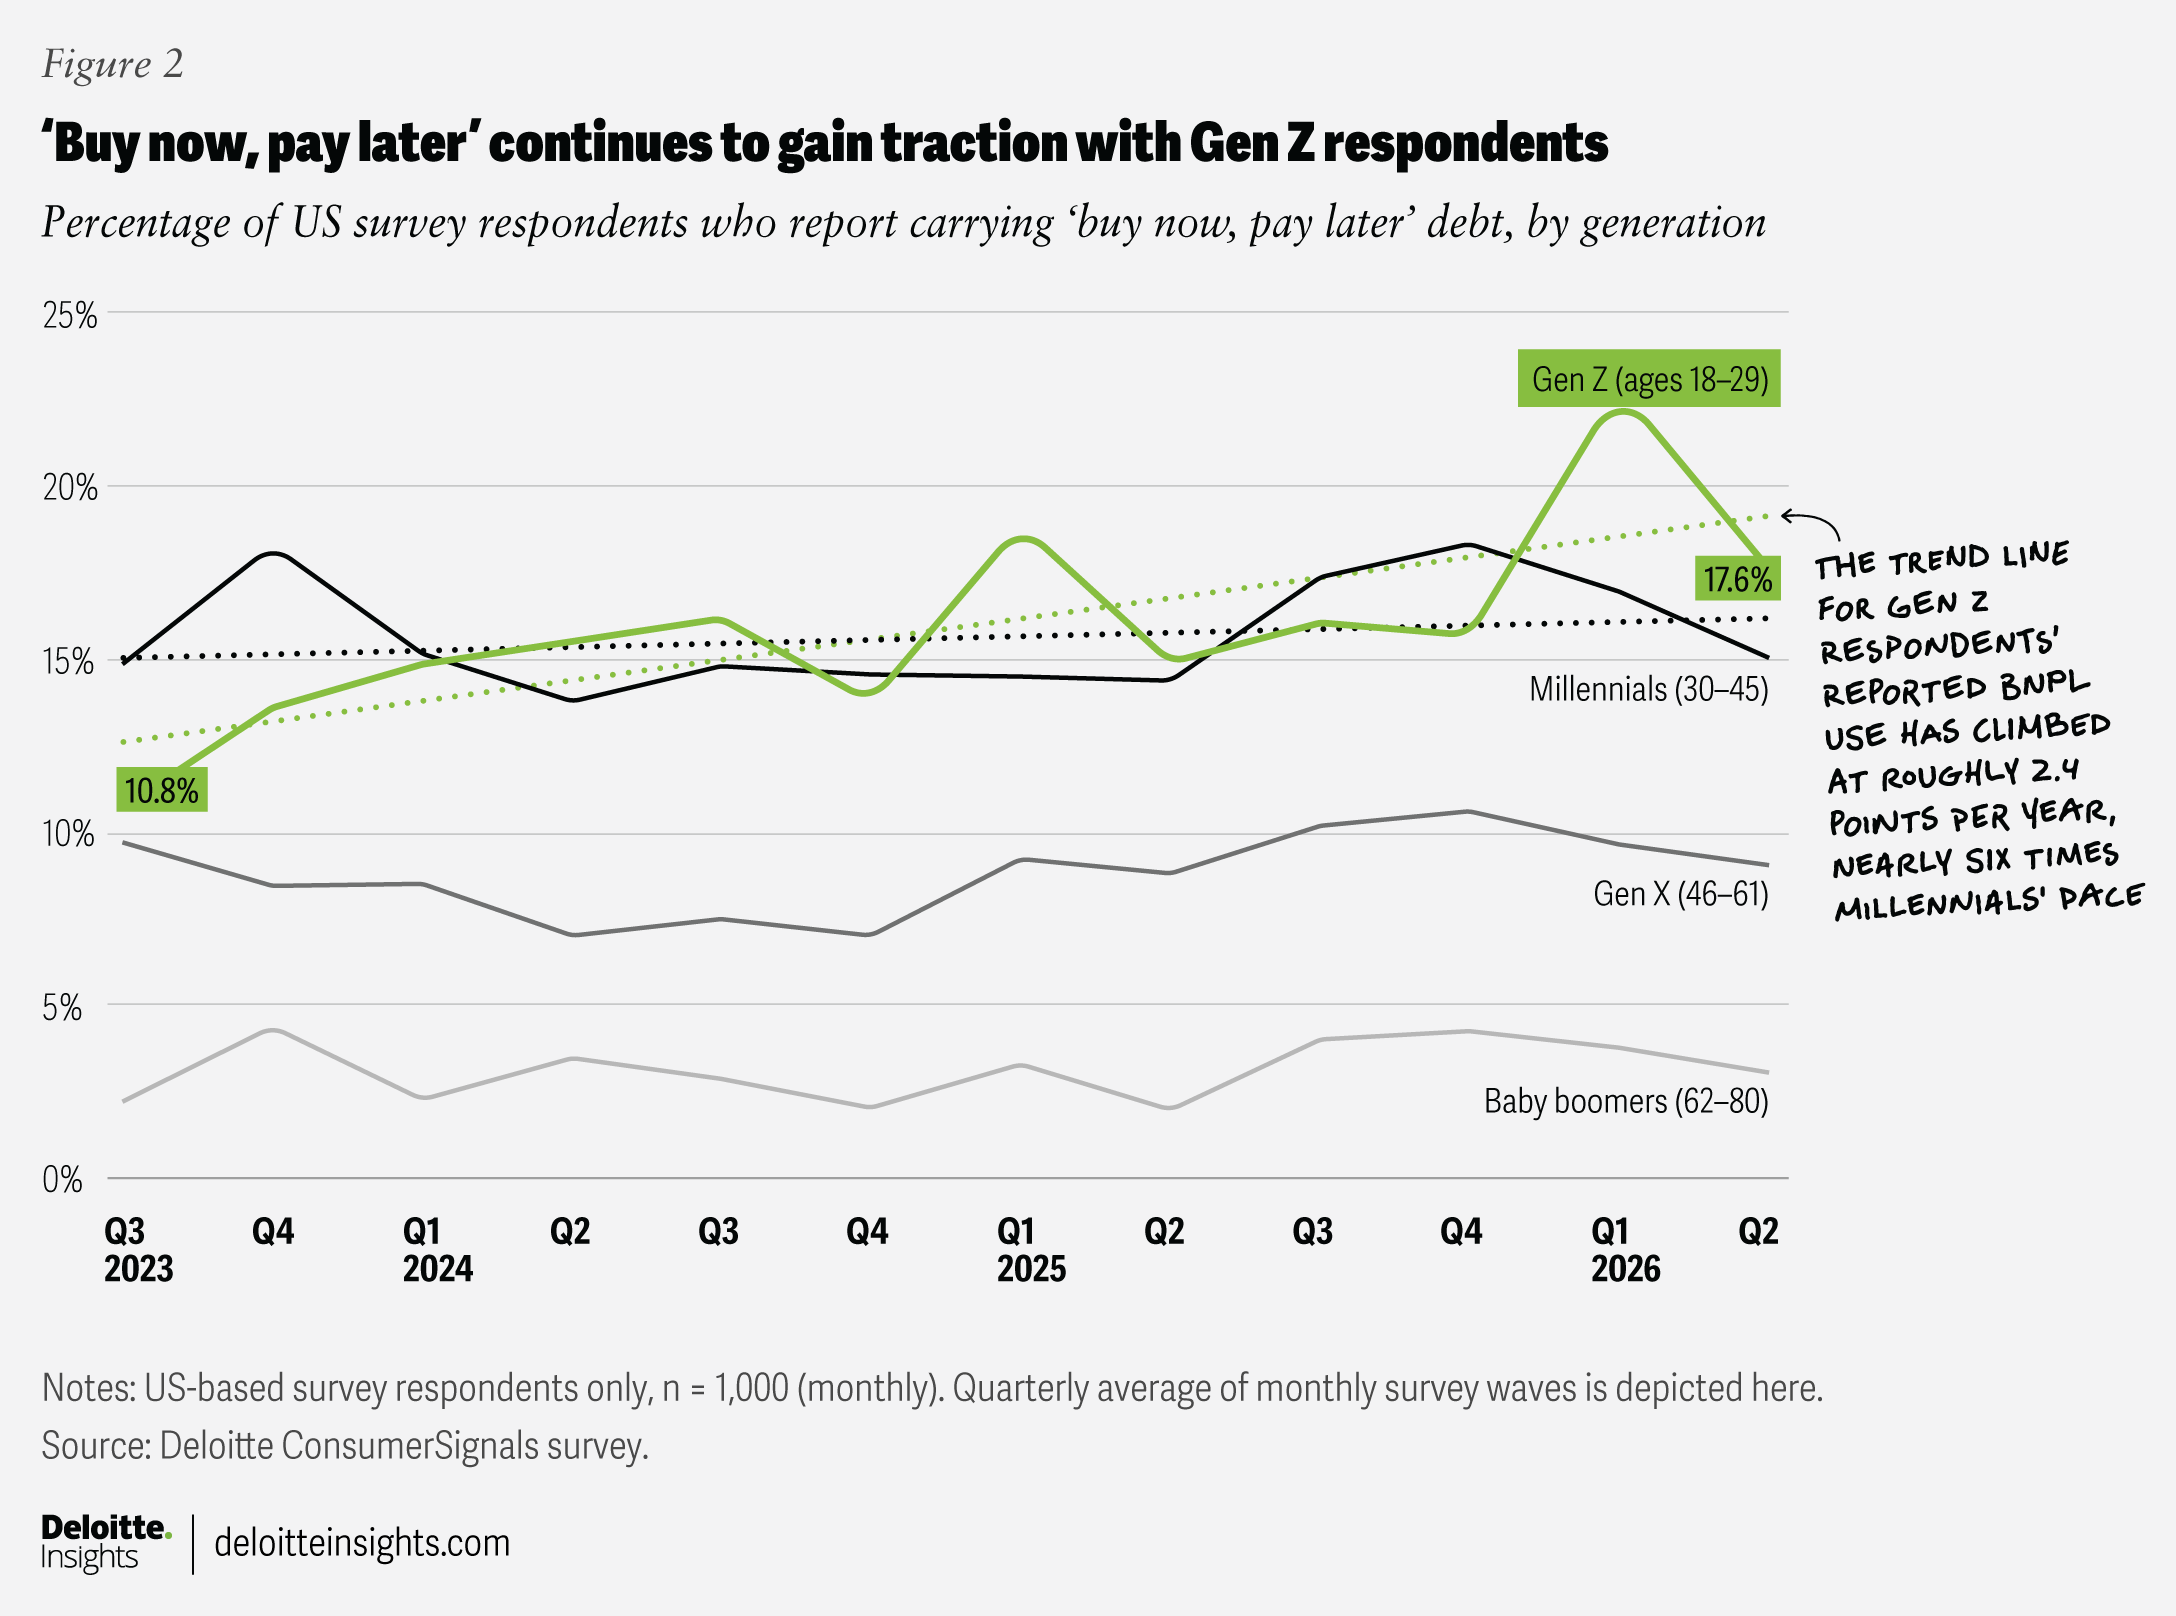
The share of Gen Z respondents using “buy now, pay later” (BNPL) services surged to 22.8% in the first quarter of 2026, the highest level of any generation tracked in three years of data, before easing to 17.6% in the second quarter (figure 2).
Gen Z is fast outpacing other generations in its adoption of BNPL, and other Deloitte research suggests that these consumers could be seeking not just current access to items, but also access to more spending power: Deloitte’s BNPL report found that, across all generations, 27% of shoppers used BNPL to buy items they’d otherwise have delayed, and 15% opted for pricier purchases than planned.3
Gen Z respondents are more uncomfortable with their credit card debt than other generations
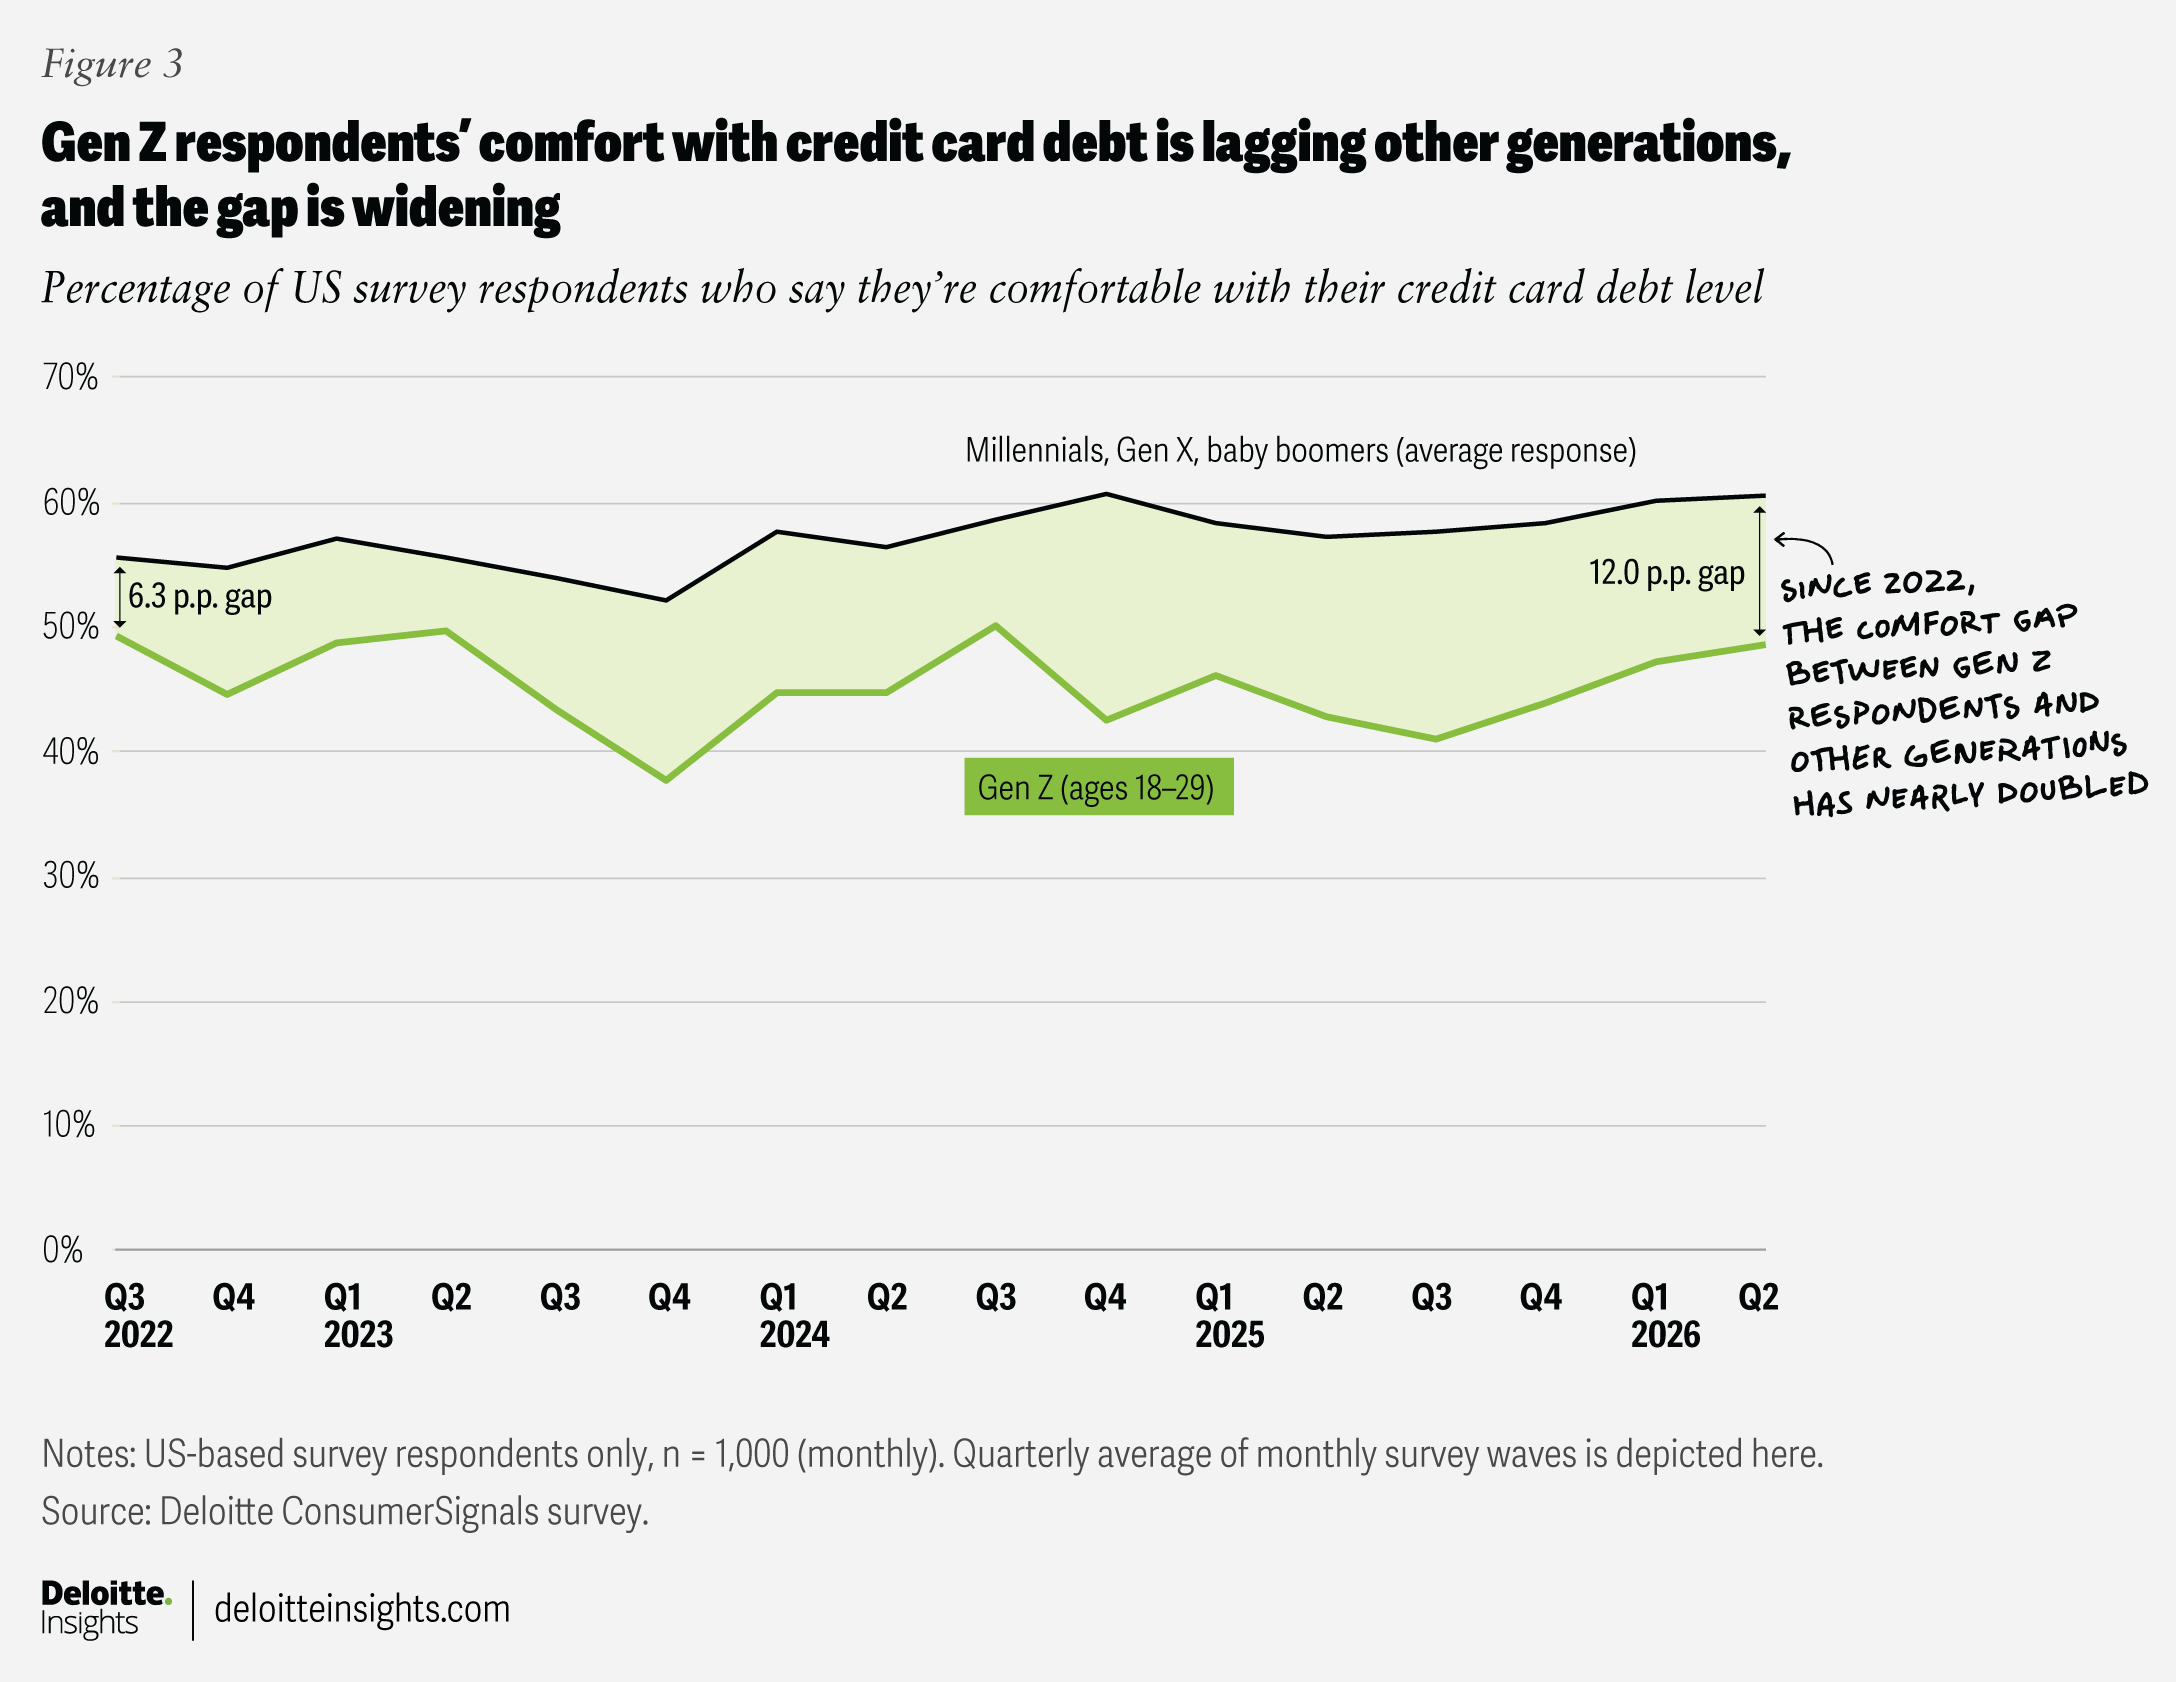
Gen Z respondents’ reported level of discomfort with their credit card debt has remained mostly unchanged across survey periods. However, over the past four years, other generations have grown more comfortable with their credit card debt, nearly doubling the gap in generations’ comfort levels, our survey shows (figure 3).
Gen Z respondents say they’re borrowing in the short term, but they also seek longer-term stock gains
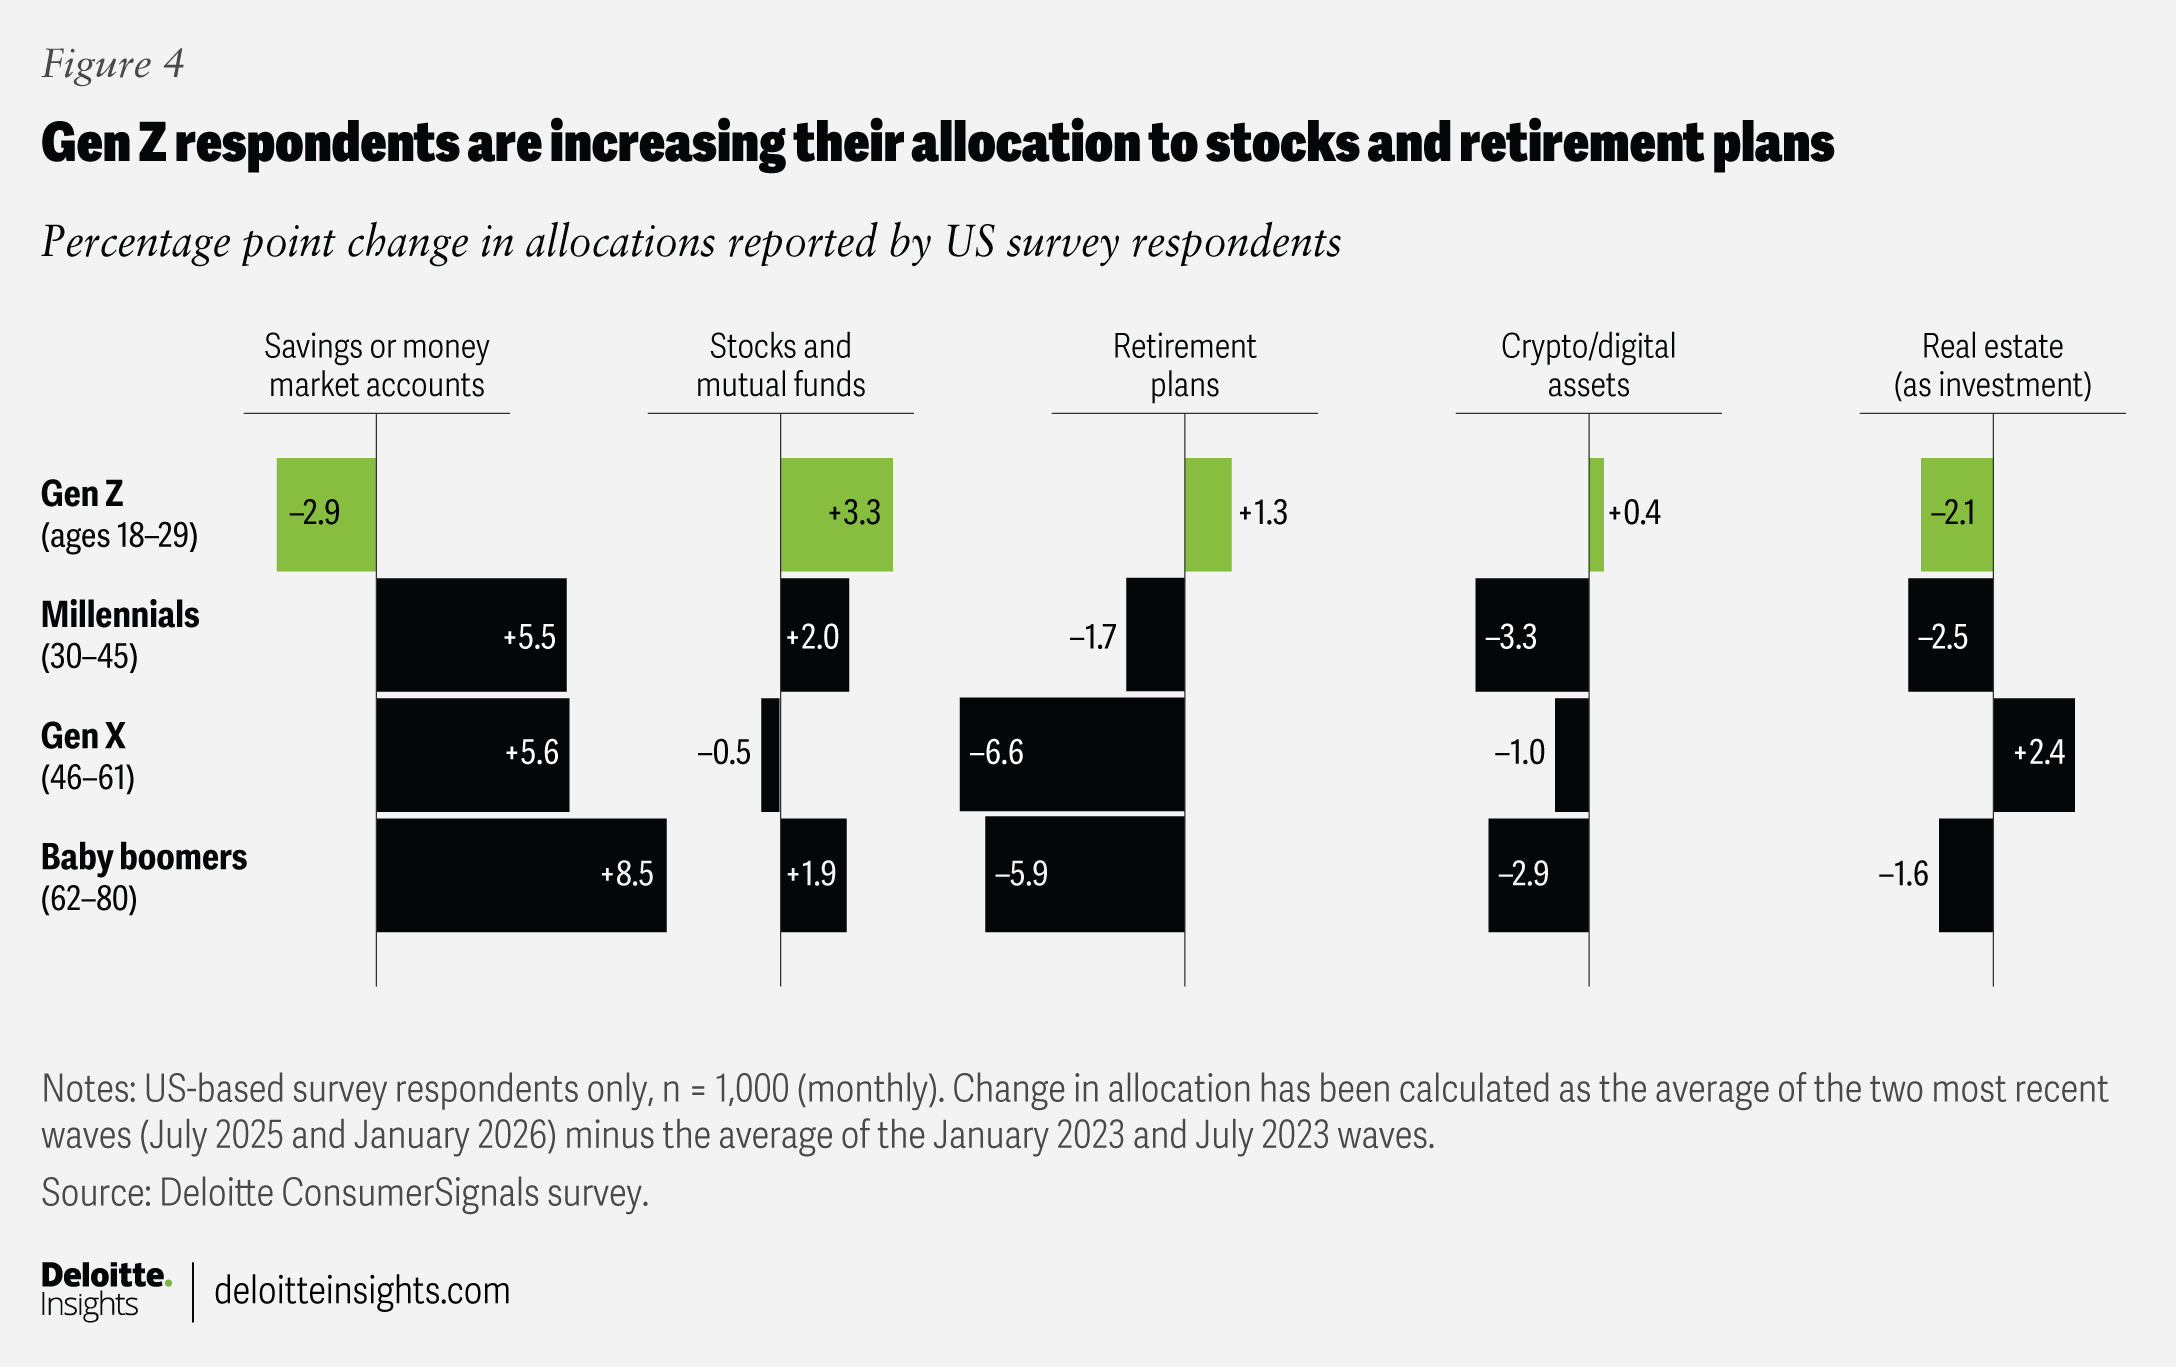
According to our survey, Gen Z respondents plan to allocate a larger share of their savings and investments to stocks, mutual funds, and retirement plans than they did three years ago (figure 4). Meanwhile, millennials, Gen X, and baby boomers plan to shift more toward cash over the same period. Gen Z respondents’ planned allocation to crypto has remained roughly stable, while respondents from other generations plan to pull back compared with survey results from 2023.
According to the survey, Gen Z appears to be managing their finances in novel ways, with short-term borrowing and long-term saving behaviors that could present opportunities for financial services firms to better meet young customers’ needs.
Continue the conversation
Meet the industry leaders
Michelle Gauchat
Lananh Nguyen
By
Michelle Gauchat
Samia Hazuria
The authors would like to thank Lananh Nguyen and Patricia Danielecki of the Center for Financial Services, Stephen Rogers of the Consumer Industry Center, and Elisabeth Sullivan of Deloitte Insights for their meaningful contributions to this article. They would also like to extend their sincere appreciation to Marcello Gasdia.
Additionally, the authors would like to acknowledge and thank the marketing excellence and public relations teams.
Editorial (including production and copyediting): Elisabeth Sullivan, Aditi Rao, Sayanika Bordoloi, and Anu Augustine
Design: Alexis Werbeck and Molly Piersol
Cover image by: Molly Piersol
Knowledge services: Agni Wagh
Visit the Deloitte Center for Financial Services
Access more insights for the banking and capital markets, commercial real estate, insurance, and investment management sectors.