
Keeping pace with prices: 2026 Deloitte Corporate Travel Study
Budgets grow to accommodate costlier trips, and buyers continue to invest in new traveler tech
Corporate travel spend appears to be expanding in 2026—not because companies are taking more trips, but because the same trips cost more.
The broader economy offers little clarity on why now. Employment and manufacturing output have grown all year, although manufacturing output slowed. Labor force participation has softened, and concerns about both cost and consumer demand persist. Real gross domestic product grew in the first half of 2026, but decelerated in the second quarter.1
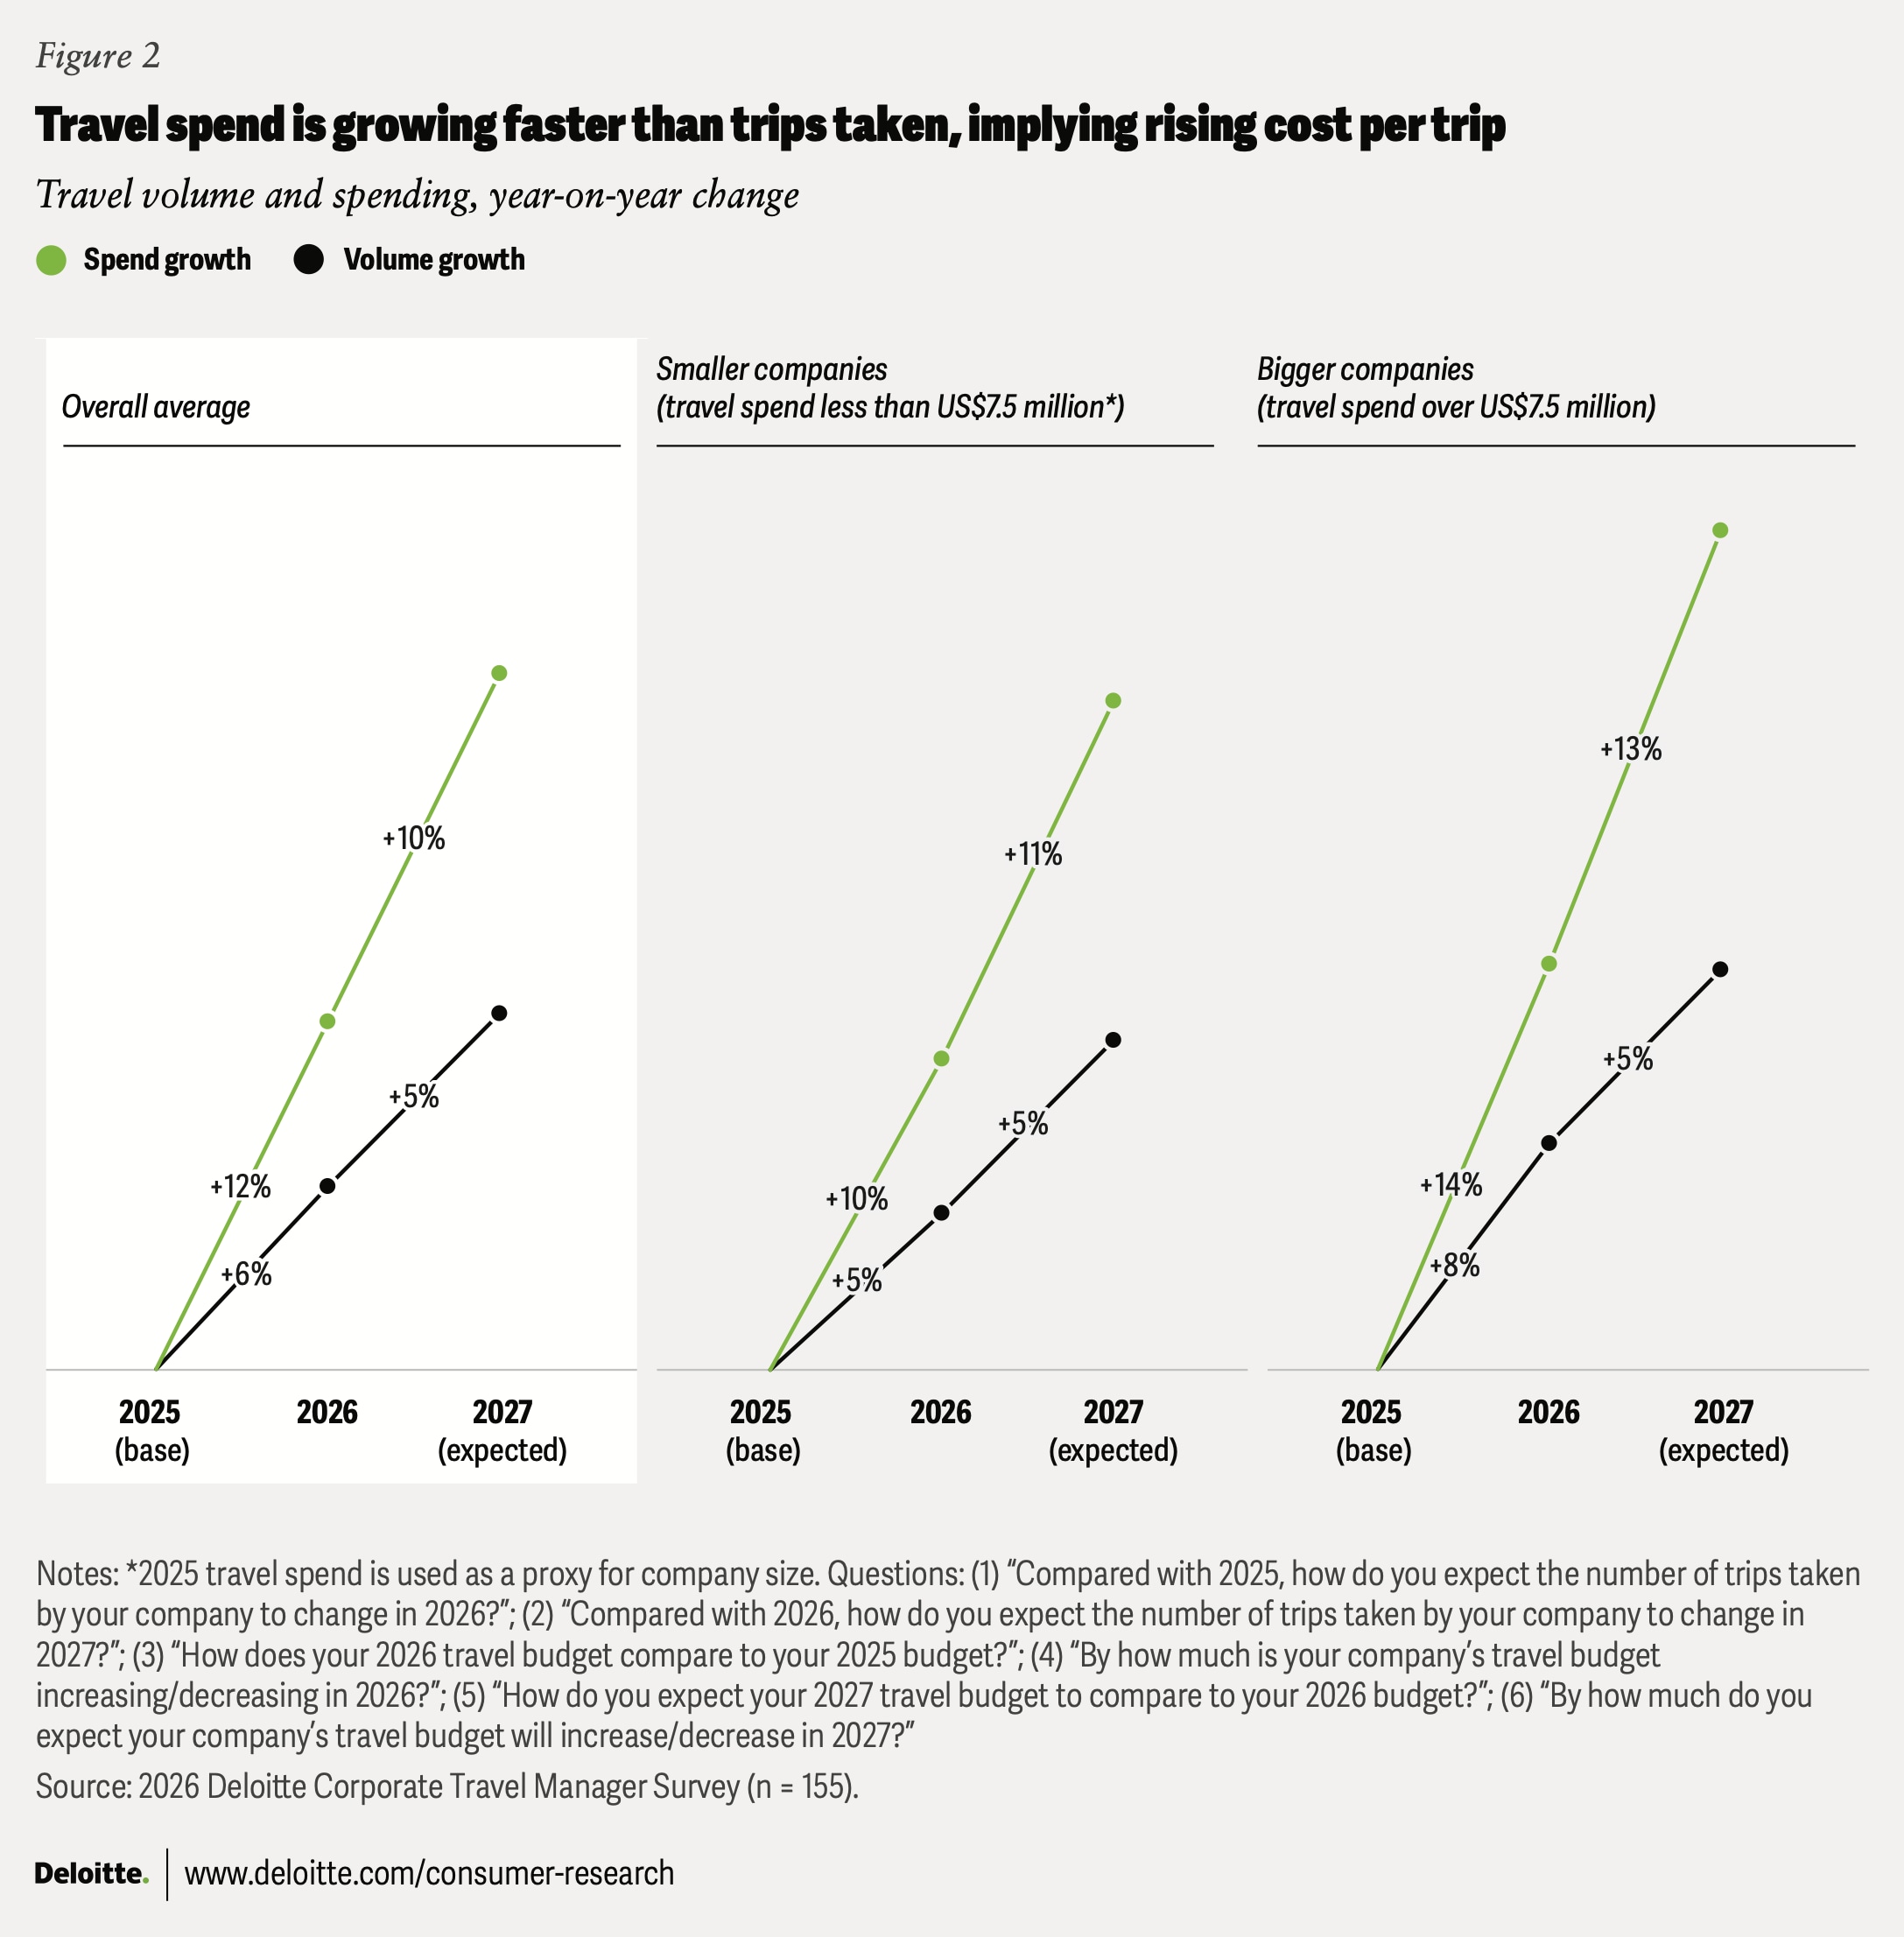
Against that uneven backdrop, business travel spend is climbing. Deloitte’s annual survey of about 150 US-based travel managers (one of two surveys supporting this report; see methodology for more information) points to an average budget increase of 12% in 2026, moderating to an expected 10% in 2027. But spend is rising at roughly twice the rate of trip volume. Most of the added budget is being absorbed by higher prices, not funding a real expansion in travel.
Airfare accounts for much of the increase. Representing close to 30% of the average travel budget, airfare rose well ahead of inflation this year. According to an analysis of corporate bookings by Prime Numbers Technology, domestic corporate fares climbed 18%, while international fares rose 13%.2
Rising costs may influence who gets on a plane, which trip types keep growing, and how buyers negotiate with vendors, but they are not, so far, driving broad cuts to trip volume or to the traveler experience, according to respondents. After the COVID-19 pandemic-era travel pullback and a recalibrated recovery, most corporate travel programs are likely already lean, and companies may be wary of cutting comfort further after already trimming it once.
As they balance growth and restraint, corporate travel managers continue to turn to technology. Steady, broad-based investment in travel tech is becoming the primary tool respondents’ companies use for managing costs while protecting trip volume or comfort.
Growth and the layers under it
After a 2025 marked by moderate growth, economic uncertainty, and tighter scrutiny of discretionary trips,3 travel spend gained momentum in 2026. Eighty-five percent of travel managers report expanding budgets, up from 74% in 2025, while the share reporting contracting budgets dropped from 10% to just 3% (figure 1). It may be that the caution of 2025 left some pent-up demand for client engagement, business development, and in-person collaboration.
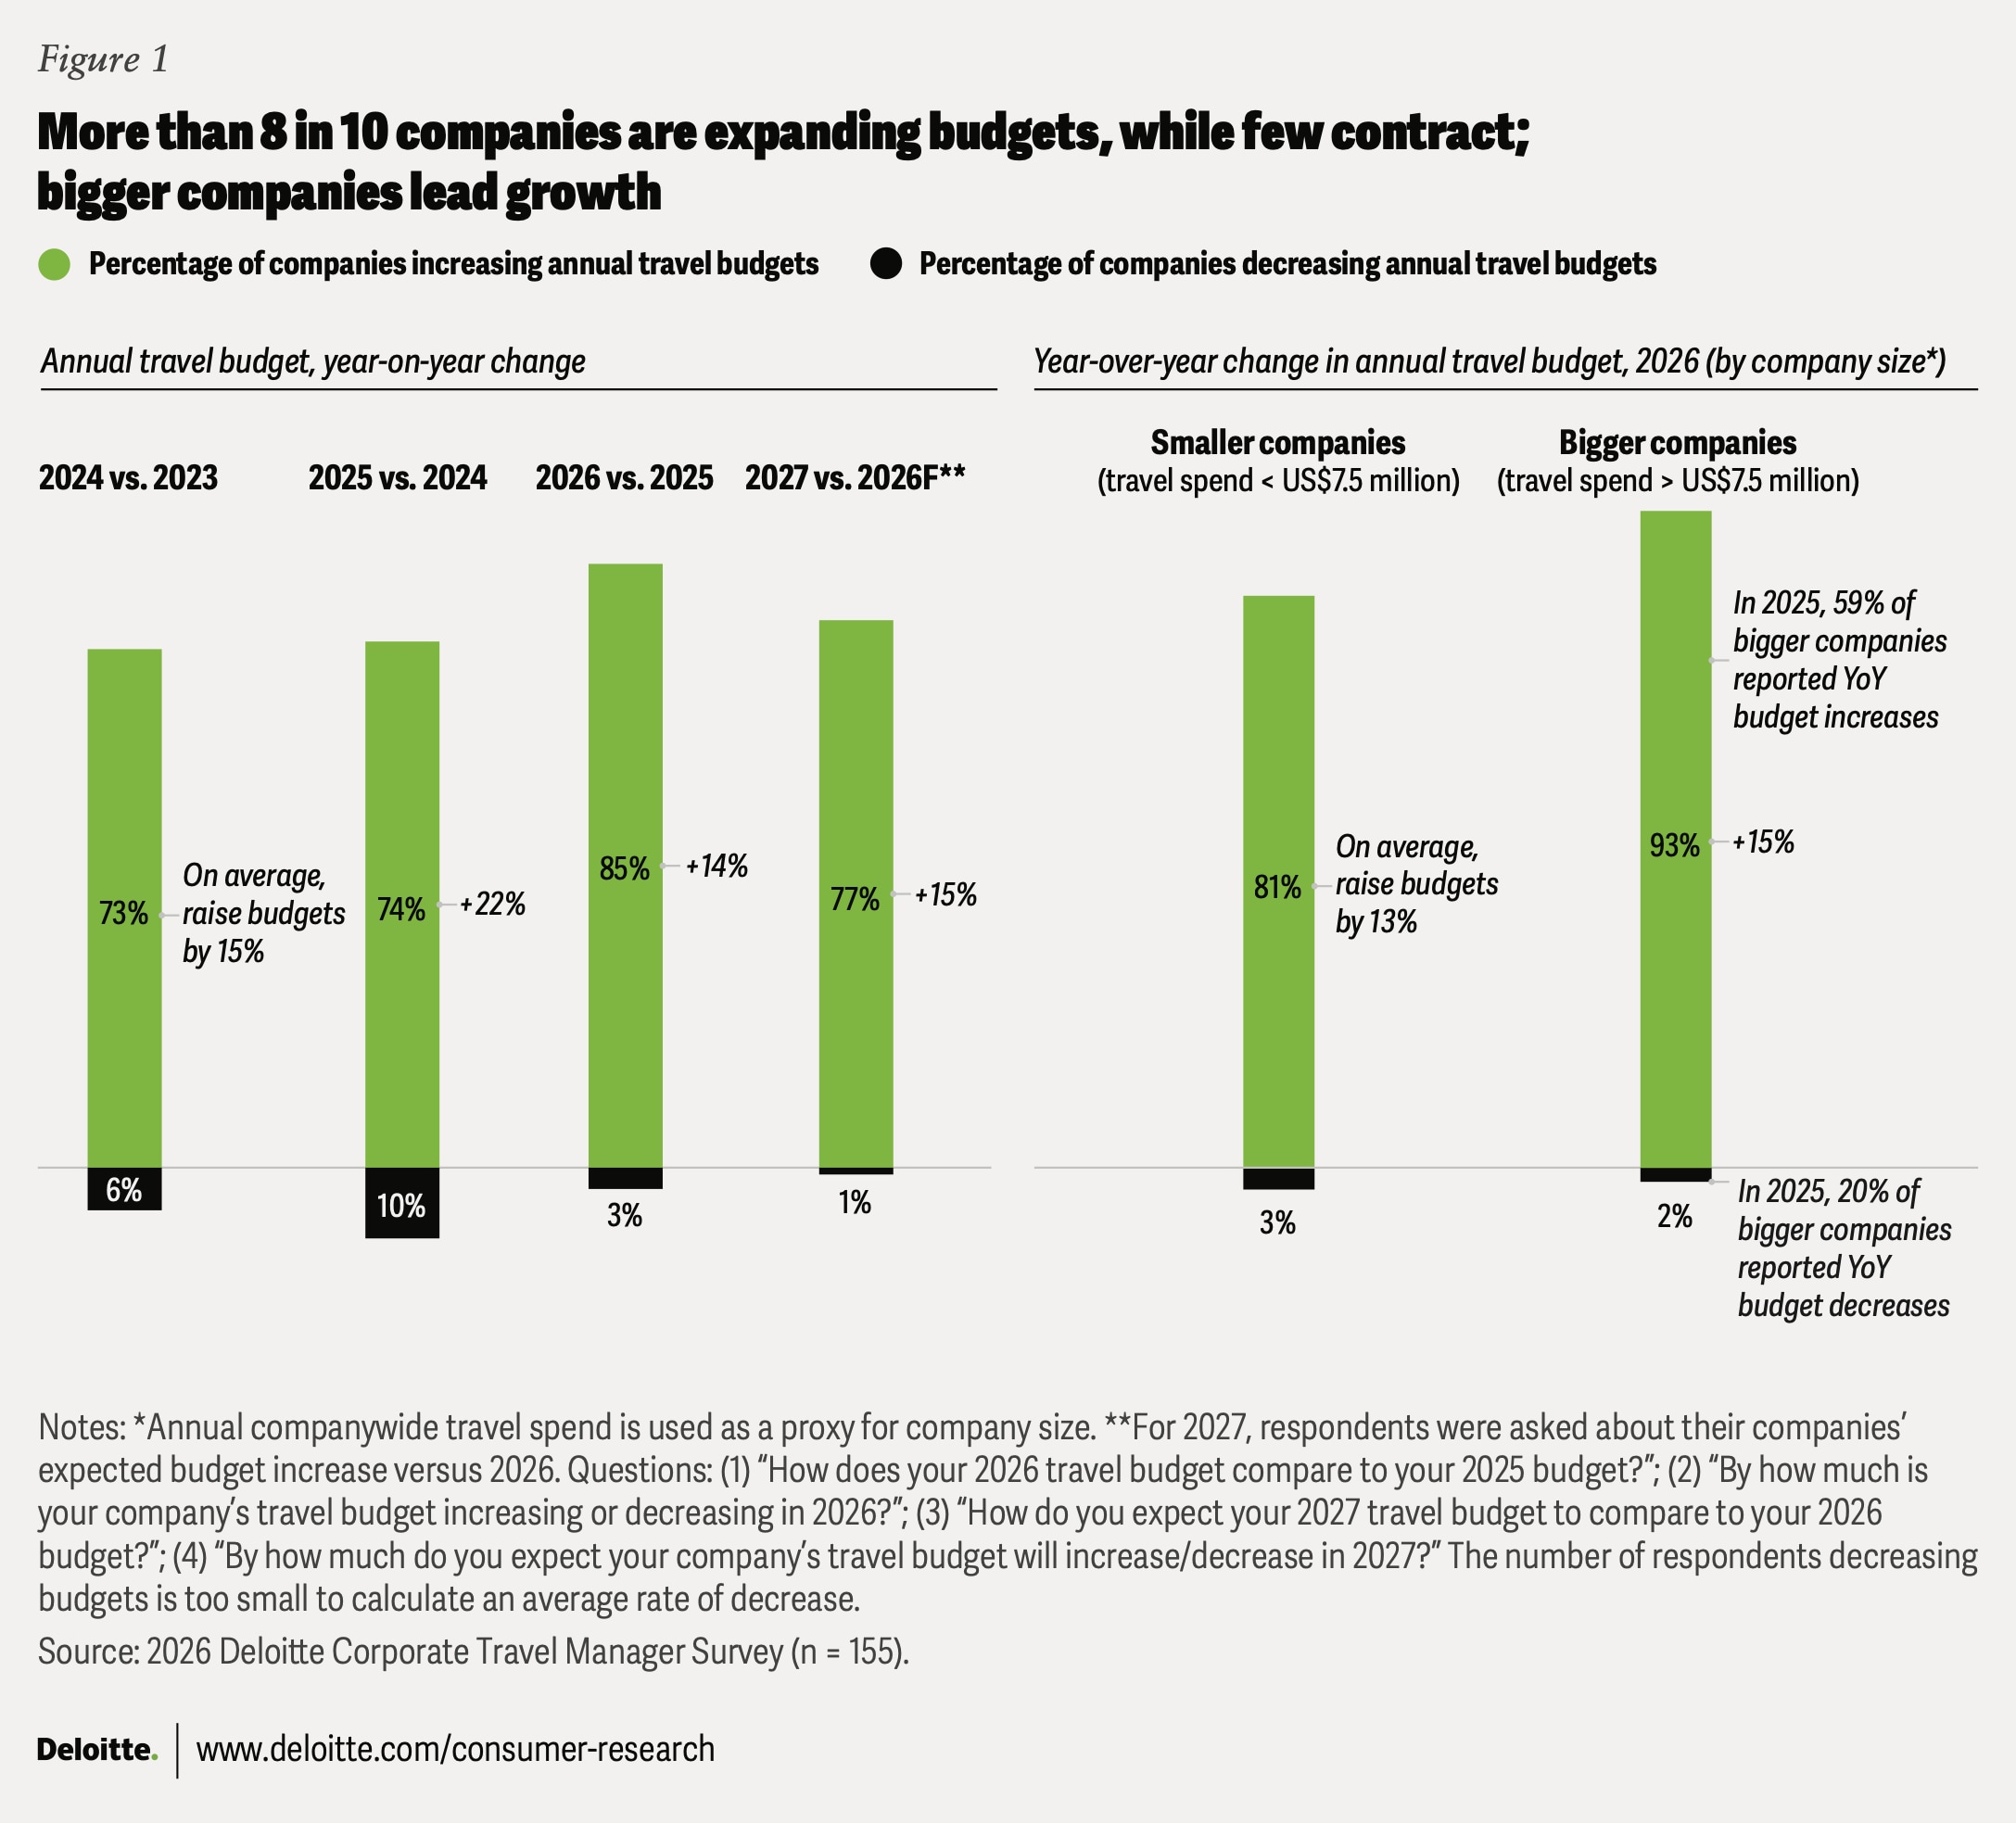
Growth is more common this year, but it’s also more conservative. Compared with 2025, fewer companies are increasing budgets by 25% or more, and the average rate of increase fell from 22% to 14%. Bigger companies in the survey report more frequent and larger increases.
Higher prices are a tailwind behind those budget gains: Spend is increasing at roughly twice the rate of trip volume in 2026, and a similar pattern is expected in 2027 (figure 2). Among travel managers surveyed, 43% expect trip volume to increase slightly (1% to 5%), while 34% expect higher growth (6% to 20%). Only 2% expect travel to decline. Bigger companies anticipate faster growth, with more than half projecting trip volume increases of 6% or more.
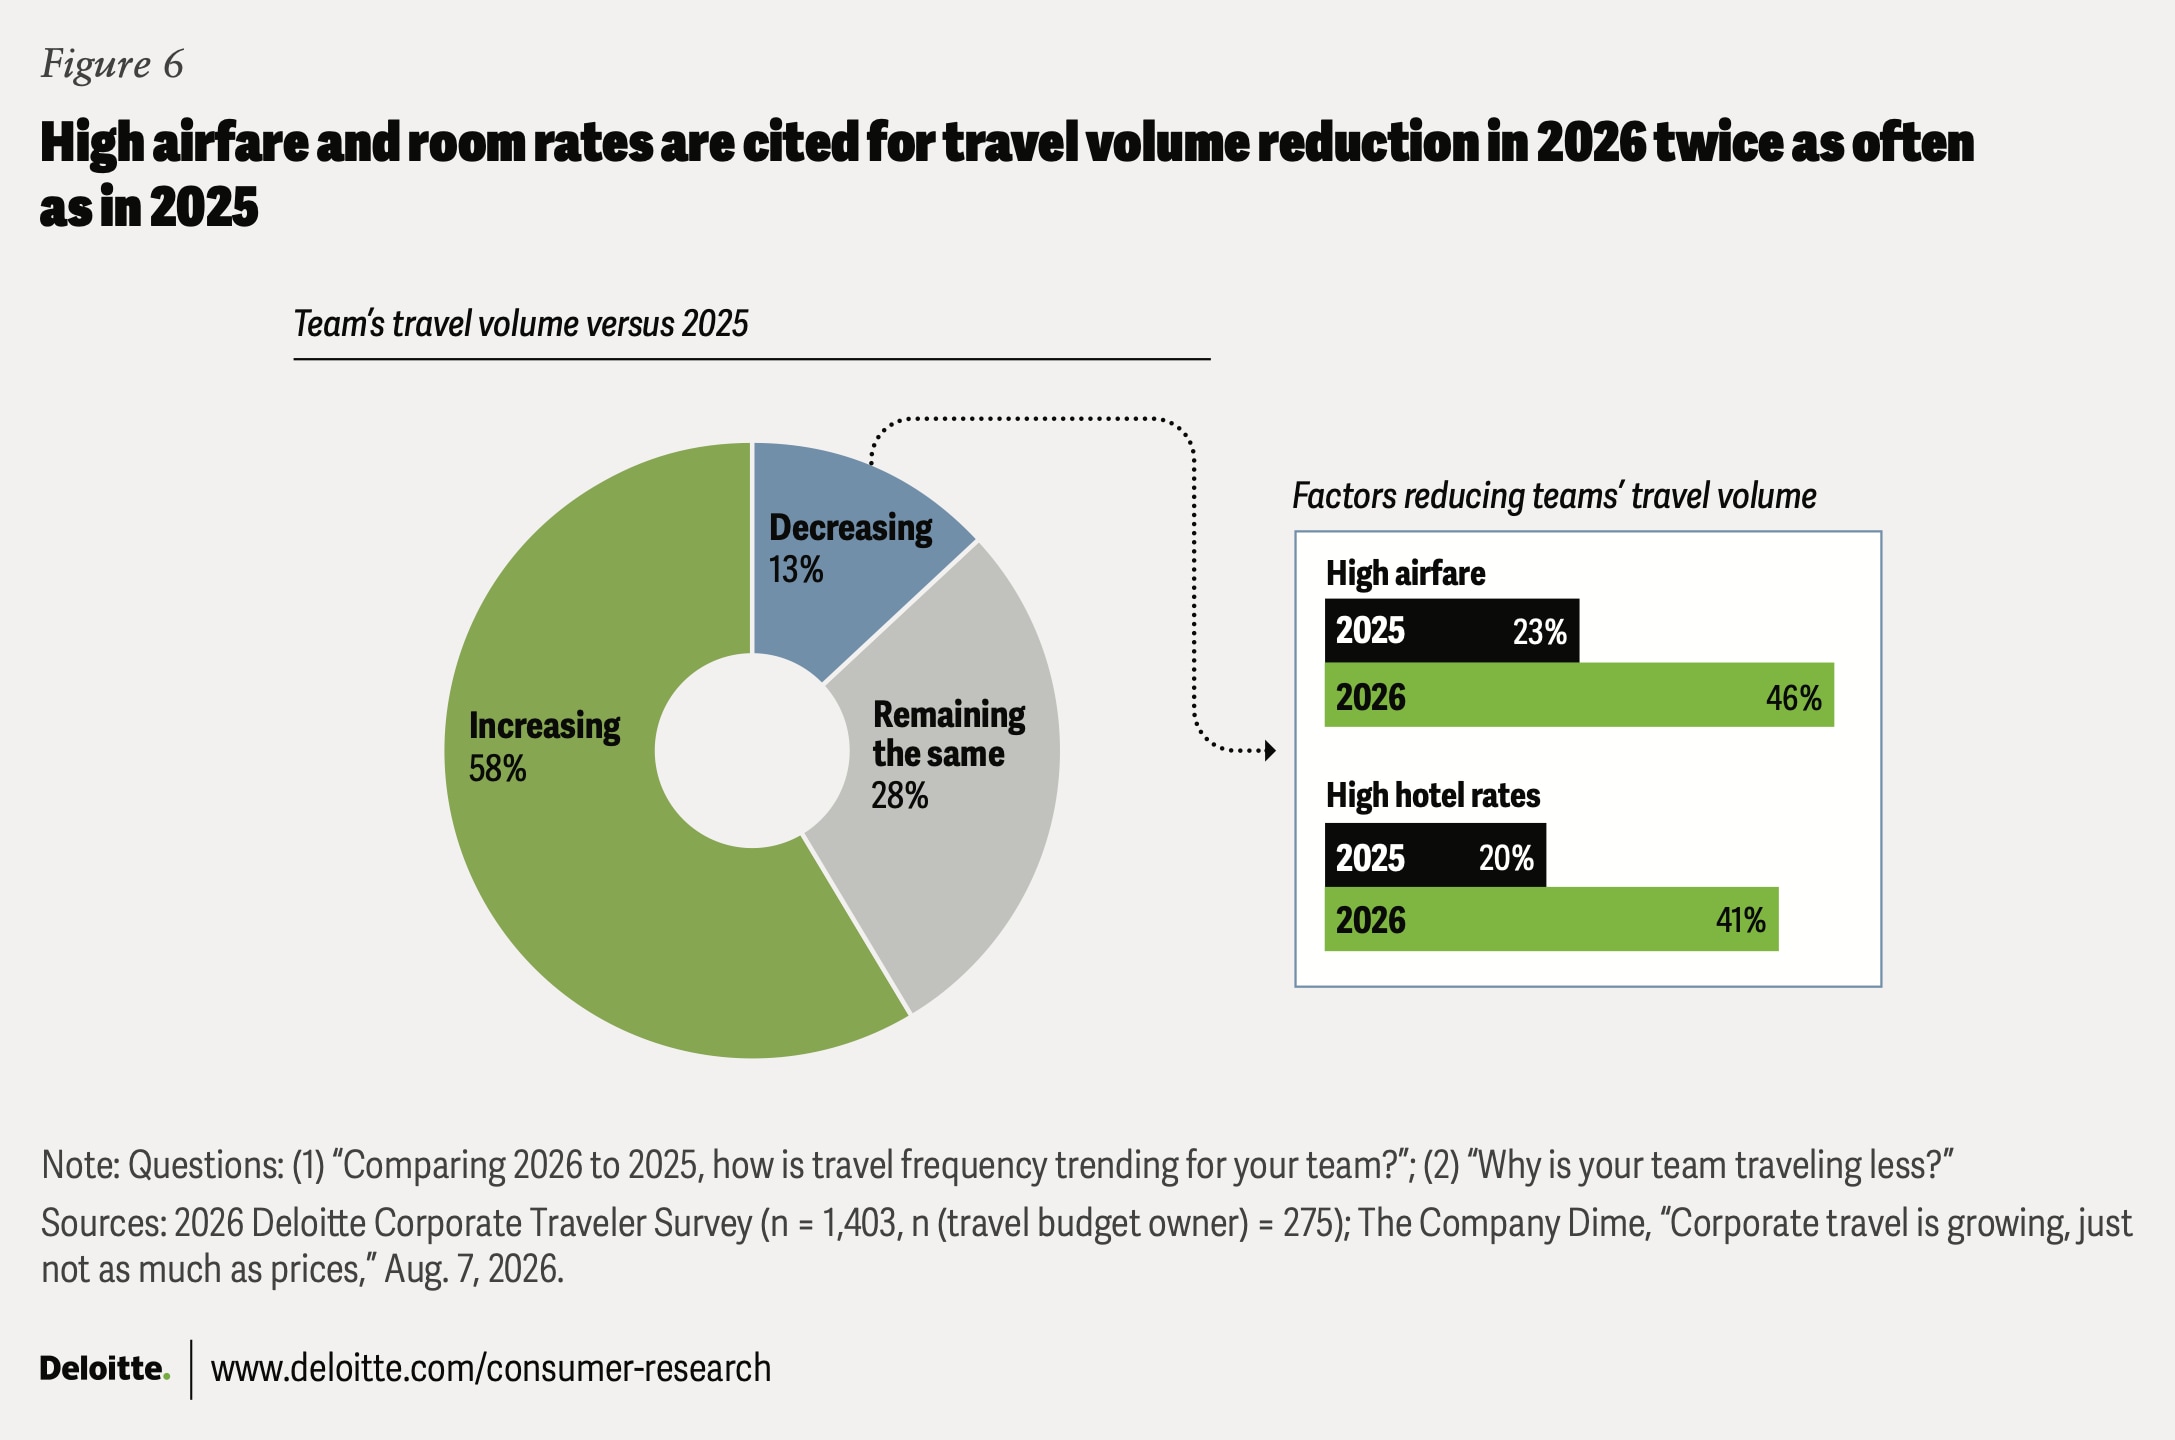
Team-level survey data shows a similar pattern of cost-constrained growth: The share of team leaders reporting increased trip frequency ticked up from 54% in 2025 to 58% in 2026 (figure 5), but after accounting for the size of those increases, overall gains look similar to last year. Among those reporting decreases in travel volume, about twice as many now cite high airfare or hotel rates as the cause compared with 2025. But fewer cite budget constraints, suggesting more companies are struggling to keep pace with prices despite setting aside a similar or larger budget.
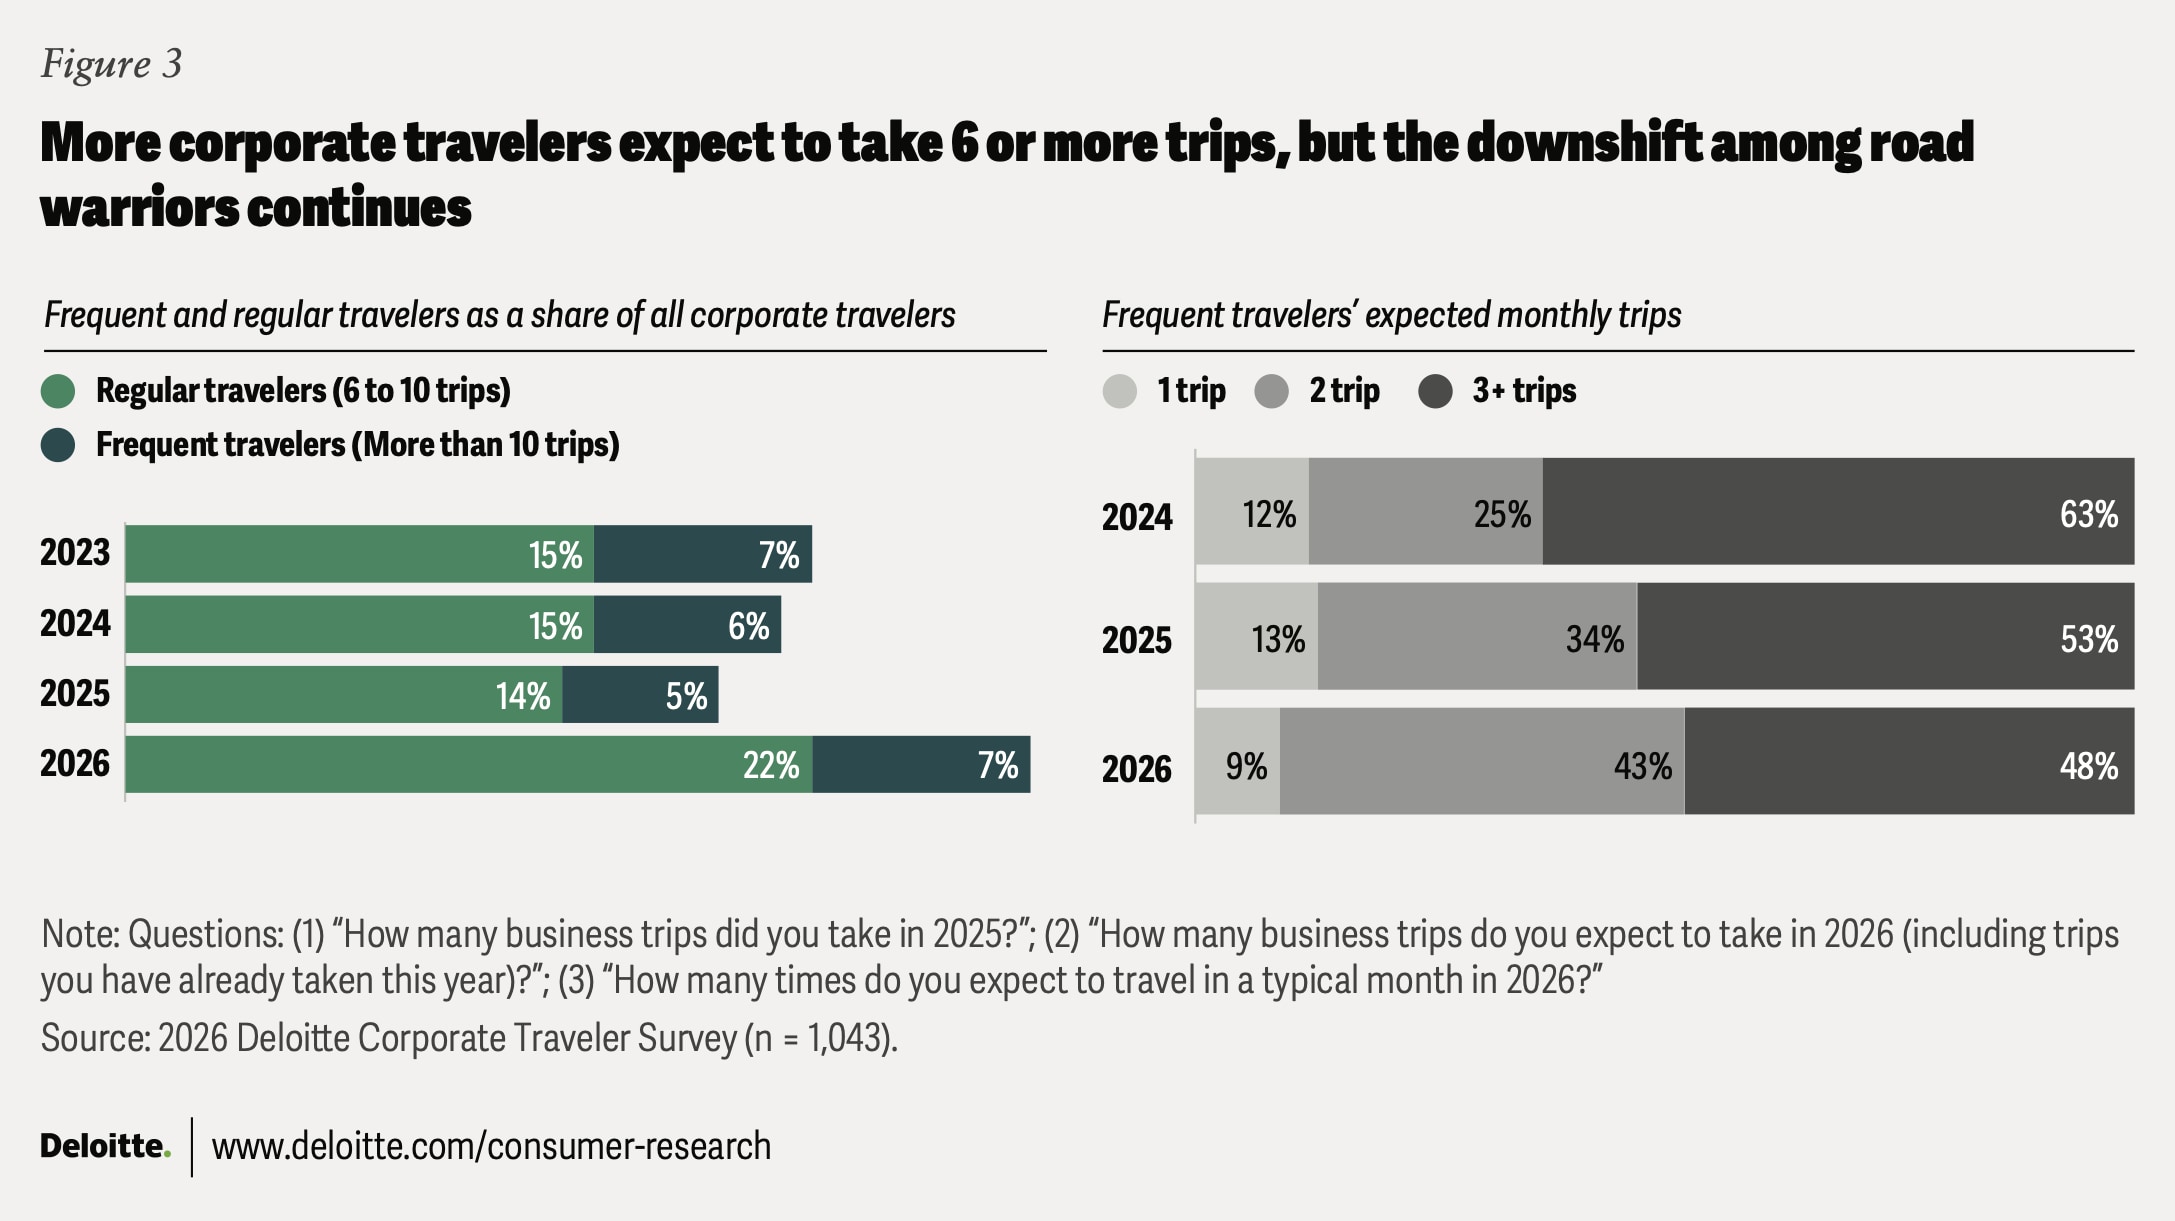
This shift toward more travel, spread more thinly, also shows up in Deloitte’s survey of individual corporate travelers (figure 3). The ranks of regular travelers (those taking 6 to 10 trips a year) jumped from 14% to 22%, while frequent travelers, who take more than 10, inched up 2 percentage points. And among those frequent travelers, a shrinking share expect to travel three or more times in a typical month. For the second year in a row, many of the busiest travelers appear to be dialing down their cadence.
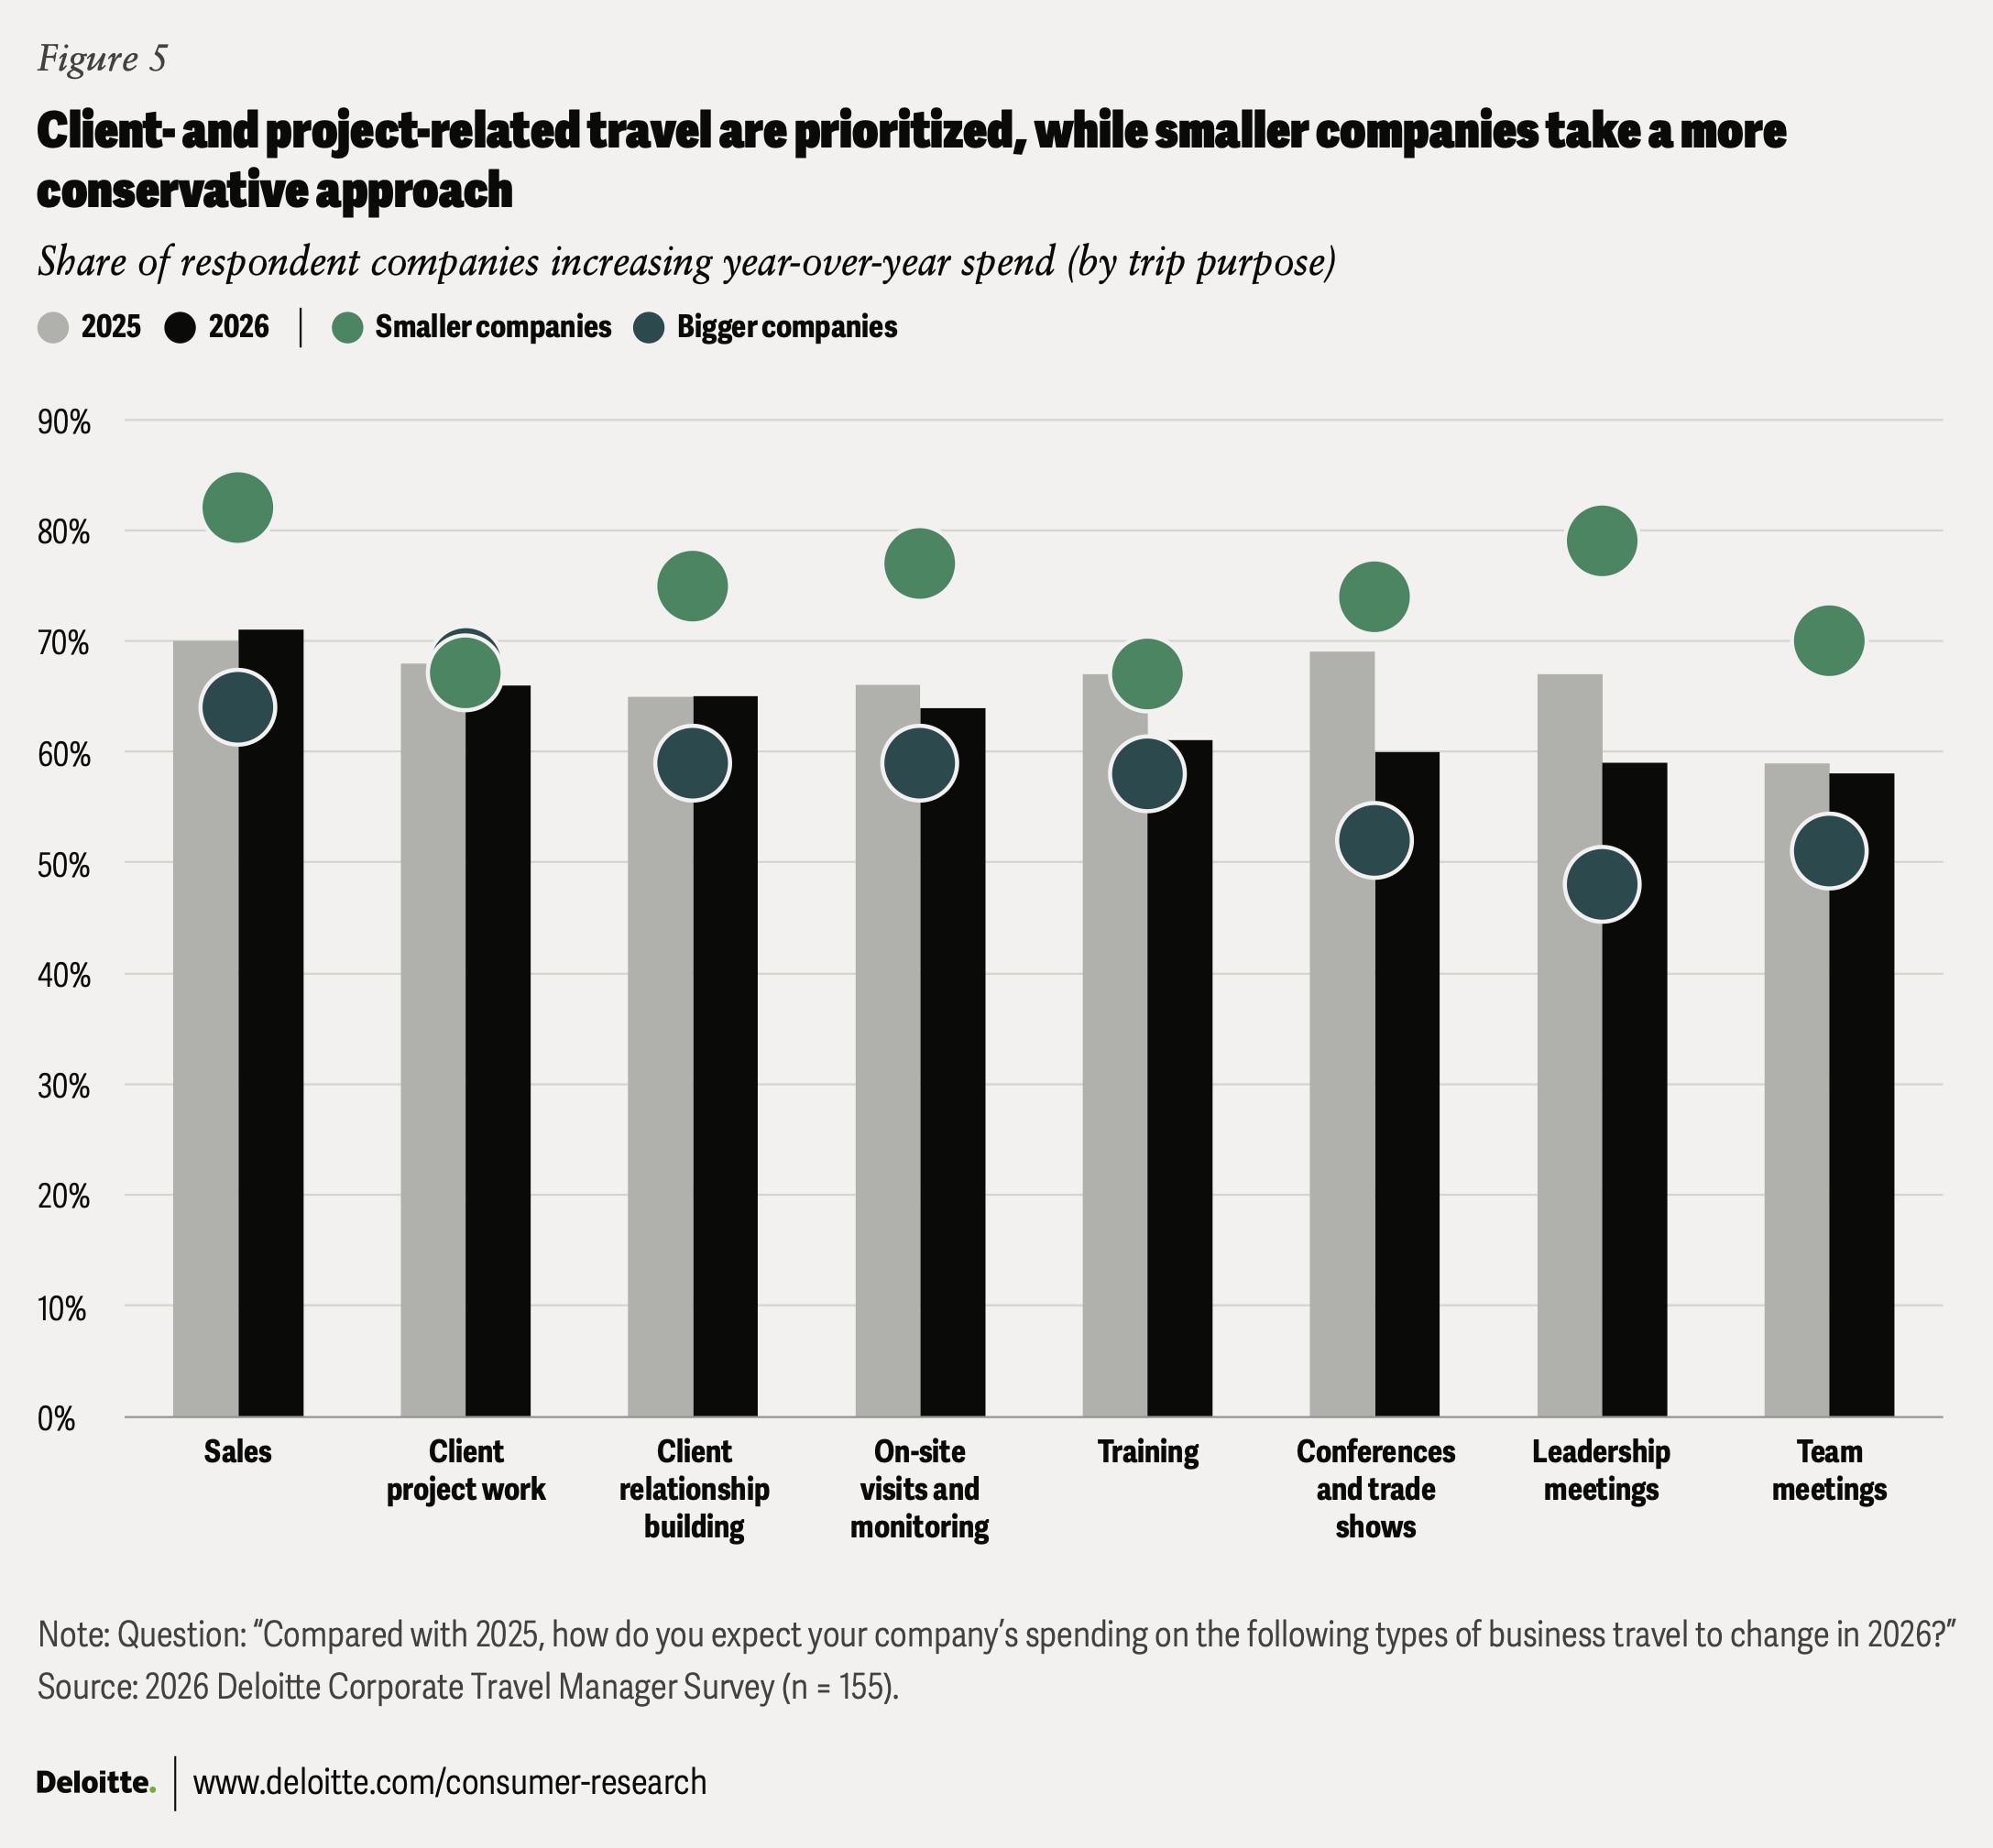
A more selective approach to travel also appears to influence how trip types are trending. With most of the incremental budget being absorbed by higher costs rather than funding volume expansion, no travel purpose shows a meaningful year-over-year increase in the share of companies growing that category of spend. Instead, surveyed companies are concentrating limited incremental spend on travel most directly tied to revenue and delivery: sales, client project work, client relationship building, and on-site visits (figure 4). Spending on conferences, training, leadership meetings, and team meetings is growing less.
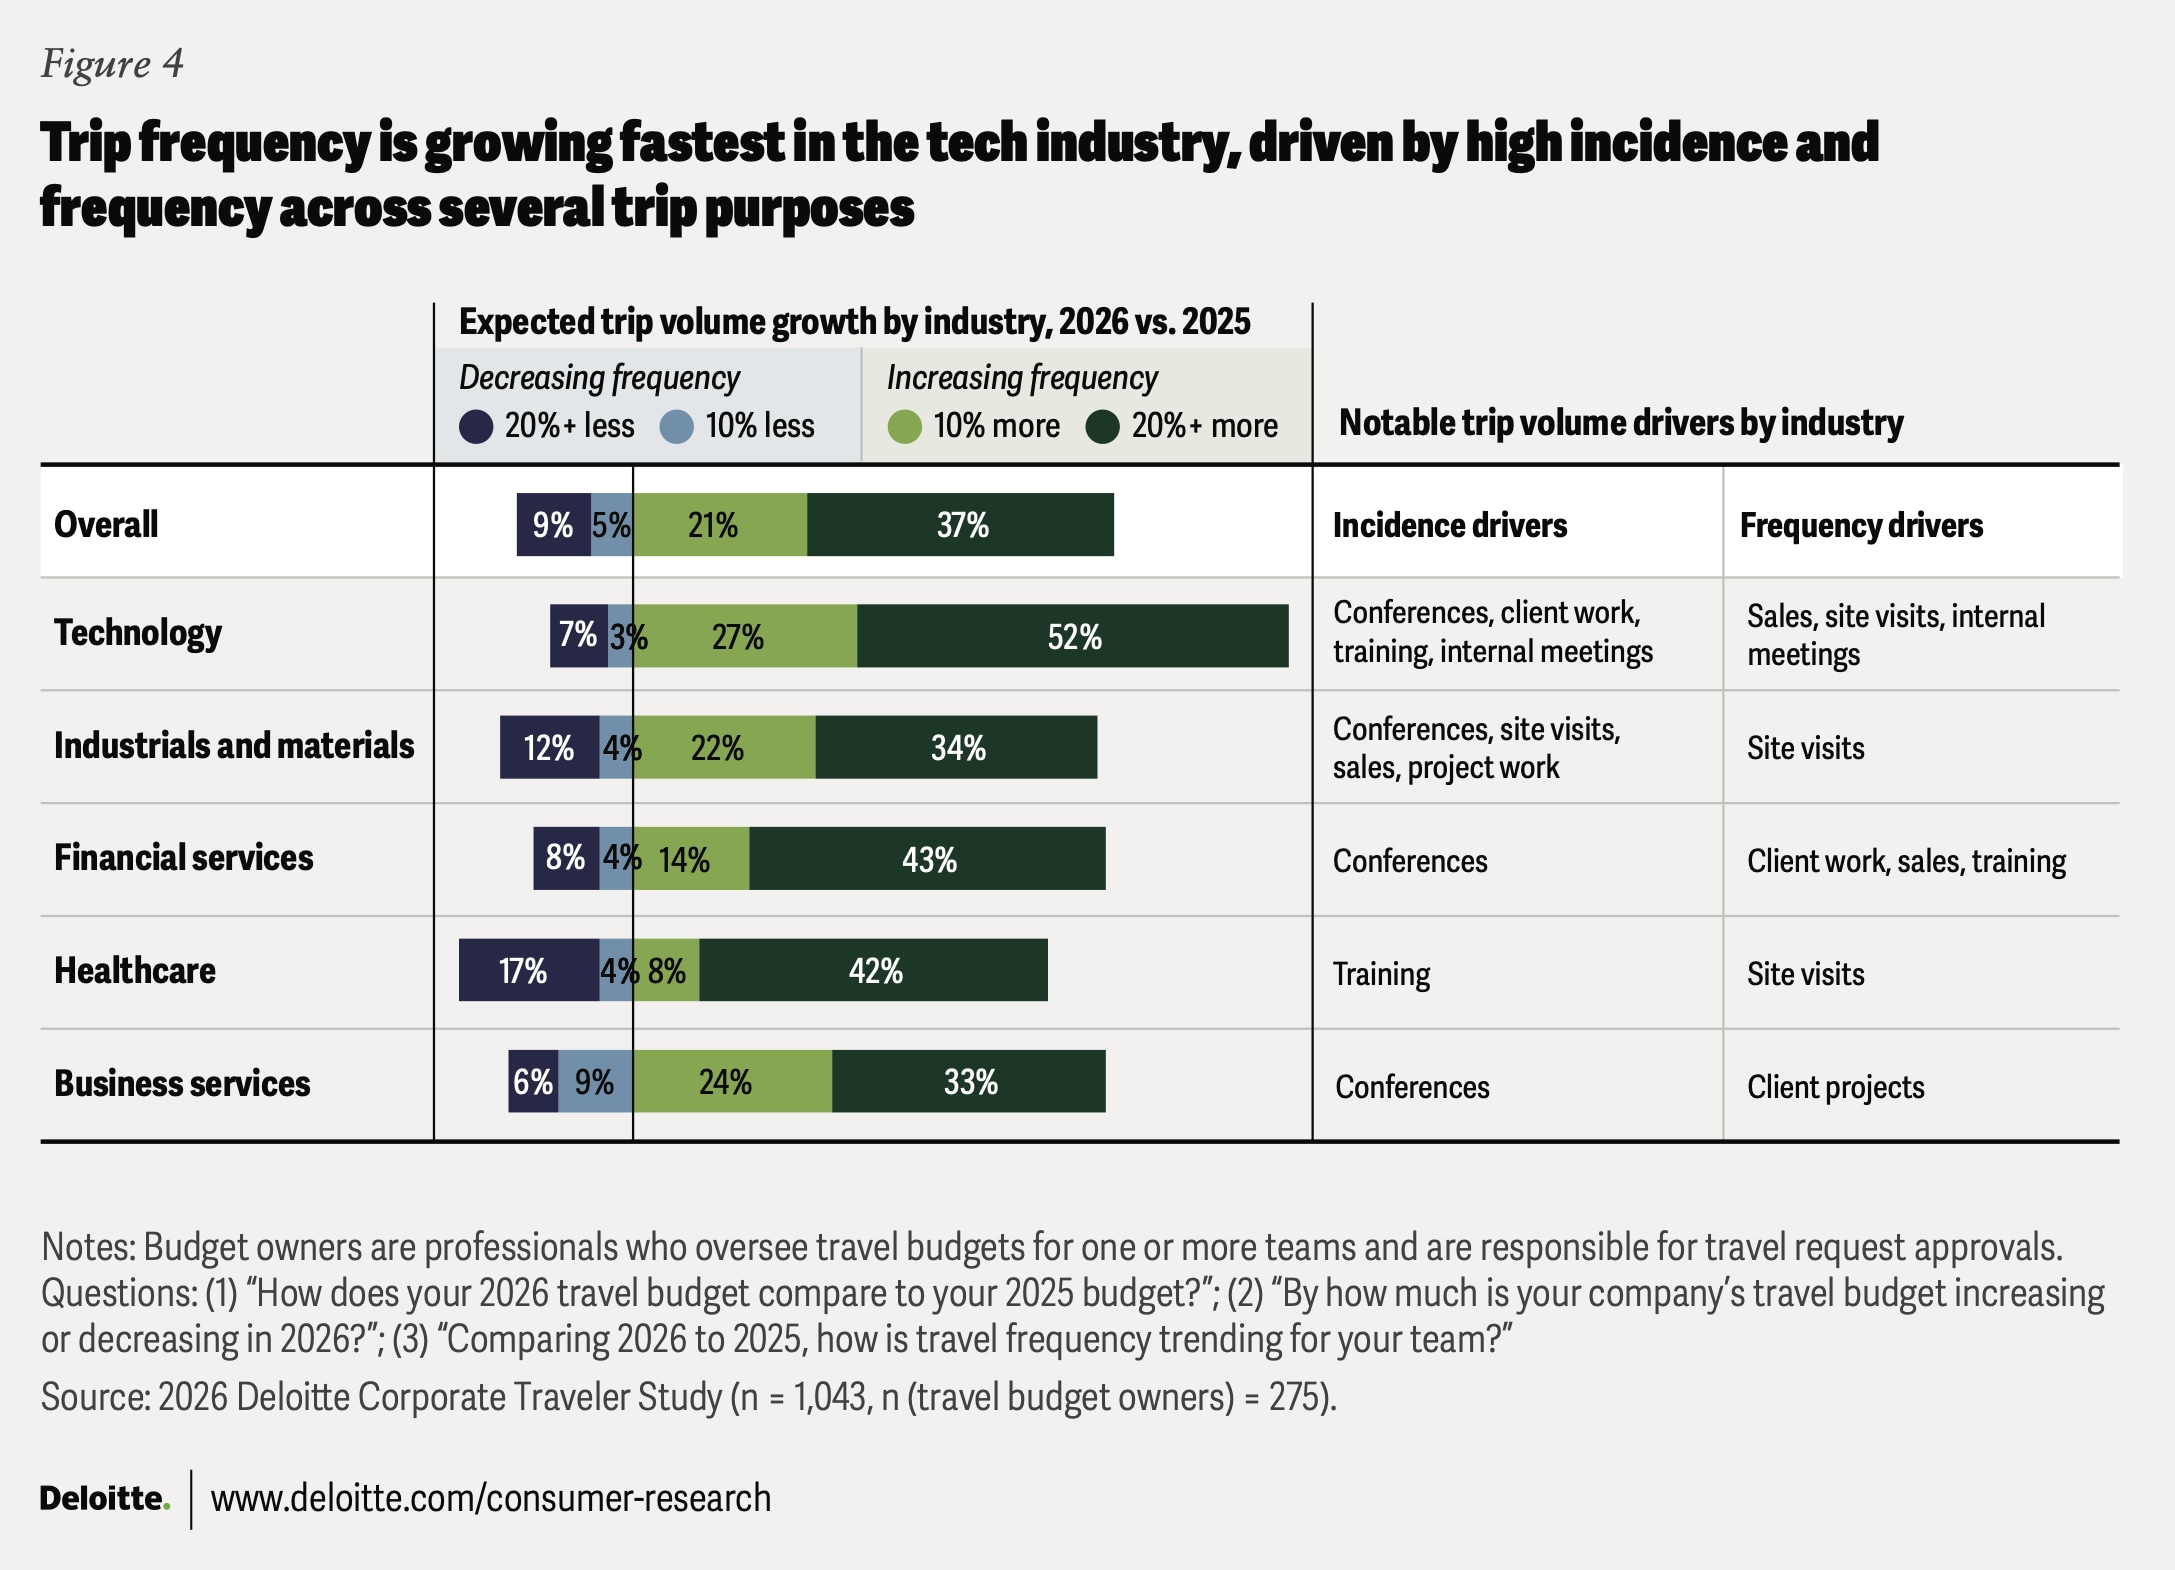
Growth and key travel drivers also vary noticeably by industry (figure 5). Technology reports the strongest expected gains in frequency, with over half of tech budget owners expecting increases of 20% or more. The tech industry continues to navigate competition and volatility, contending with rapid AI adoption and pressure to show results. For tech companies, efforts to cement partnerships and close deals may be putting a premium on face time with clients, partners, and colleagues. Other industries represented by survey respondents show more measured, although still largely positive, outlooks. Just as important, the reasons companies travel differ meaningfully by industry: Sectors where conferences and training drive a greater share of travel may have more room to pull back when costs bite, while those whose travel is concentrated in client work and site visits likely have less discretionary travel to trim without touching revenue-generating activity directly.
Where the cost pressure squeezes
The cost of travel is simultaneously driving the expansion of many corporate travel budgets while also putting some trips on the chopping block. In 2025, travel managers taking Deloitte’s survey highlighted employee comfort expectations as the No. 1 factor increasing travel costs. In 2026, rising travel prices took the top spot. Among the team leaders tasked with allocating travel budgets, twice as many point to high airfare and room rates as reasons their teams do not travel as much in 2026 (figure 6).
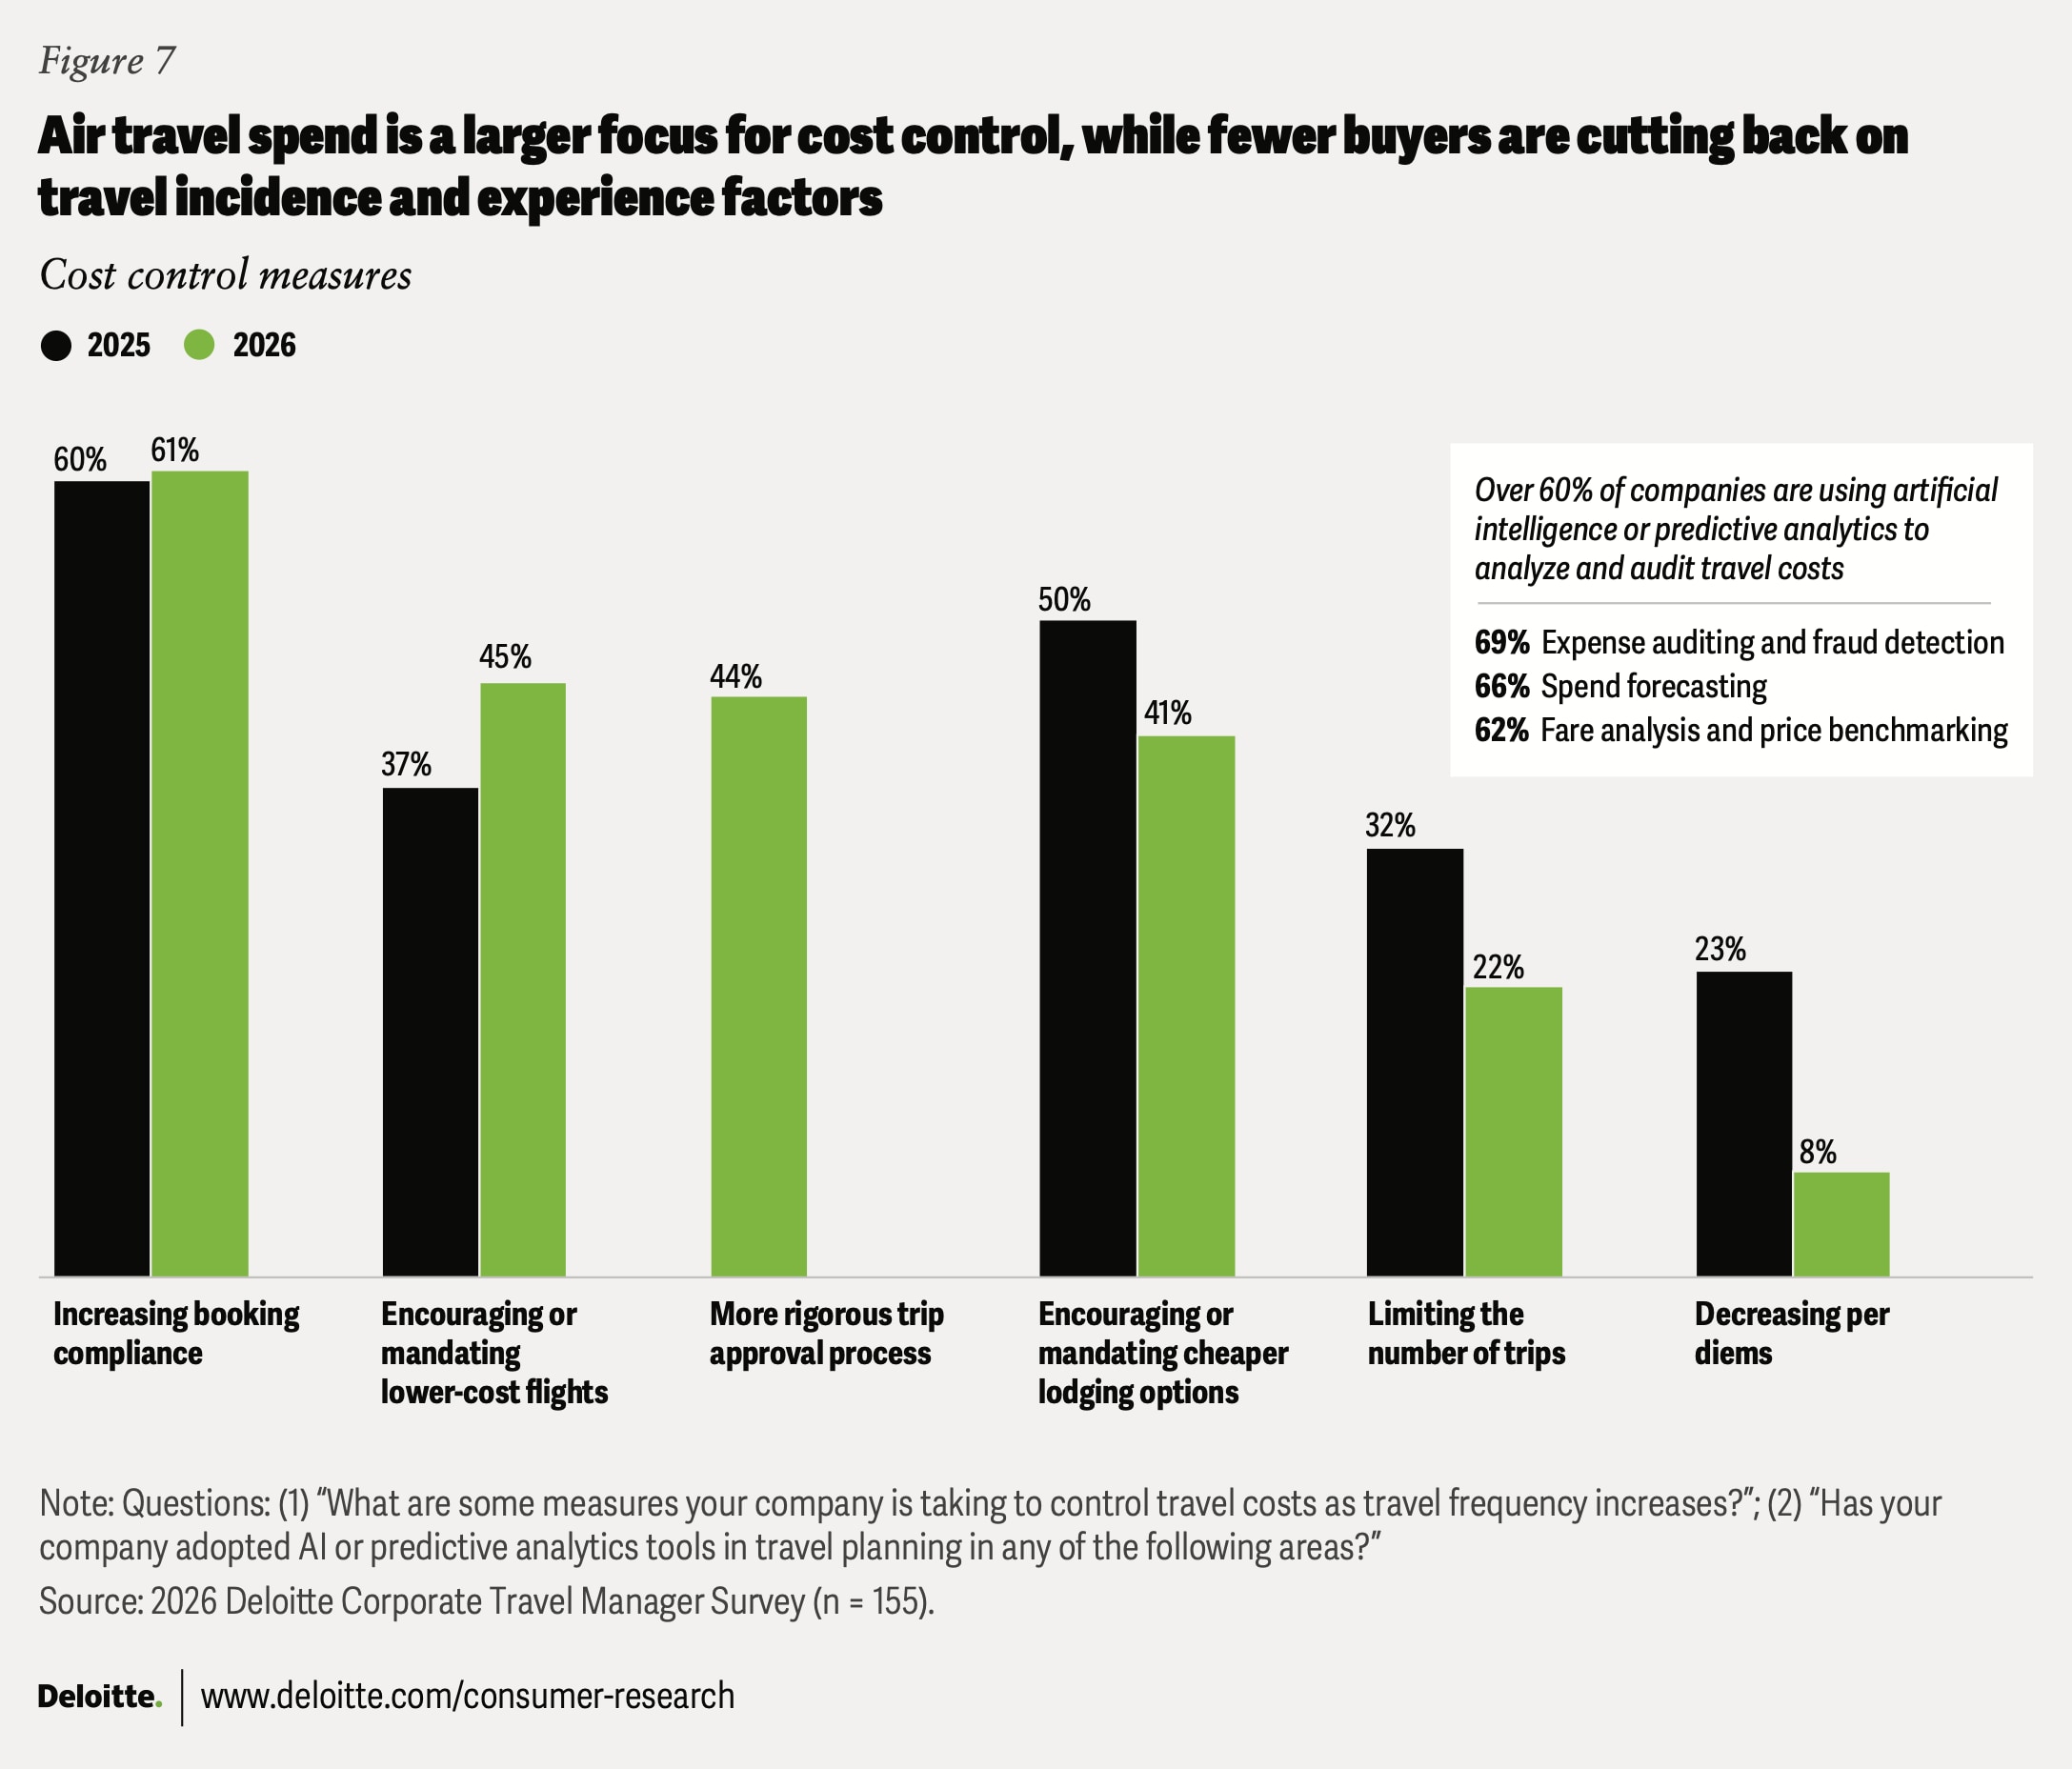
To broadly manage costs, booking compliance remains travel managers’ most popular lever by far, with 60% saying it is a cost-control priority (figure 7). Nearly half (44%) say their company has made the pre-trip approval process more rigorous.
Protecting the traveler experience, with a little help from suppliers
If there’s one lever companies appear reluctant to pull, it’s comfort. Despite the cost pressure running through this year’s survey, employee comfort expectations remain the No. 2 driver of travel spend growth, second only to rising prices and still ahead of factors like flexibility or duty-of-care concerns. Only 8% of travel managers say they’re decreasing per diems this year, down sharply from 23% in 2025.
Drilling down to specific trip components, flights mark a departure from the pattern of prioritizing employee comfort. With domestic corporate airfares up by double-digit percentages, the share of companies mandating lower-cost flights rose from 37% to 45%, while the share pushing travelers toward cheaper lodging actually fell, from 50% to 41%.
Overall, the 2026 data suggests companies are leaning toward negotiating and managing costs down, versus eroding the trip experience. Many programs already went through a comfort-cutting phase during the pandemic-era pullback,4 and travel managers may be reluctant to downgrade the traveler experience. The focus instead appears to be on negotiating better rates for the flights and rooms.
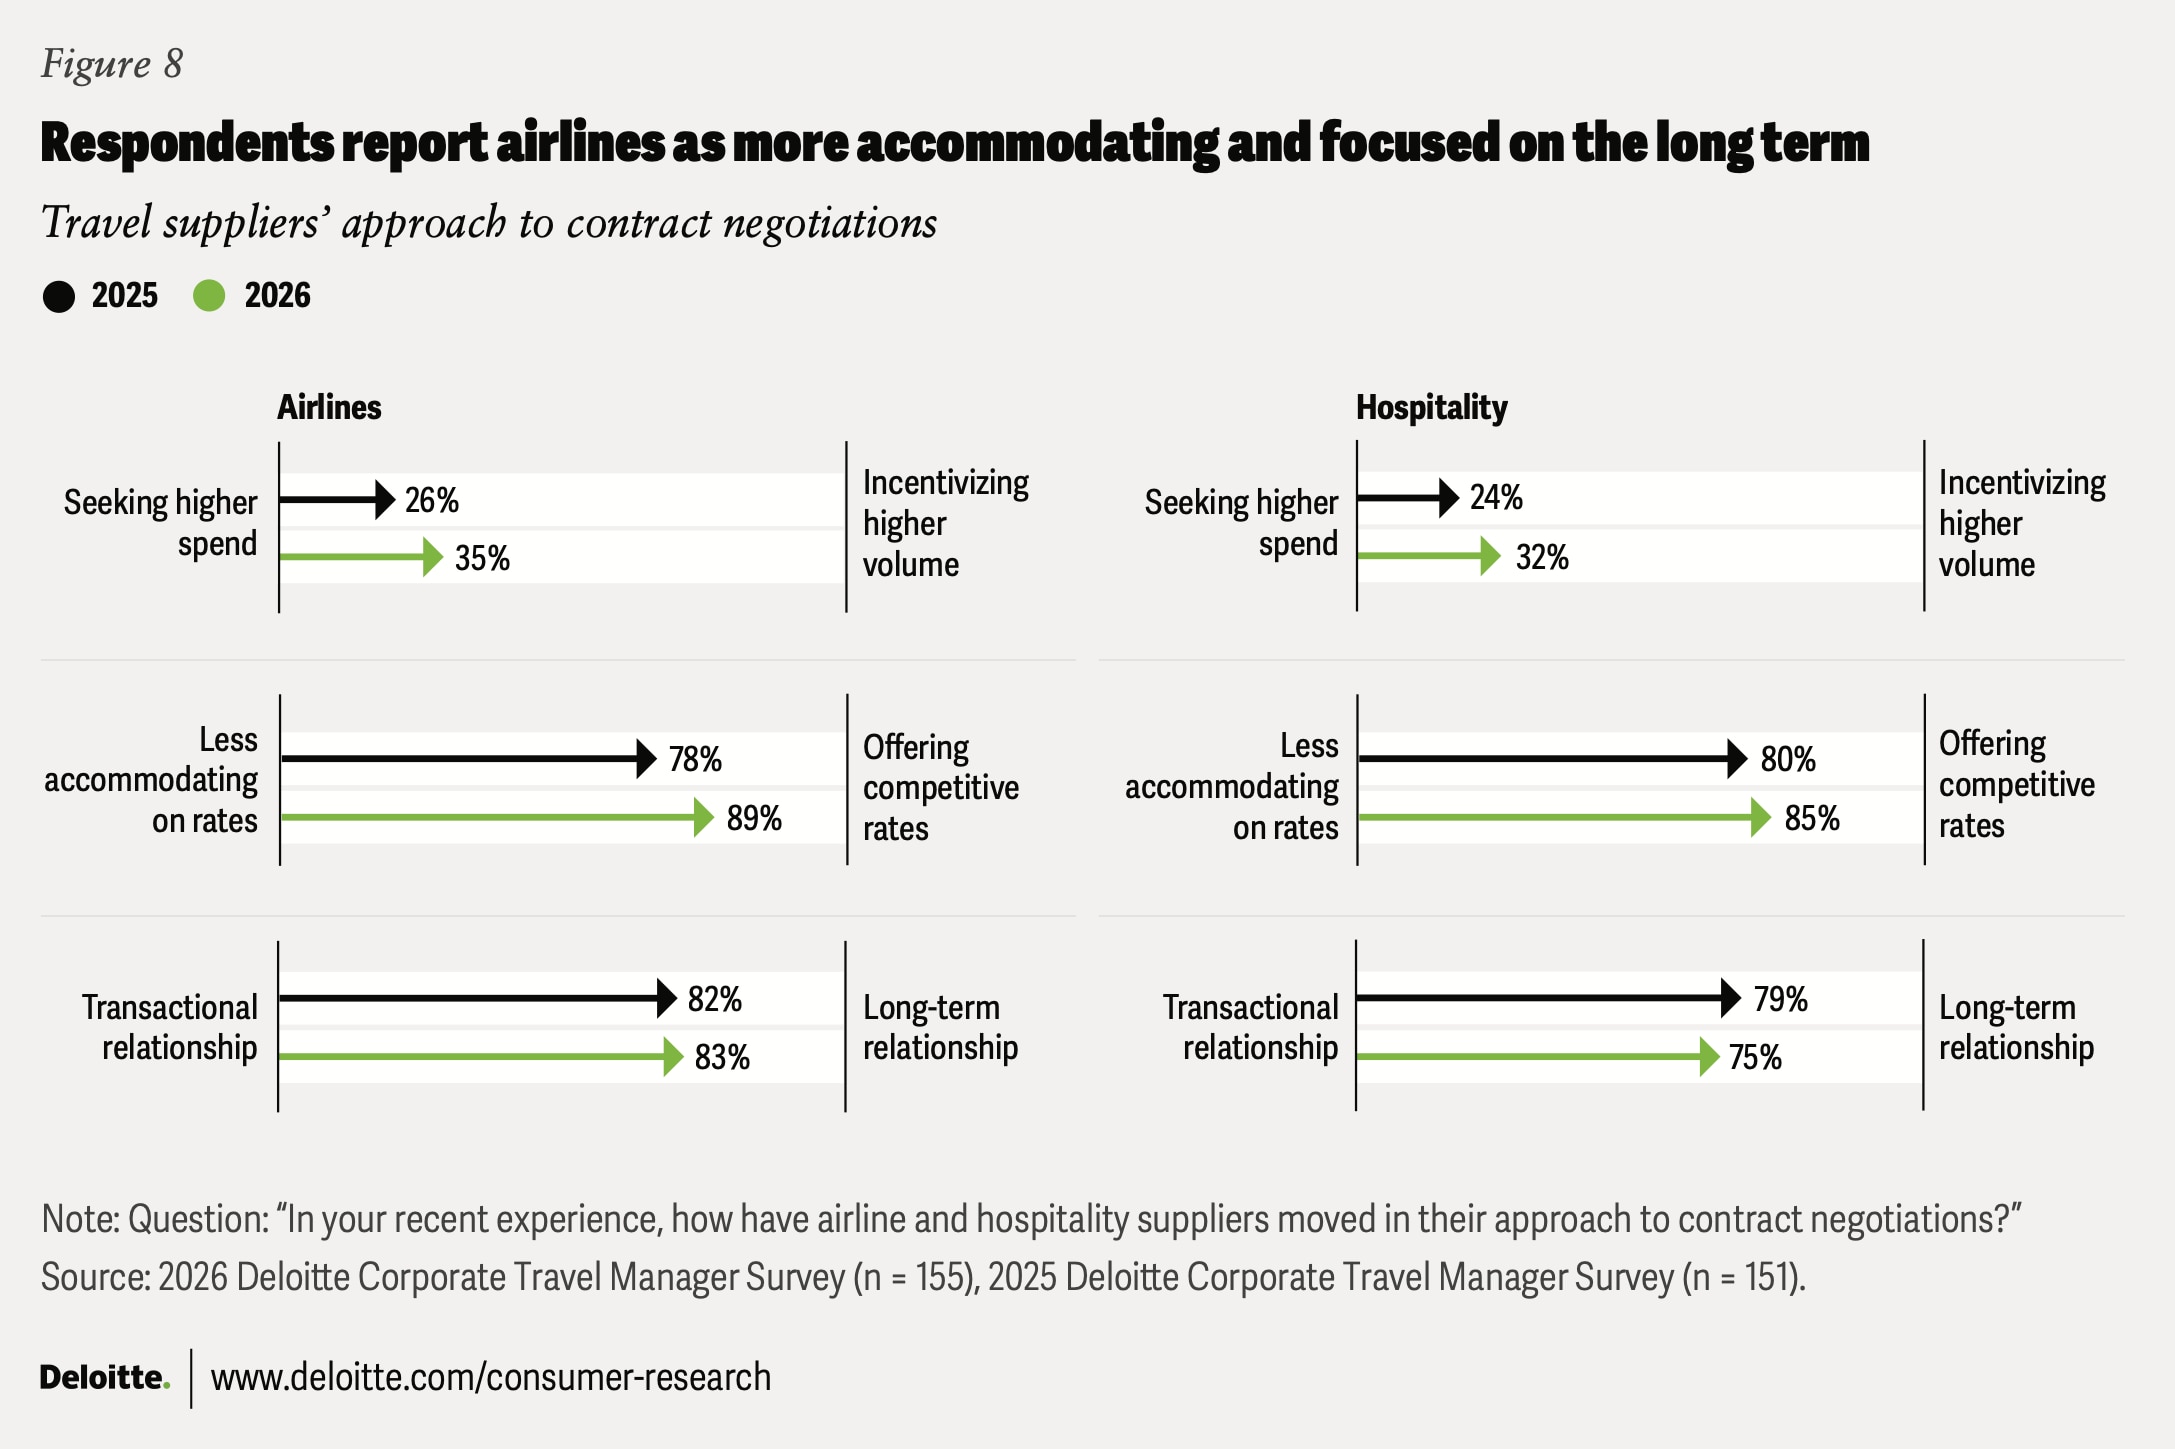
As corporate travel buyers look to secure a consistent experience for employees in the face of higher costs, responses to the travel managers’ survey suggest that suppliers have largely cooperated. Fewer travel managers report seeing either airlines or hotels seeking higher spend over higher volume, and more credit both with competitive rates. Airlines show more accommodation on pricing, suggesting they may be finding ways to offer deals to corporate clients despite rising fares.
But the scorecard diverges when travel managers rate suppliers on their approach to the relationship. More buyers now see airlines playing the long game. Hotels moved the other way: Despite improving on rate and volume, fewer buyers see hotels investing in the relationship for the long term rather than optimizing each deal transactionally (figure 8).
Governance is maturing, with less tightening from the top
In a challenging price environment, some scrutiny practices that had receded in recent years are becoming more prominent again. The shift is toward closer scrutiny at the operational level, not more executive intervention. Fewer companies report evaluating travel strategy at the C-suite or board level, even as more report attaching specific key performance indicators to travel budgets and running pre-trip justifiability assessments (figure 9).
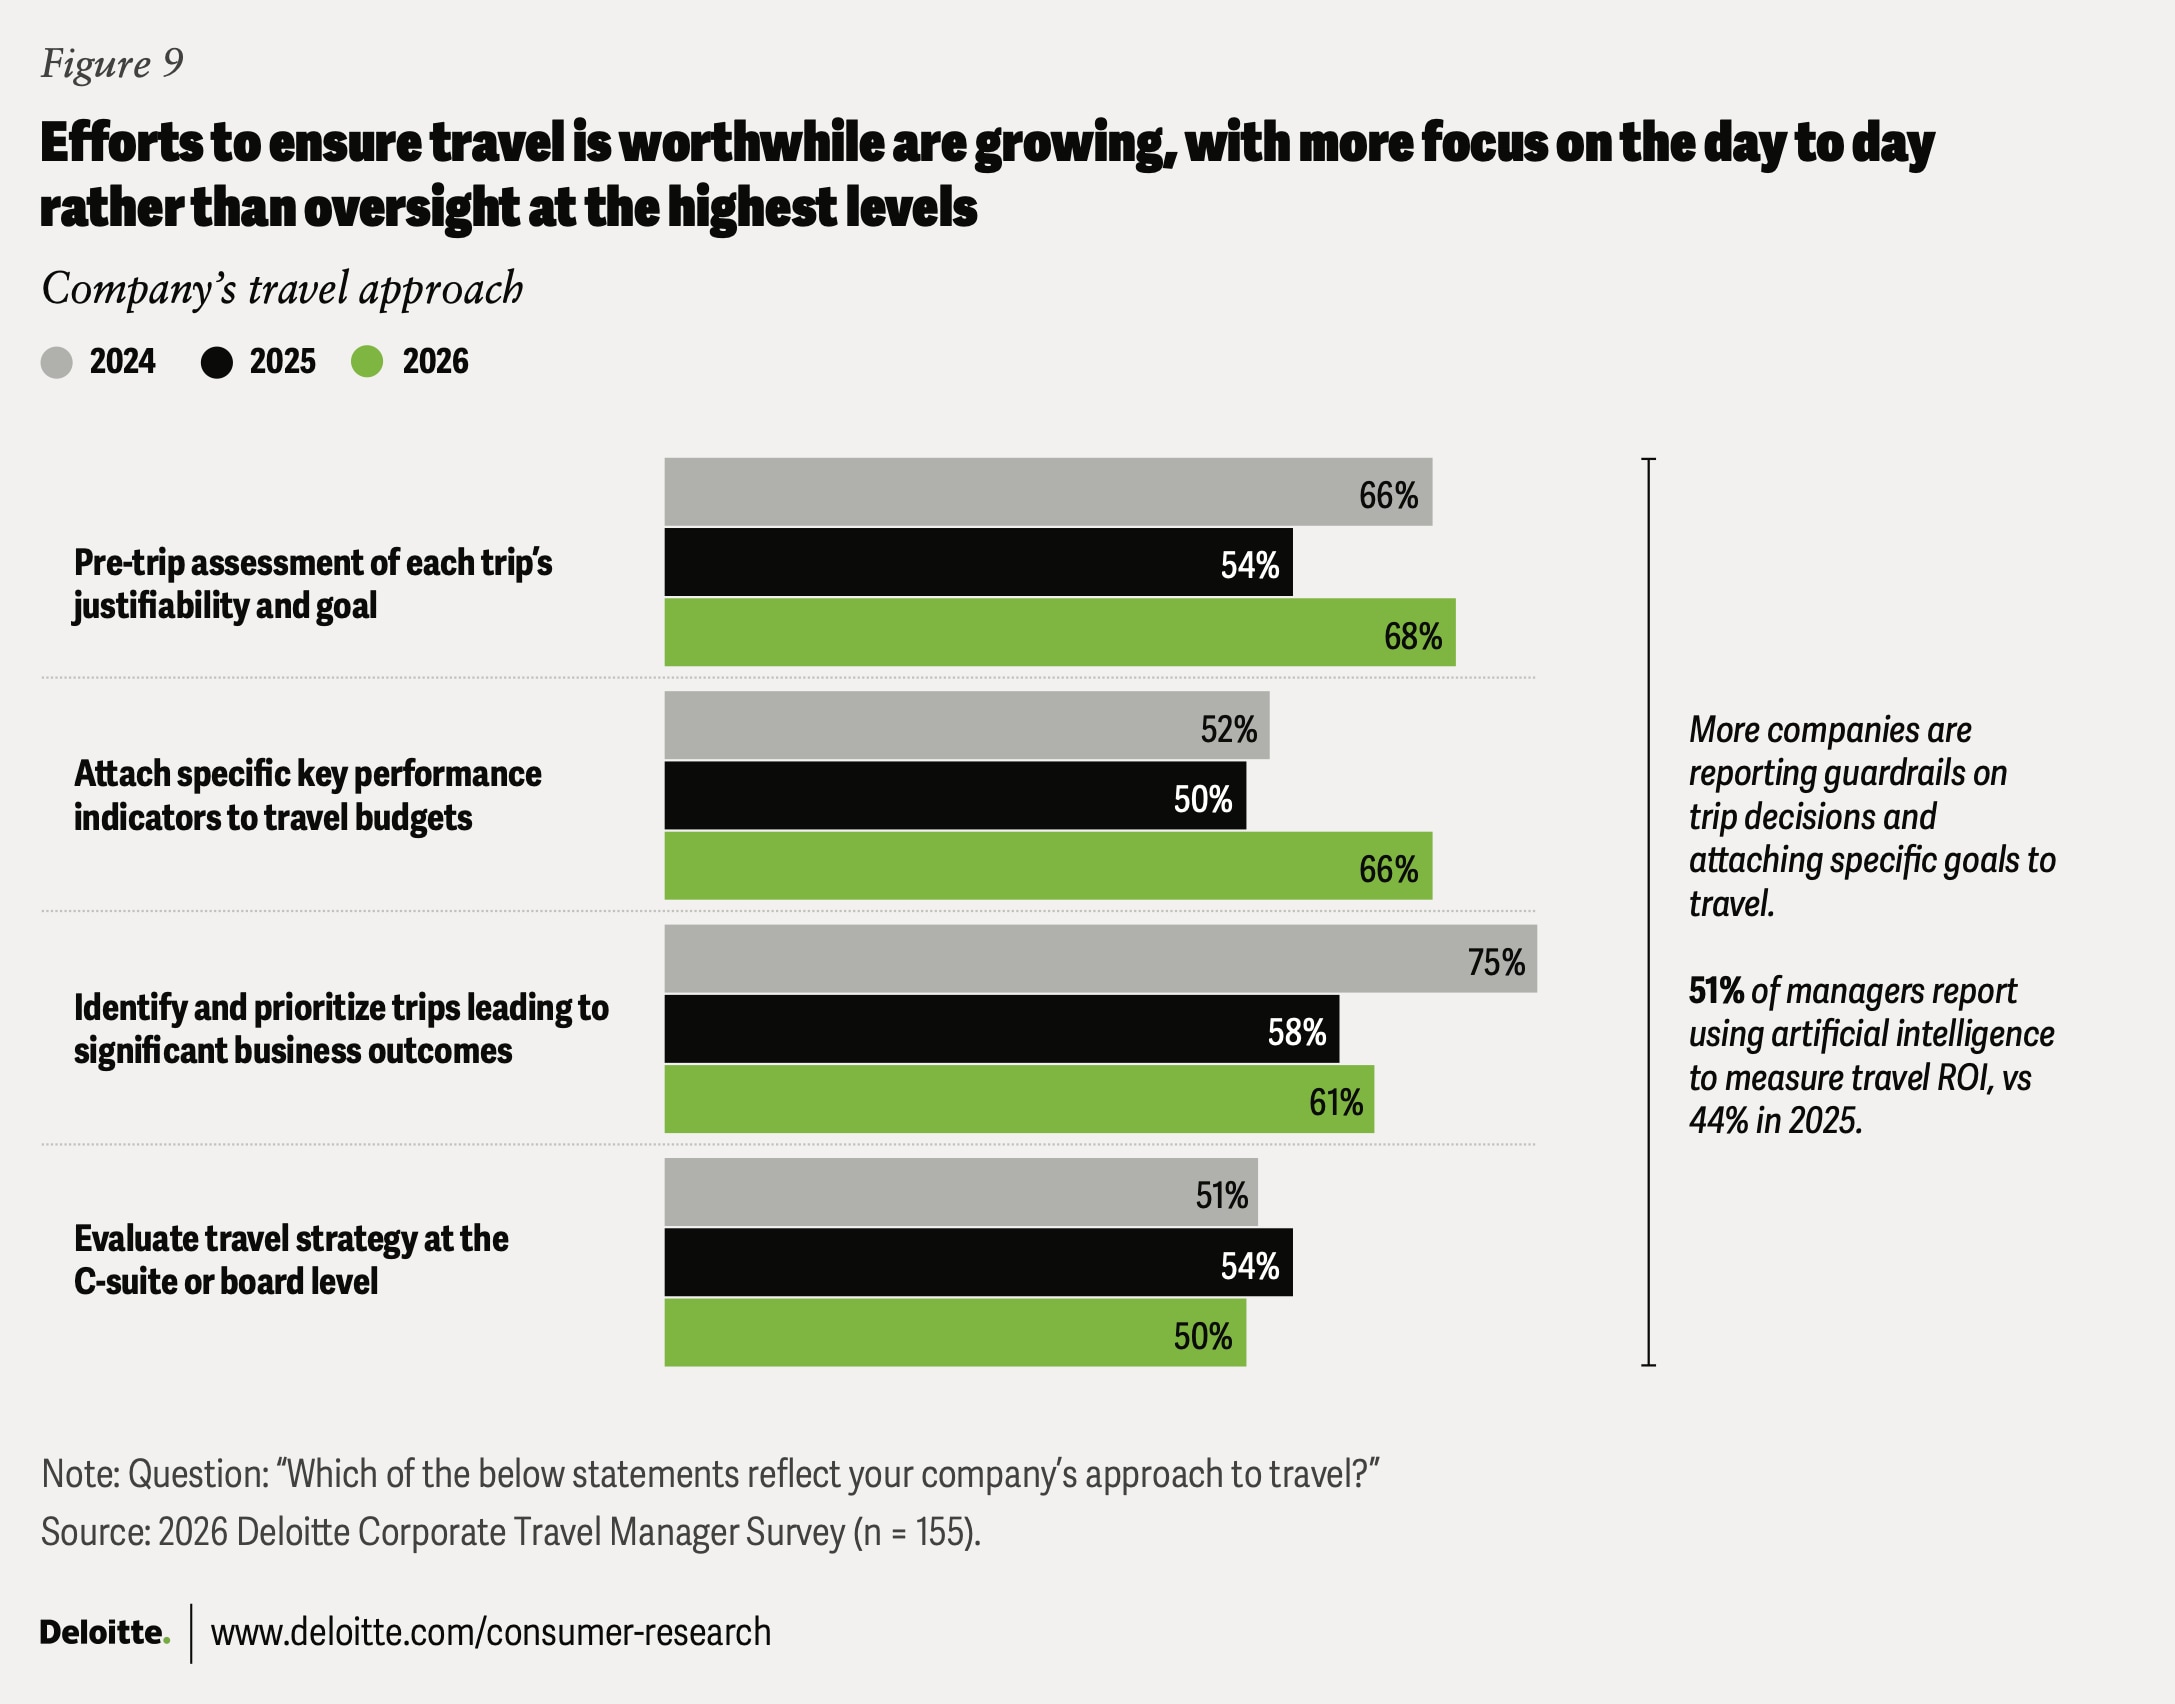
Lower levels of C-suite review could reflect growing confidence that travel managers and business leaders can execute within governance that’s already in place. More mature travel management programs likely have clear policies, reporting, and accountability, which can free leadership to focus on exceptions rather than routine oversight. Increasingly, travel managers, procurement, and business leaders are trusted to optimize within defined guardrails.
Technology as the release valve
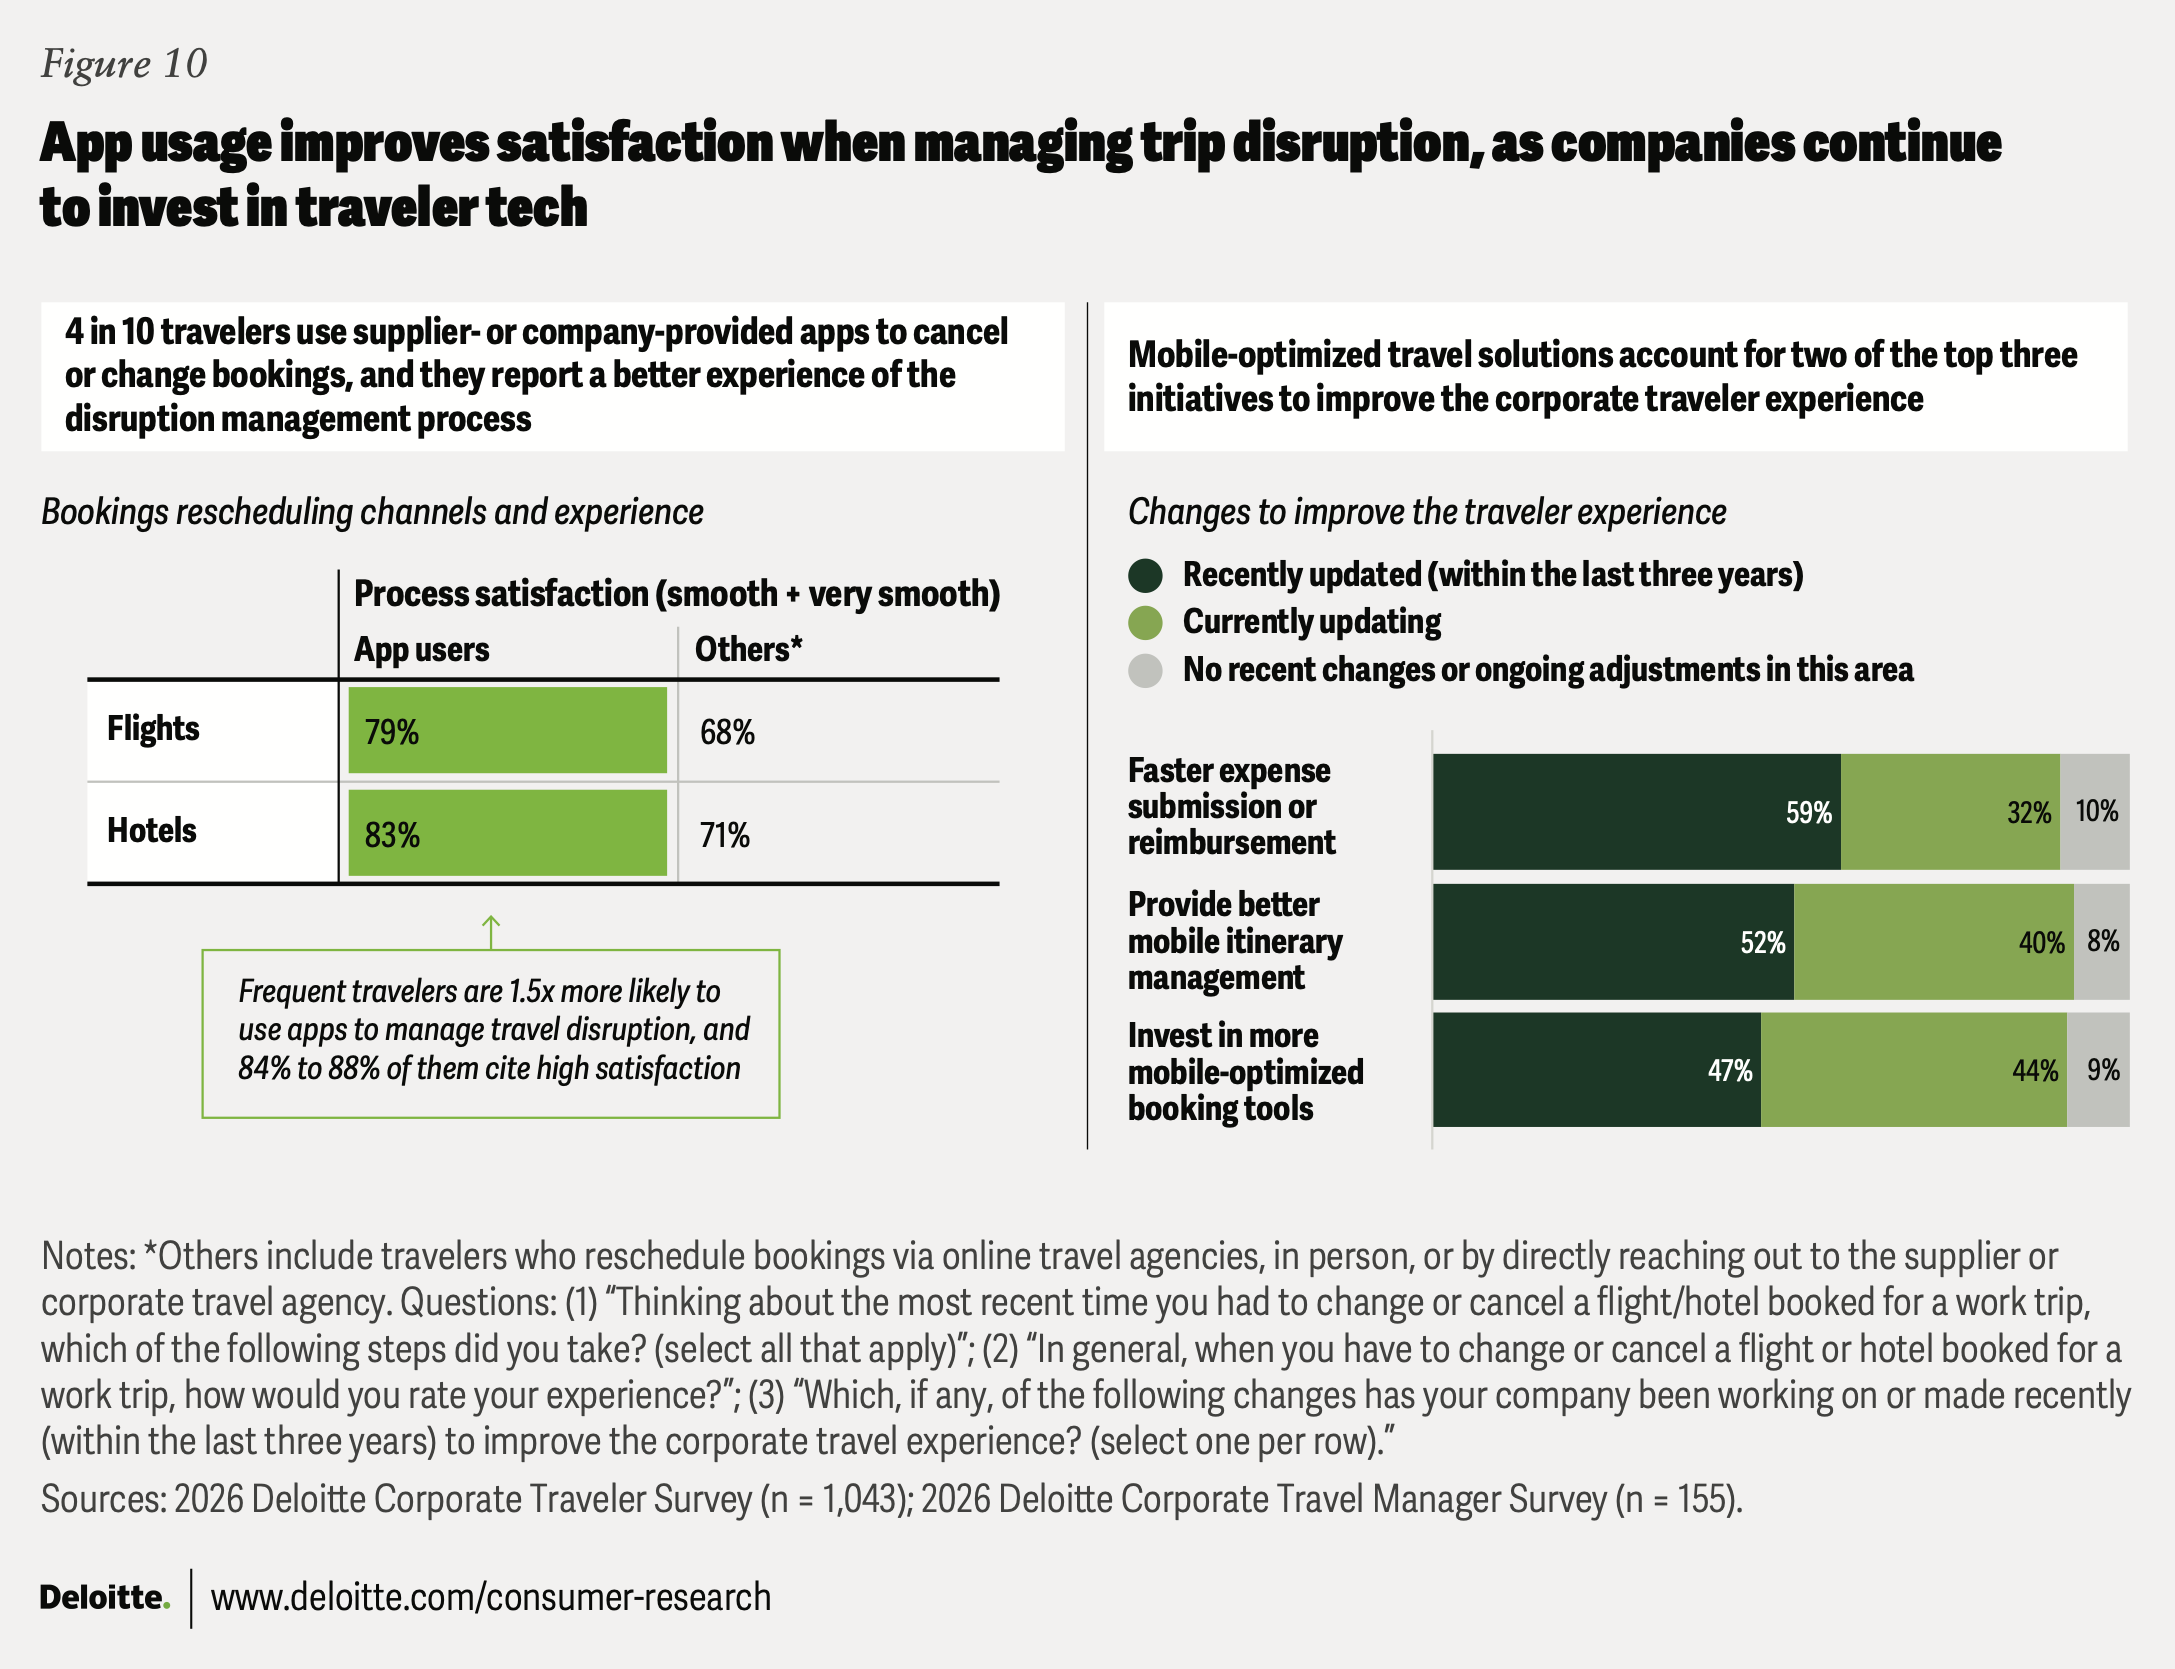
As companies seek to protect the travel experience while reining in spend, many are turning to technology. More than 8 in 10 travel managers report active or recent initiatives to upgrade travel technology. Expense management draws the most attention, but investment in mobile trip management is close behind it, trailing only sustainability in the share of companies currently working on improvements (figure 10).
The traveler survey indicates the investments are improving an important, if unfortunate part, of the trip experience. Travelers who use apps to rebook a disrupted flight or change a hotel reservation report meaningfully higher satisfaction than those who rely on a phone call to the travel agency or a conversation with a gate agent. Reported satisfaction is highest among millennials and Generation Z travelers, a possible signal that as these younger employees make up a bigger share of corporate travelers, the return on mobile investment will only grow.
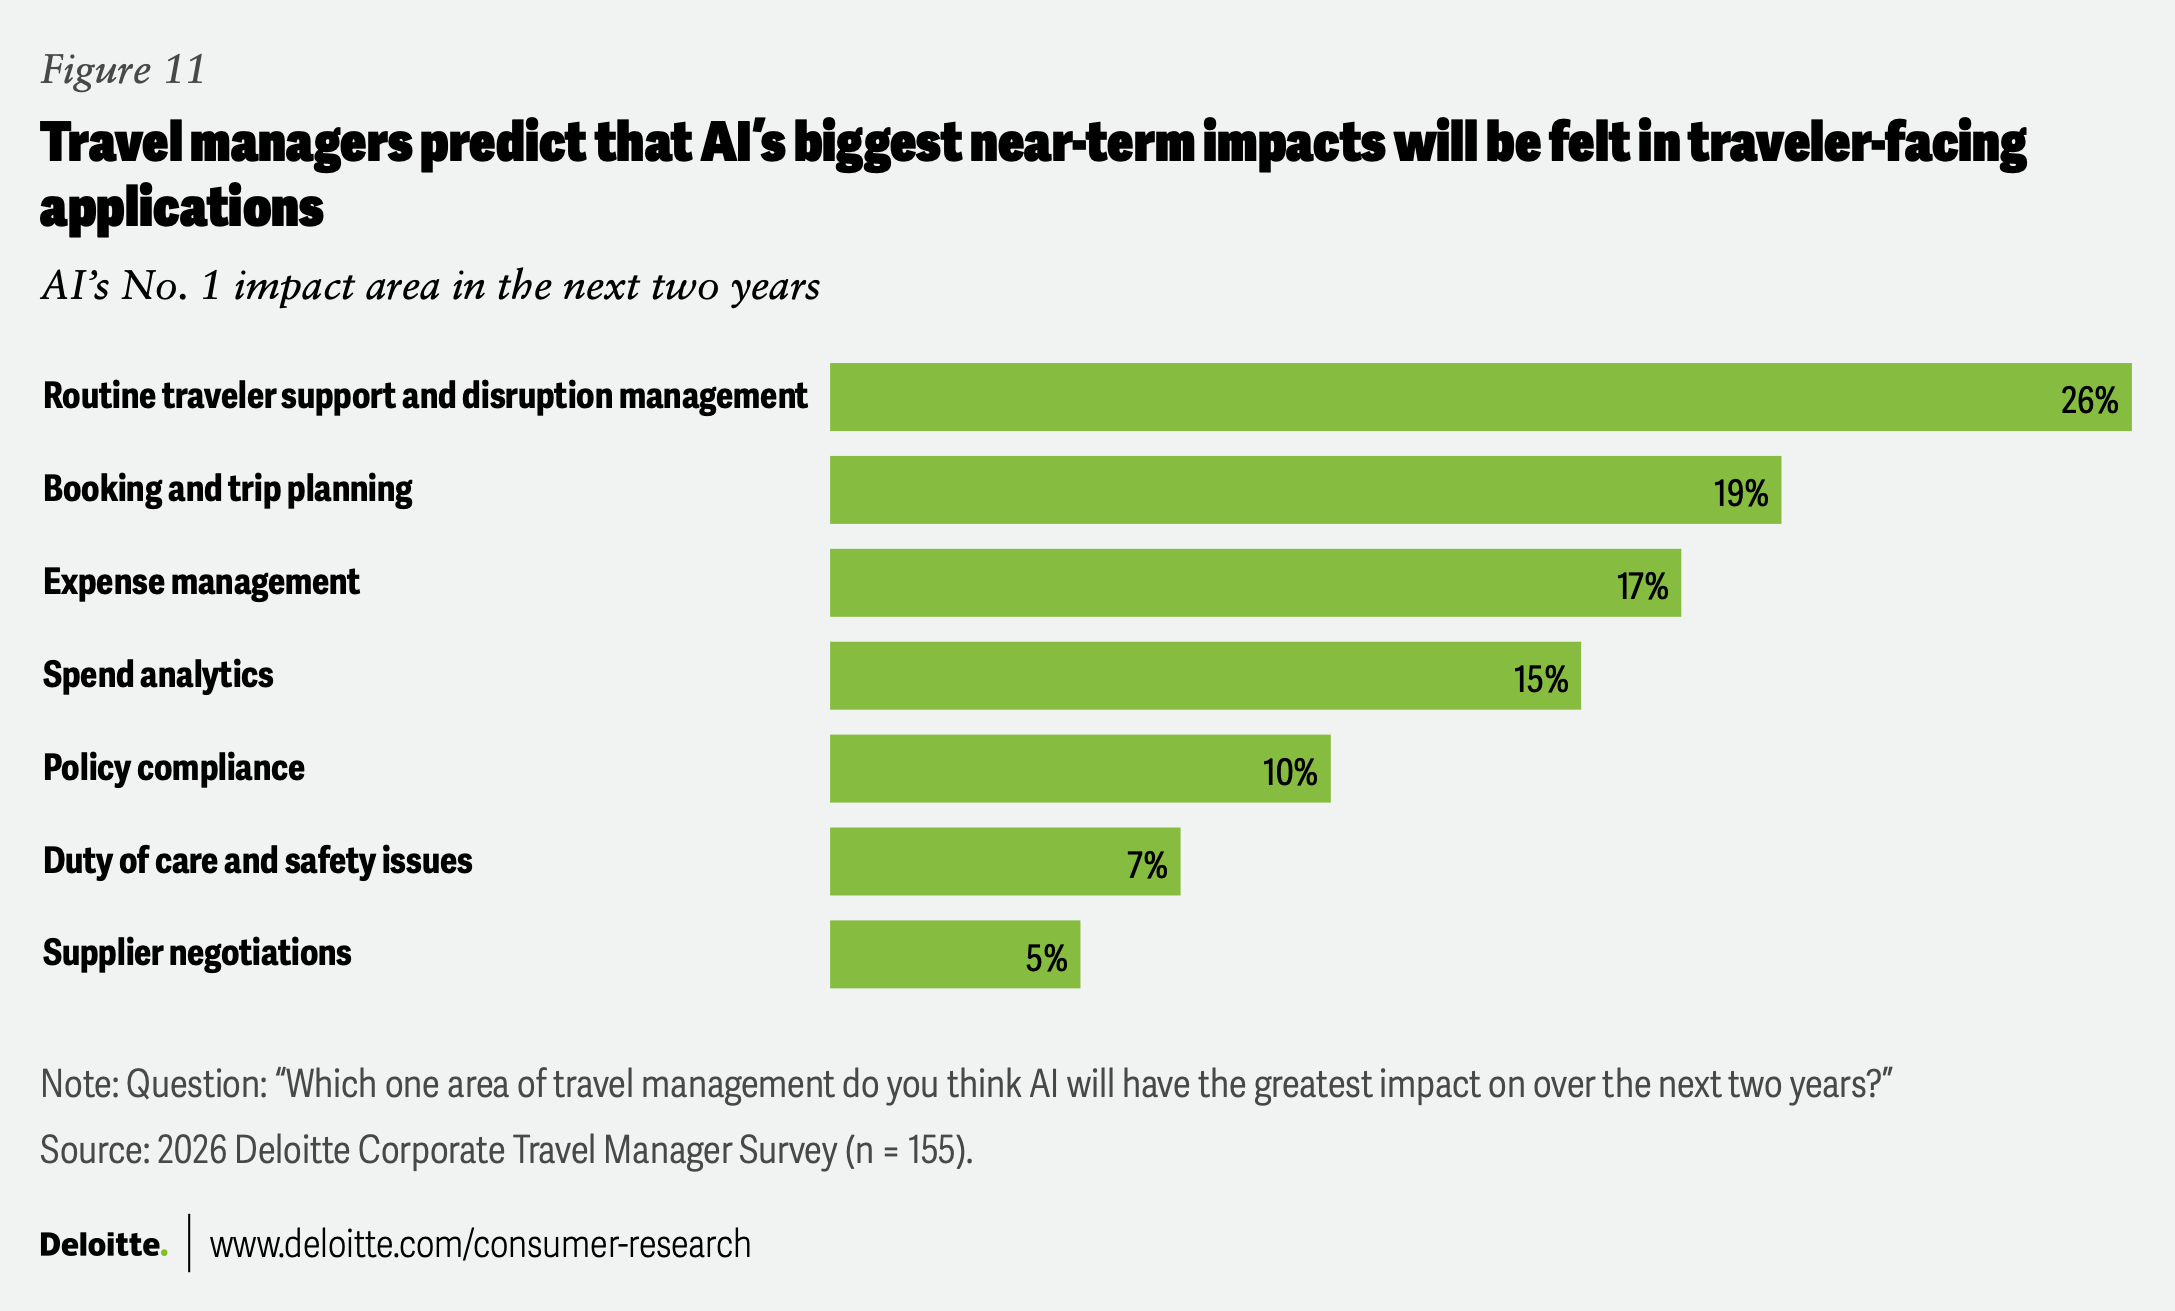
Given mobile travel tech’s reported effectiveness in managing flight disruption, it is notable that buyers expect AI’s greatest impact to be felt in this area. While there is no clear consensus among travel managers on where AI will matter most in the near term, the two leading responses—routine traveler support and disruption management (26%), and booking and trip planning (19%)—connect directly to the traveler rather than sitting behind the scenes (figure 11). Combined with expense management, these three front-end use cases account for 63% of responses.
Corporate travel in 2026 and beyond
Budgets are rising, trip volume is rising more slowly, and the difference is the price of getting there. Many companies are responding not by traveling less or forcing new frugality, but by traveling smarter. Travel managers and team leaders appear to be tightening processes, protecting the experience, and investing in technology to help fill some of the gaps.
For suppliers, this year’s data suggests trust, not price, may be key to upholding relationships with corporate buyers and the travelers they send out on the road.
Considerations for industry suppliers (such as airlines, hotels, and tech providers):
1. Compete on price, uphold service and amenities. Many buyers are protecting the traveler experience even as they tighten budgets. They want the same trip for less, not cheaper options that can erode trust. Cutting amenities alongside price misreads the moment.
2. Turn concessions into relationship equity. A better rate doesn’t automatically read as partnership. Suppliers may need to actively demonstrate long-term commitment—multiyear terms, transparency, flexibility in a pinch—or risk being seen as merely transactional even while giving ground.
3. Build for the front end, not just the back office. Buyers expect AI and tech investment to show up where travelers feel it—disruption handling, booking, and trip planning. Tools that visibly help travelers in the moment can help drive outsized satisfaction gains, especially with younger travelers. Self-service tools that resolve problems without a phone call are now a measurable differentiator.
4. Earn trust with data, not just discounts. As governance matures and buyers push decision-making to the operational level, suppliers who provide the reporting and predictability that operational teams need to manage compliance and KPIs will likely win more institutional trust than those competing on rate alone.
Continue the conversation
Meet the industry leaders
Kate Ferrara
Suzy O'Mara
Maggie Rauch
By
Kate Ferrara
Suzy O'Mara
Matt Josephson
Matt Soderberg
Maggie Rauch
The authors would like to thank Upasana Naik, Anand Kumar, and Rohith Alluri Reddy for their contributions to this report.
Editorial (including production and copyediting): Rithu Thomas, Preetha Devan, Anu Augustine, and Pubali Dey
Design: Molly Piersol
Cover image by: Tushar Barman; Adobe Stock
Knowledge services: Rohan Singh
Visit the Deloitte Consumer Industry Center
Access more insights for the automotive, consumer products, food, retail, wholesale and distribution, airlines and hospitality, and transportation sectors.