
TMT divestitures make a comeback: 2023 deal values in tech, media, and telecom may bounce back strongly
Many TMT companies are aiming to become smaller and more focused. Bottom-line pressure and high interest from private equity and venture capital firms can make it easier in 2023.
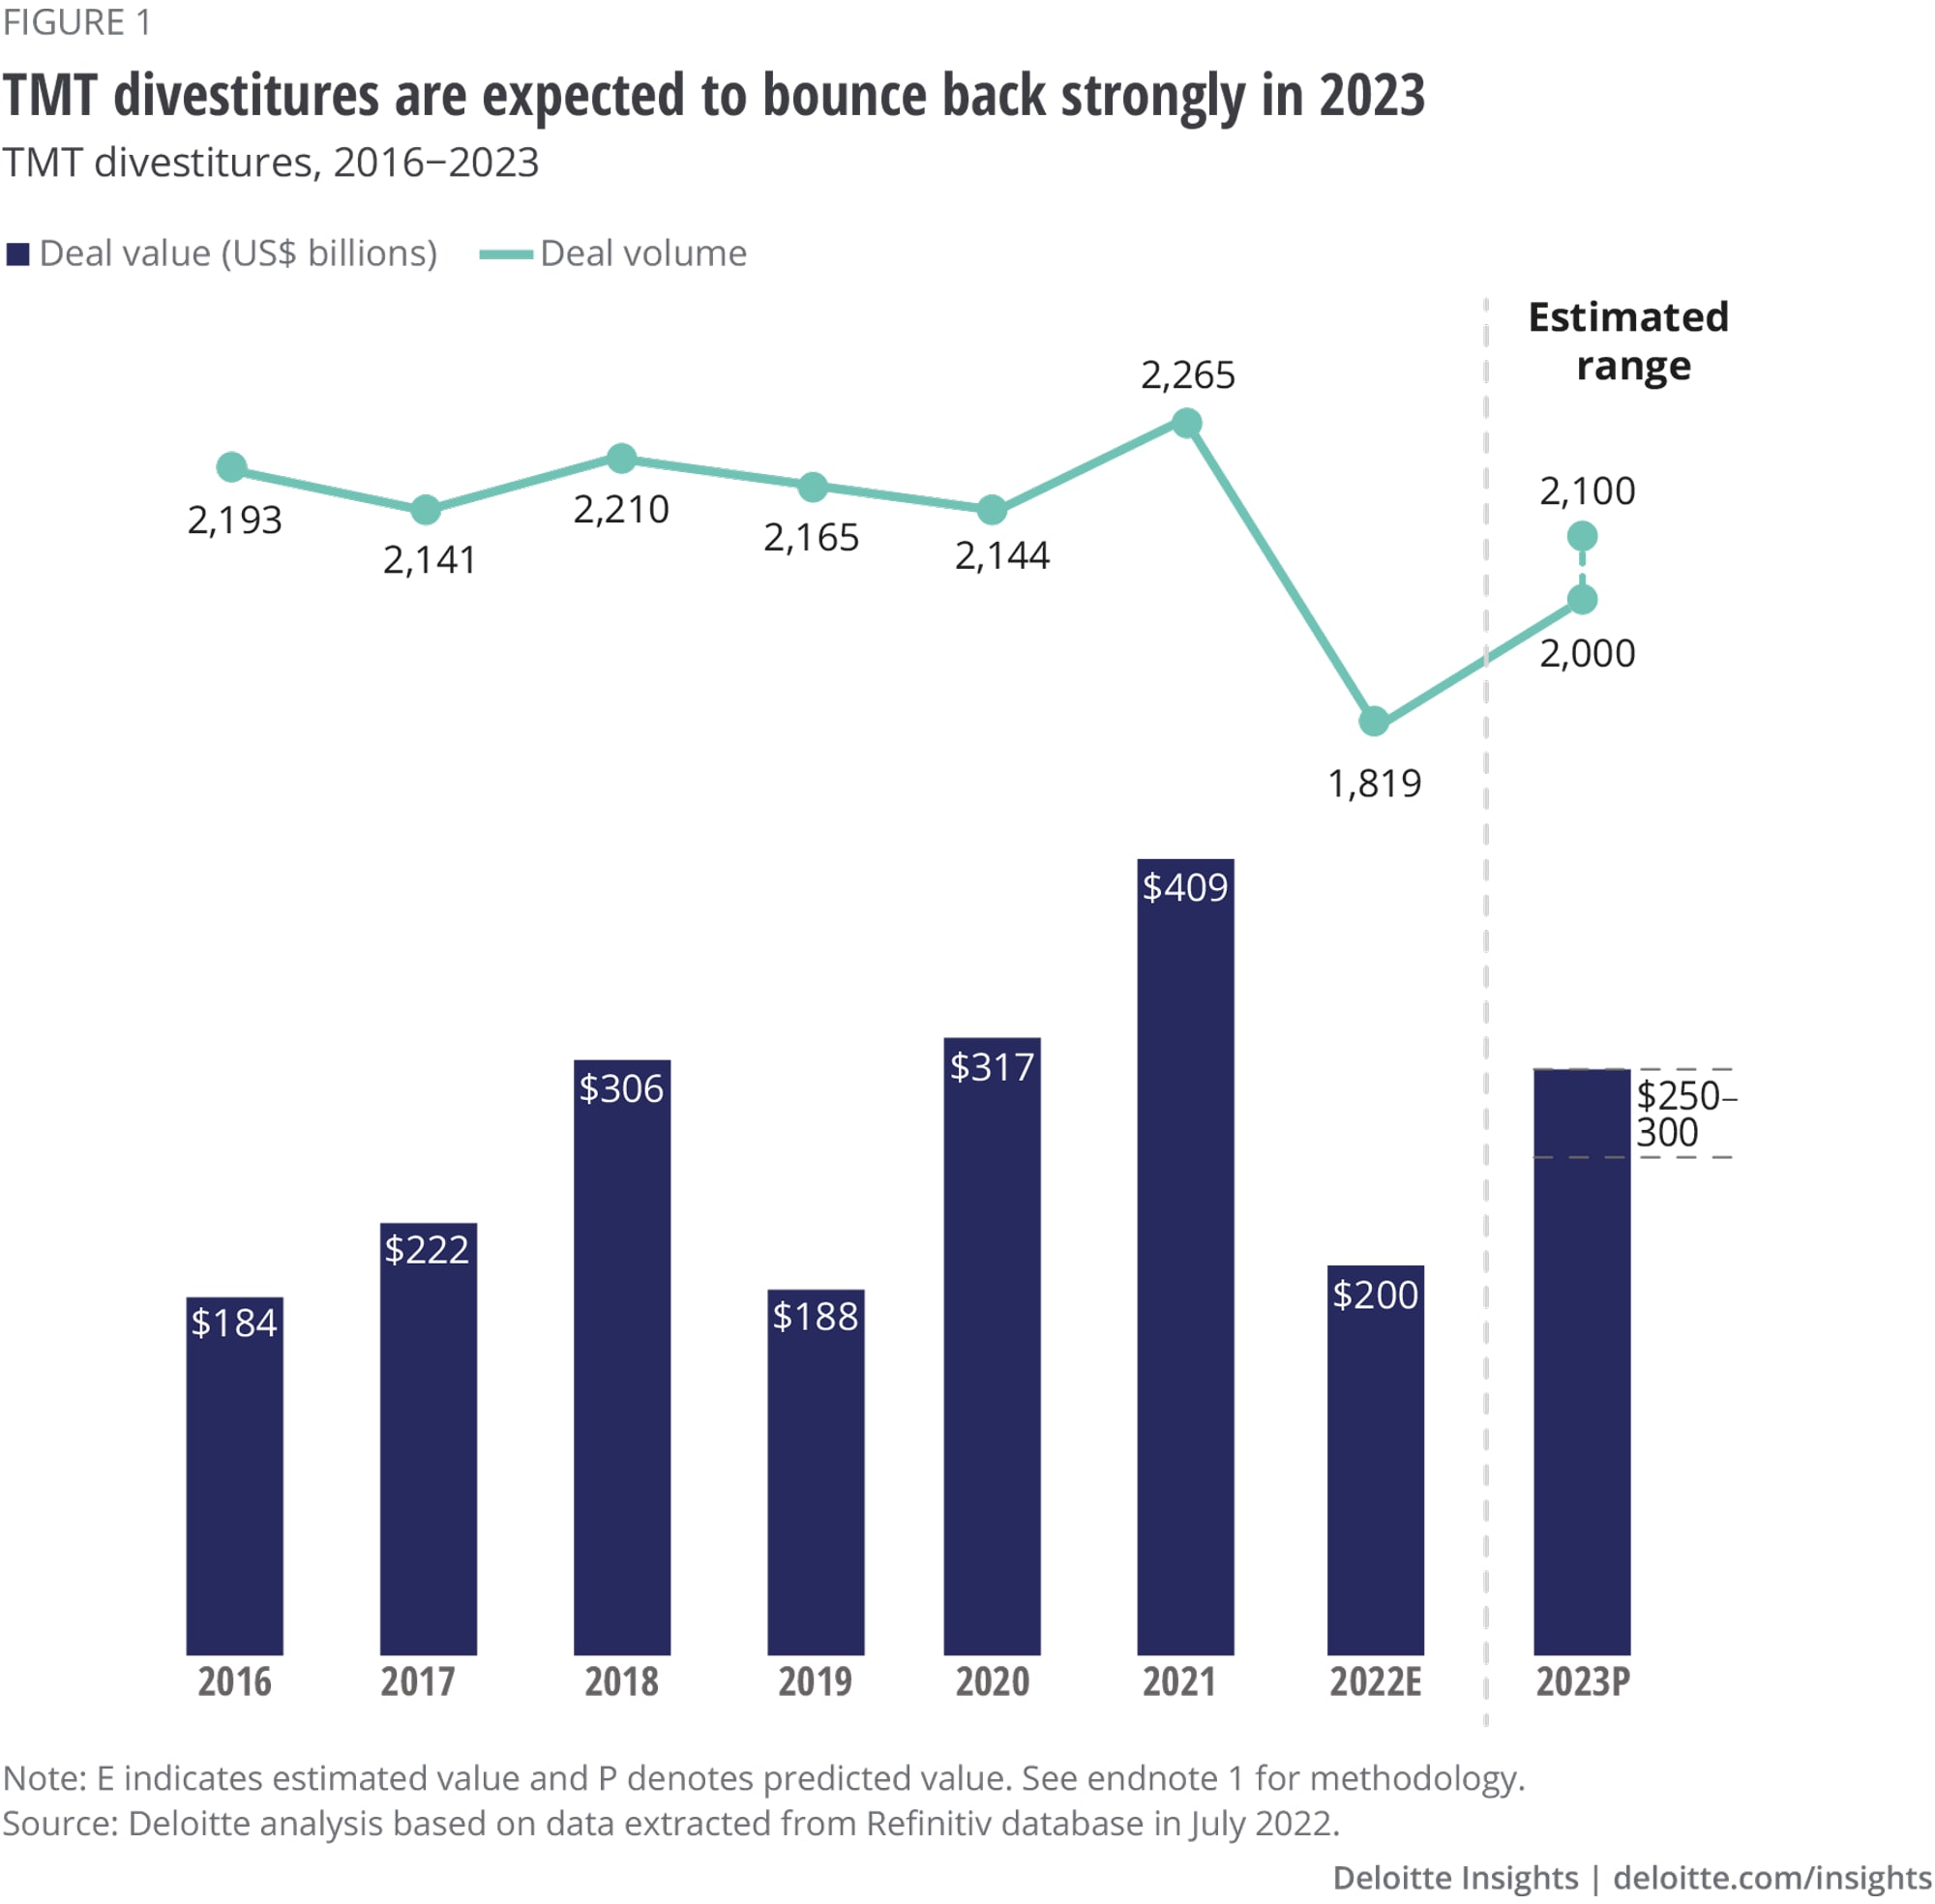
Due to macroeconomic headwinds, business disruptions, and a weak IPO market, TMT divestitures took a nosedive in 2022 from 2021’s record-setting values: Through the first half of 2022, total divestiture deal value fell 64% from the first half of 2021, while volume went down by only 21%. However, divestitures are now poised to bounce back to near-record highs. Deloitte Global predicts that the total value of TMT divestitures in 2023 could expand by 25–50% year over year to range from US$250–300 billion, well above the US$244 billion average for the period 2016–2020. The increase in total value will likely come from a rise in both deal values and volumes (figure 1) as the business and investment environment improves and deal volume returns to historic levels.1
Divesting now could appeal to sellers and buyers alike
The decrease in divestiture activity in the first half of 2022 had many drivers: recession worries, tighter credit markets, spiraling supply chain issues, and concerns about bottom-line impact. In addition, companies were most likely still taking stock of their asset portfolios following 2021’s robust M&A and divestiture season. But many TMT companies still see divestitures as a path to becoming more agile in dealing with future uncertainties, and as conditions improve, they will likely once more begin to act. In fact, Deloitte’s 2022 Global Divestiture Survey found that corporate leaders expect to step up divestiture activity going forward.2
We expect the recovery in TMT divestiture transactions will probably begin sometime in mid-2023, driven by several converging factors. Macroeconomic uncertainties and business disruptions may prompt companies to reassess their strategic business assets—including which ones it makes sense to hold onto.3 Additionally, activist investors are likely to press for divestitures soon, as a variety of challenges have led to disappointing earnings and falling share prices.4 Private equity investors (PEs) and select venture capital firms (VCs)5 may become more aggressive buyers by mid-2023 as they see more stable fund flows and highly attractive valuations compared to late 2021.
TMT executives are looking to divestitures to accomplish a variety of goals. Some are aiming to sharpen one or both entities’ focus on their core business;6 others want to unlock value from specific investments and assets;7 and some are doing both as part of their portfolio recalibration efforts. All of these goals will likely involve offloading noncore business divisions, suggesting that the growth in 2023’s deal activity will begin with an increase in the number of such niche, small-size transactions, with deal value following. Additionally, companies planning mega-mergers need to comply with regulations that mandate divesting certain assets before the mergers are approved.
As exit options, we expect corporate IPOs and especially SPAC-led deals to further weaken over the next 12–18 months due to higher valuations and rising interest rates. Given the muted IPO scene, we expect PE buyers to be more active in acquiring divested assets than strategic corporate buyers. PE firms are flush with record amounts of dry powder, and they will use it to chase select assets that they believe will yield higher ROI.8 Sellers should prime the assets that they intend to sell off, as the market is less likely to simply “take over” assets available for sale.
In the technology sector, noncore assets, specialized software businesses that have the potential to scale, and financially struggling divisions with proven business models will be attractive candidates for both sellers and buyers.9 Large, diversified semiconductor and electronics companies will likely continue to spin off select fab operations and facilities to focus on the core and preserve margins.10 From the buyers’ standpoint, PE investors can take advantage of the public funding announced by several governments, and could consider co-investing with interested chip companies to acquire fab operations that get spun off. Deal activity may be further accelerated by regulators potentially forcing some larger tech companies to divest for anti-trust concerns.
Meanwhile, the media-telecom convergence trend seems to be slowing down, with some major telcos starting to look at prospective buyers for their media assets—especially, film and TV businesses—which could prompt de-mergers. But a more prominent driver behind many media and entertainment divestitures is digitization and consumer behavior. Consumers continue to change how they consume content as well as their spending on telecom, media, and entertainment services. Ongoing streaming wars and personal financial constraints are leading consumers to reduce their number of subscriptions: Deloitte’s 2022 Digital Media Trends study found that almost 50% of US consumers felt that they pay too much for streaming video services, driving one in three to plan to cut back.11 Further, they are making very specific choices about what content and services they want to spend their money on.12 For media and entertainment majors and conglomerates offering content, broadcasting, connectivity, and entertainment, these consumer trends may prompt them to shed parts of their operations, not only to focus on their core business, but also to strengthen their financial position.
Deloitte’s 2022 Charting New Horizons M&A report suggests that telecom companies may deploy a range of defensive M&A strategies to safeguard their core businesses. For instance, they could continue to sell off select nonstrategic assets as part of a defensive strategy.13 Telecom tower and infrastructure companies as well as mobile broadband service providers may seek to sell noncore assets such as media services and large data centers to invest more in high-growth areas and initiatives such as 5G, fixed wireless access, or edge computing.
BY
Karthik Ramachandran
Sriram Prakash
Duncan Stewart
Gillian Crossan
The authors would like to thank Mark Casey, Joost Krikhaar, Pankaj Bansal, and Richa Khanna for their contributions to this chapter.
Cover artwork: Jaime Austin and Sofia Sergi