
Beyond the wellhead: Rewriting the US natural gas playbook
As LNG exports and growing gas-fired generation lift demand, producers and midstream operators are considering how to capture value through infrastructure, contracts, and market access
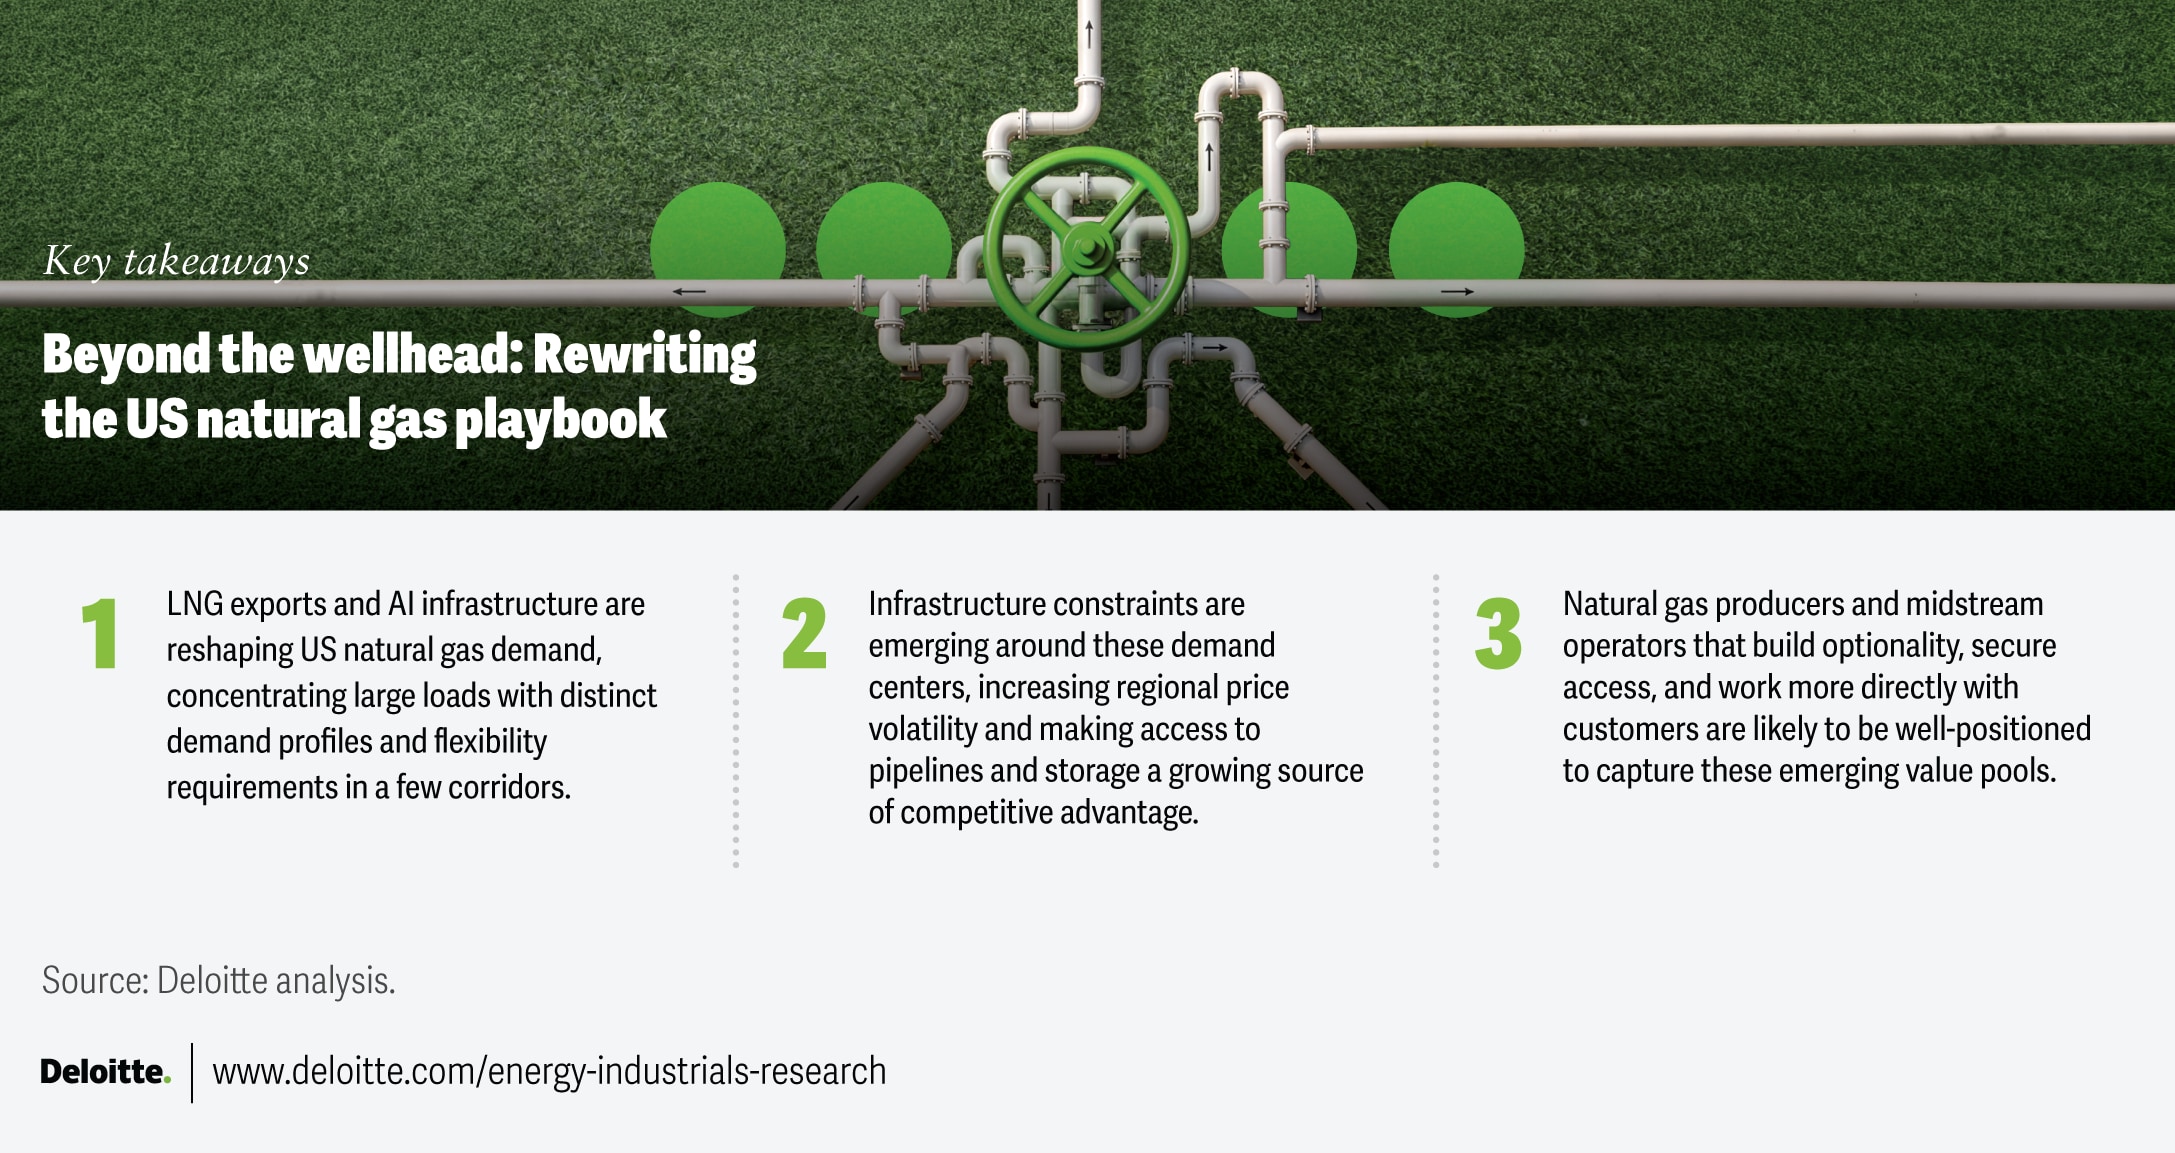
US natural gas is entering a new competitive era. For years, advantage came from producing at the lowest cost through operational efficiency, acreage quality, and scale. That still matters, but liquefied natural gas exports and growing artificial intelligence–driven power demand are shifting value toward deliverability, reliability, and commercial flexibility in a handful of premium corridors. As infrastructure tightens and regional spreads become more unpredictable, producers and midstream operators are repositioning to secure access, deepen customer relationships, capture new value pools, and expand optionality.
Demand is being redrawn
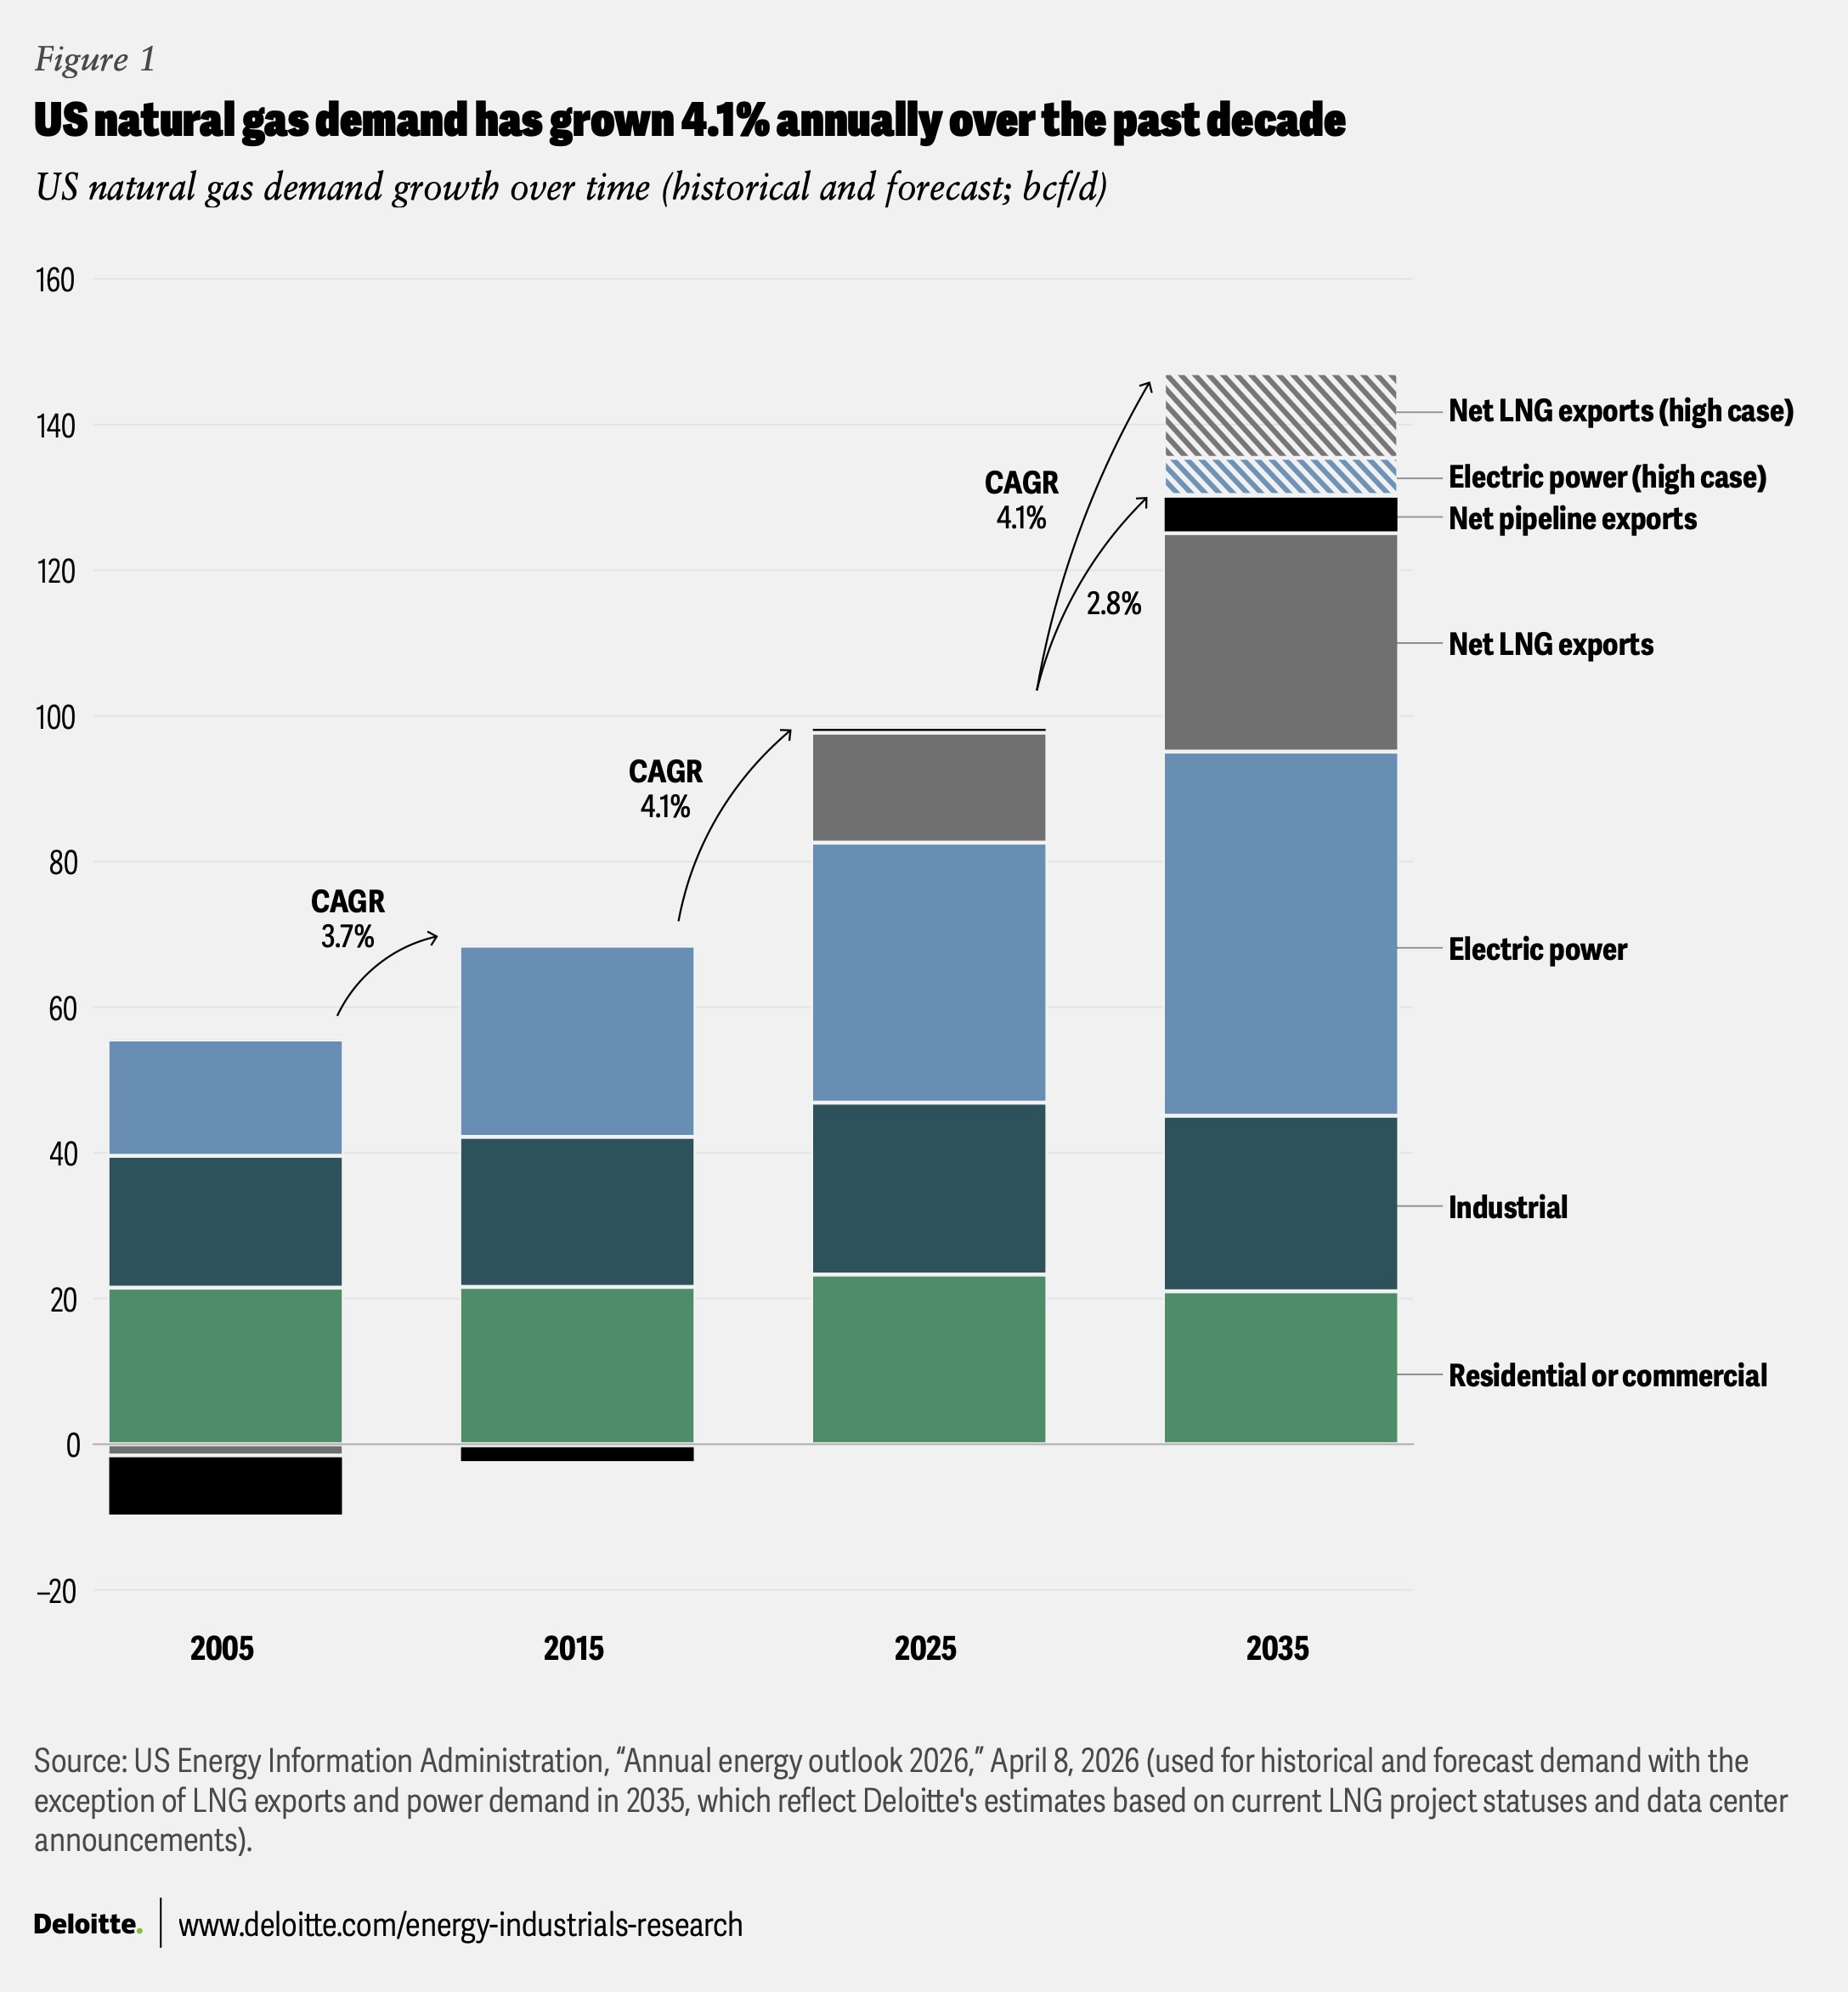
US natural gas demand has grown 4.1% annually over the past decade, driven primarily by LNG exports and increased gas-fired power generation (figure 1).1 The latter has been supported by abundant, low-cost domestic supply, which has displaced coal and provided dispatchable backup for intermittent renewables. Looking ahead, Deloitte estimates demand growth of 2.8% to 4.1% annually through the mid-2030s, driven by the power sector and LNG exports.2 An important issue is not simply how much demand grows, but where it is located, when it is needed, and how flexible it is. Those characteristics are expected to increasingly influence infrastructure needs, regional prices, and market volatility.
Concentration of demand growth
Over the past 20 years, US natural gas demand growth was largely production-driven, concentrated near shale basins where natural gas prices were relatively low, with Texas, Pennsylvania, Ohio, Florida, and Louisiana accounting for nearly half of total growth.3 Today, LNG exports and large power users are creating new pockets of concentrated demand. Deloitte estimates LNG exports could exceed 30 billion cubic feet per day (bcfd) by 2035, concentrating more than 35% of total US demand in just two states: Texas and Louisiana.4 Incremental power demand to support AI infrastructure could reach 15 to 20 bcfd nationally over the same time period as states work to meet rapidly evolving energy needs that could strain local pipeline capacity and increase the need for new deliverability.
Demand profiles and flexibility
With LNG exports and AI infrastructure–driven gas-fired power demand expected to account for about one-third of total US natural gas demand by 2035,5 the demand profiles and flexibility of these facilities could significantly impact infrastructure requirements and local price dynamics.
LNG exports have mostly functioned as baseload demand over the past decade. Since 2016, US LNG export facilities have averaged over 90% utilization, falling to around 70% in 2020 during the COVID-19 pandemic but exceeding nameplate capacity during periods of high global demand.6 This pattern has been supported by strong global pricing, as well as financing requirements that typically call for at least 70% of capacity to be backed by long-term agreements before reaching a final investment decision (FID).7 However, several recent projects have reached an FID with less contracted capacity, which could increase exposure to global LNG pricing in the future.8
Power demand is less predictable because it combines base load demand with weather- and AI- driven spikes. The impact on natural gas markets will likely differ depending on factors such as the specific power demand profile, whether the generator is behind the meter or in front of the meter, and existing local market conditions. The impact could also change over time as other sources of power generation, such as nuclear or renewables plus storage, continue to advance.
The result is expected to include tighter markets in some areas, with the potential for higher, more volatile hub prices, which could incentivize new infrastructure buildout.
Volatility has returned, and it’s becoming more regional
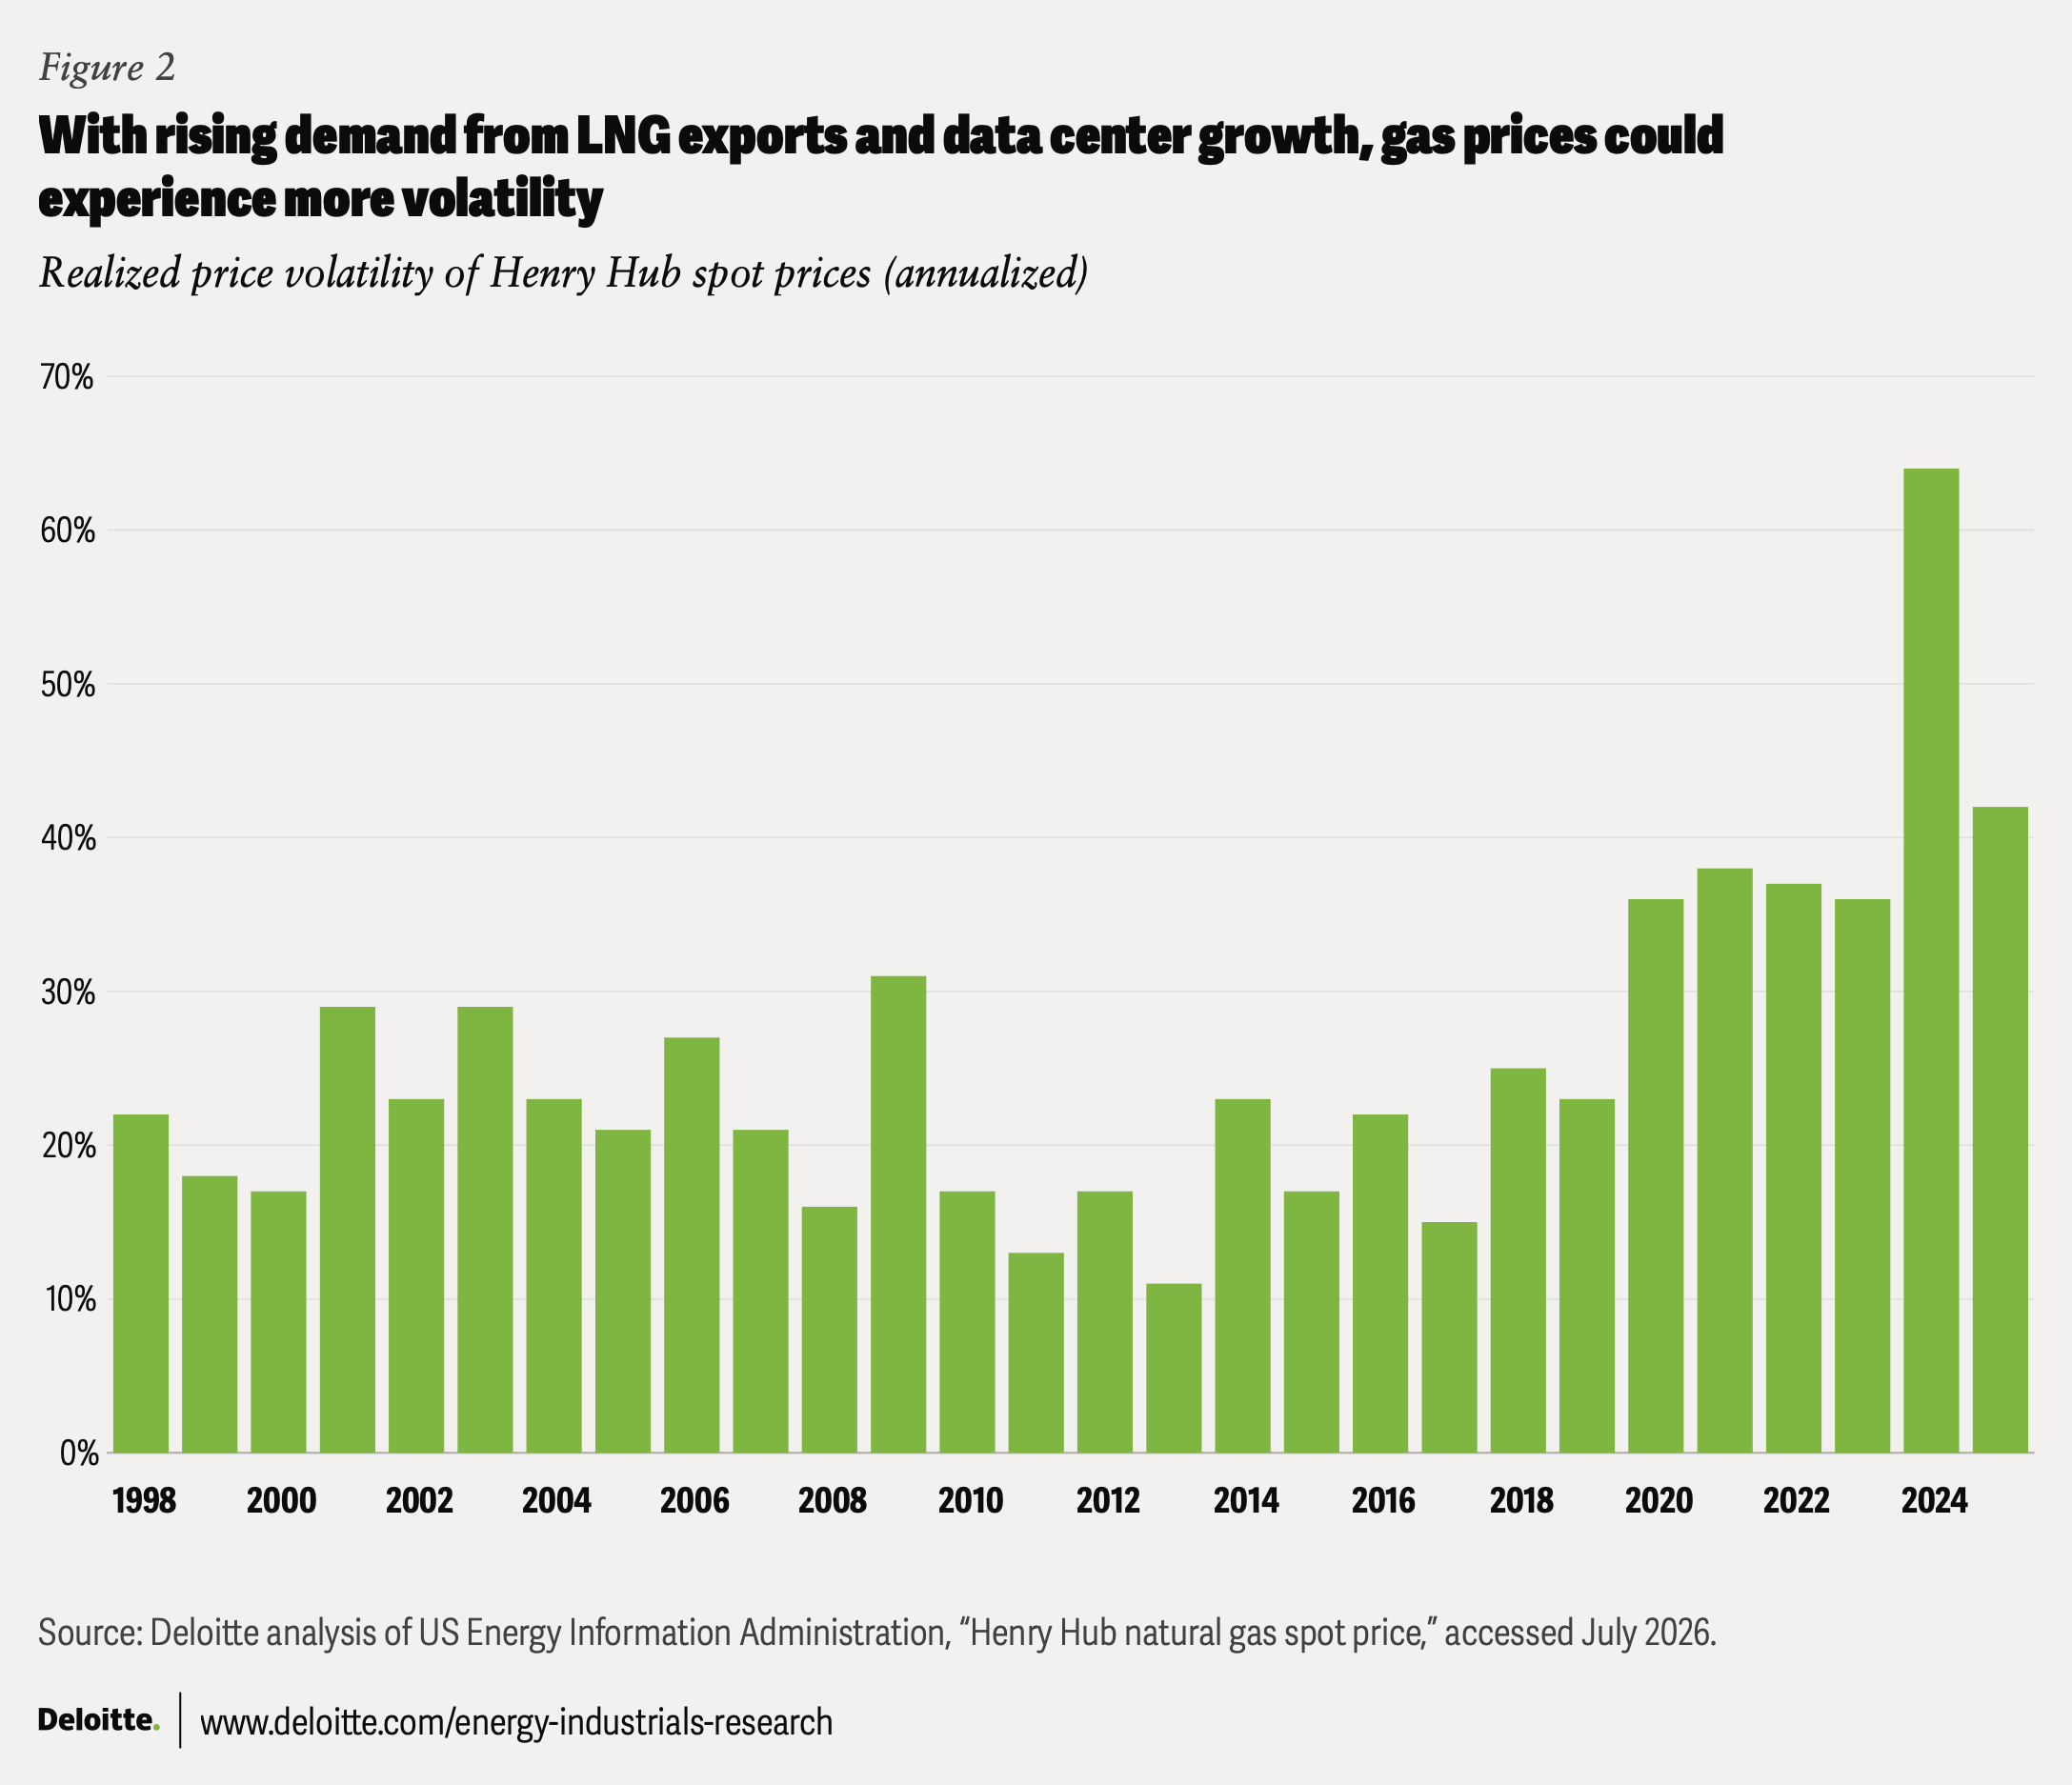
Henry Hub volatility began returning in 2020, influenced by weather, capital discipline, and shifts in the power sector.9 As LNG exports and large power user demand grow, volatility is likely to increase and become more regional and infrastructure driven (figure 2).
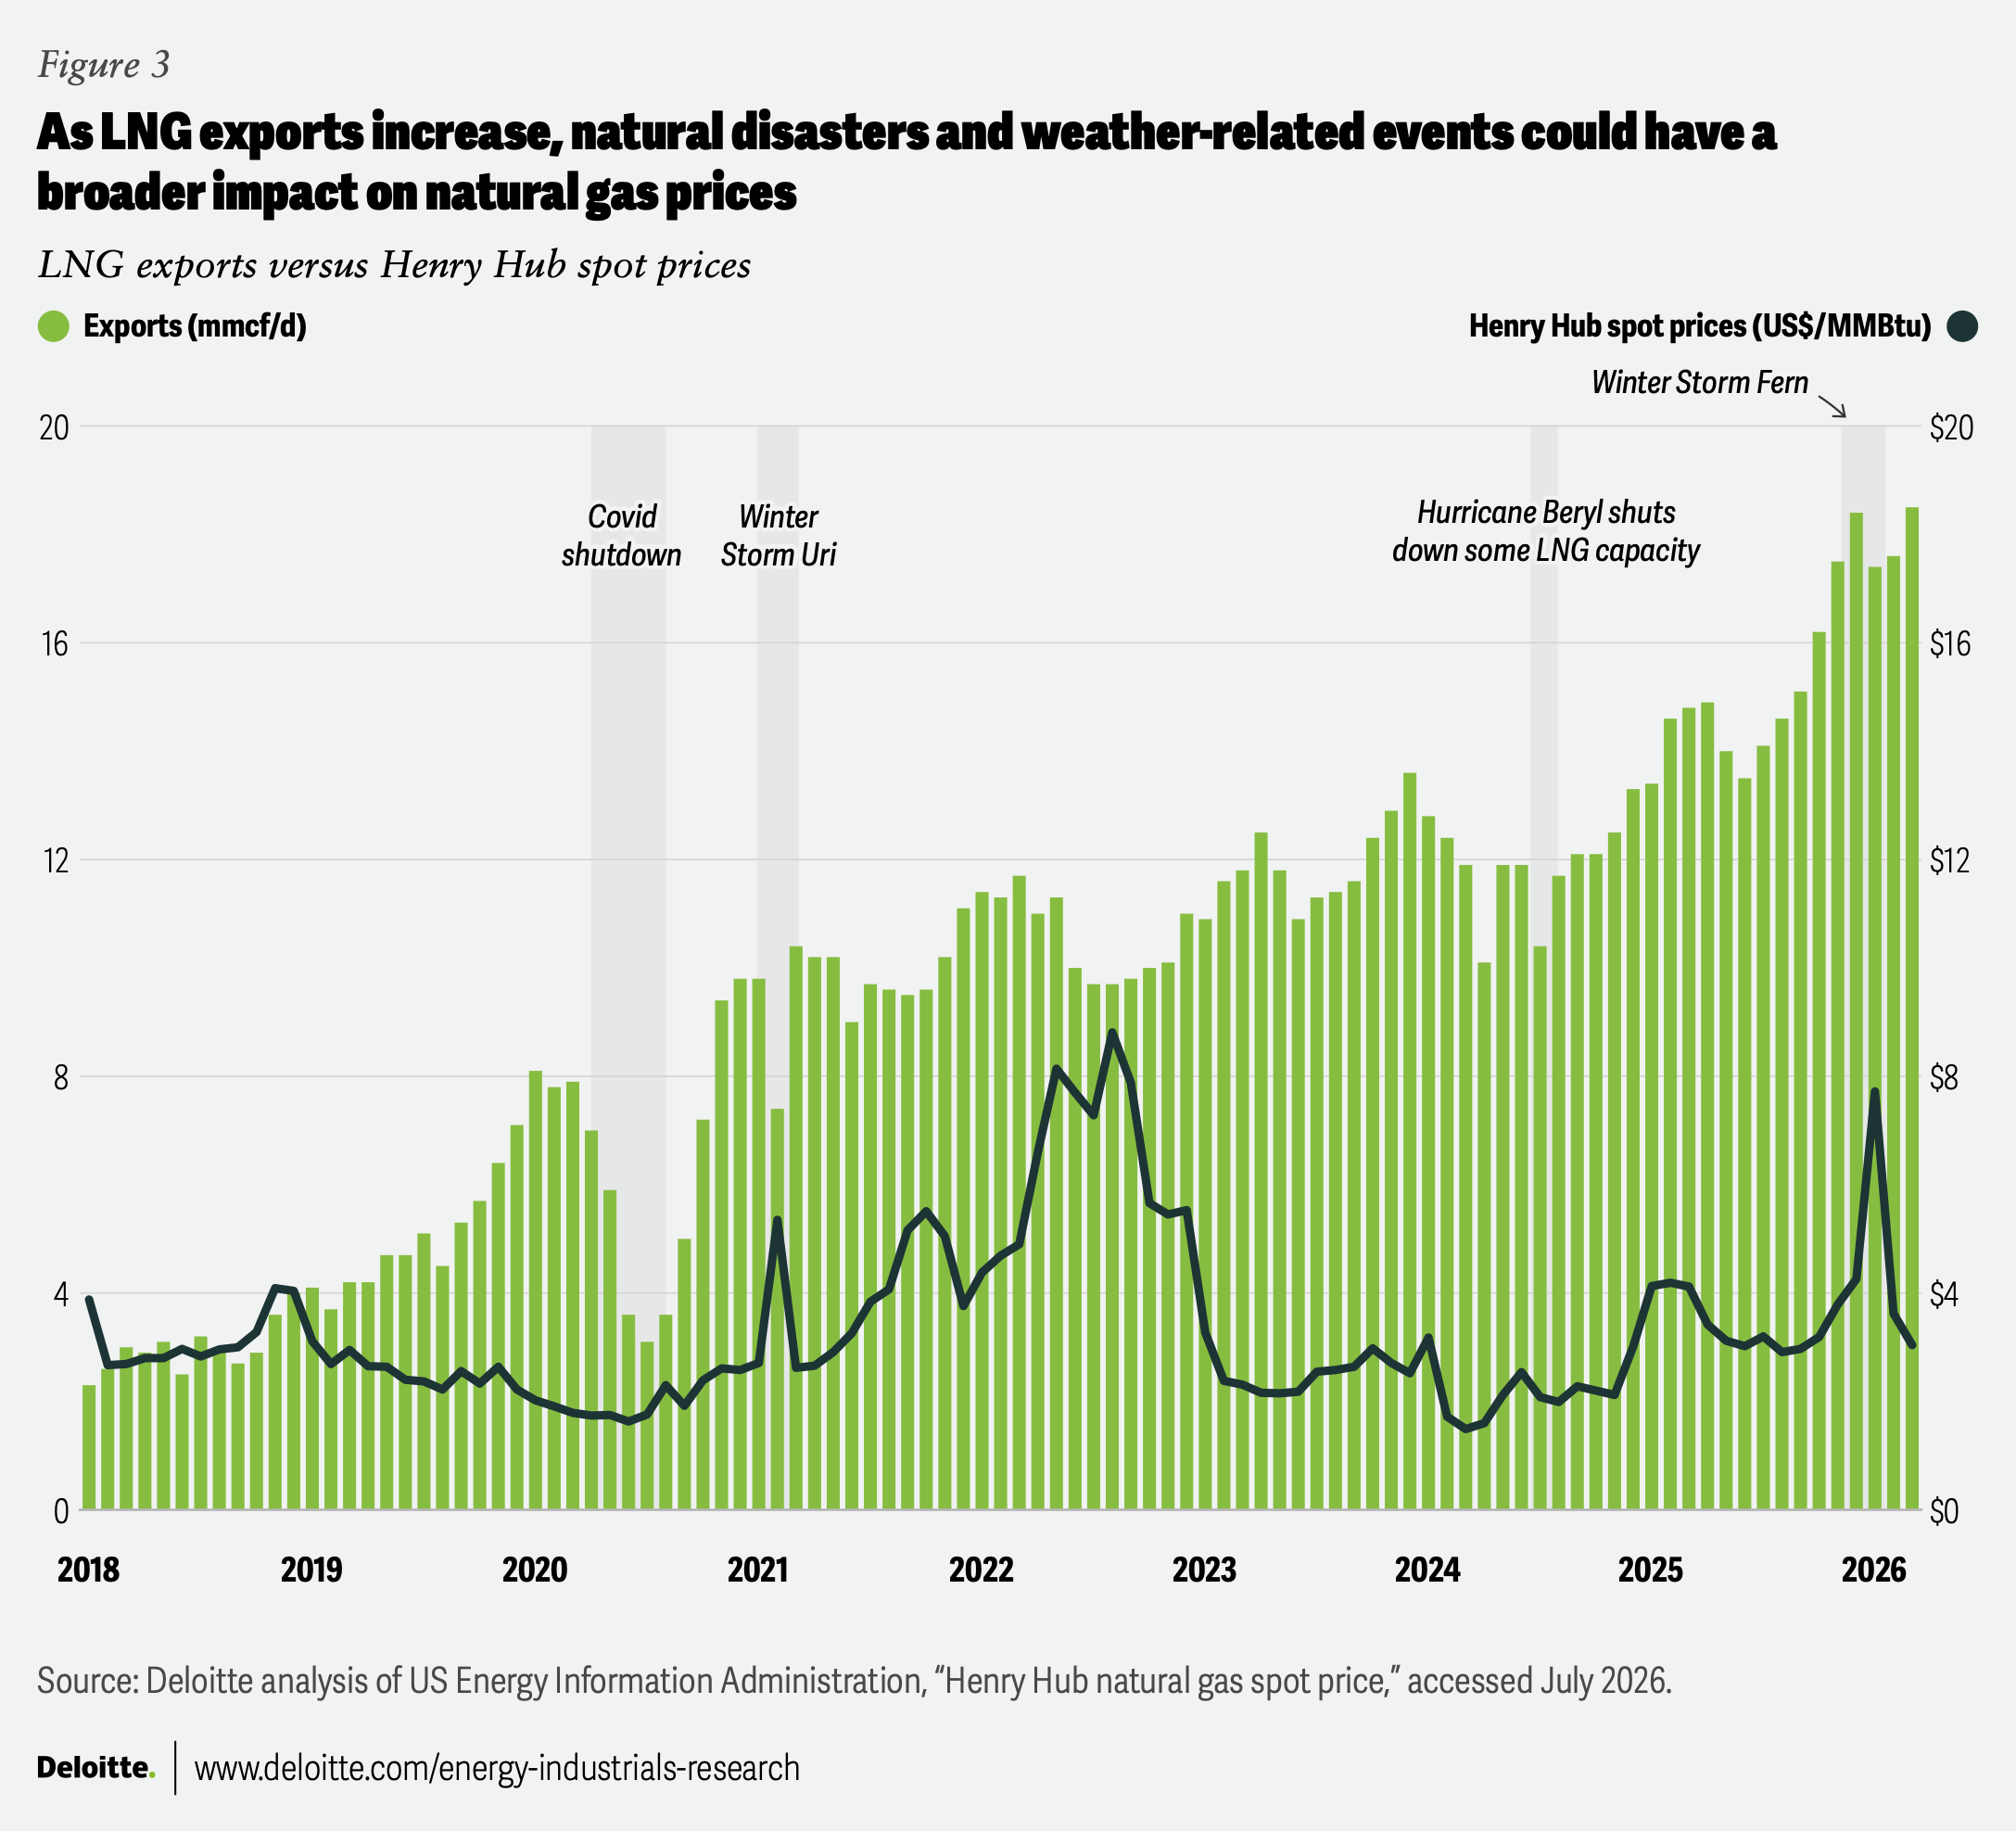
LNG exports illustrate the change. Higher exports do not necessarily mean structurally higher US prices. But they can amplify disruptions by concentrating large, high-utilization demand along the Gulf Coast. As export capacity expands, unplanned outages, hurricanes, pipeline constraints, and changes in global LNG demand could have larger regional effects (figure 3). When a facility has an unexpected outage, feedgas demand falls, putting downward pressure on regional natural gas prices.10 Along the Gulf Coast, this could increase the value of flexible storage and pipeline capacity that can redirect gas to alternate markets.
The flexibility can also work in the other direction. When domestic gas prices spike, LNG facilities may reduce feedgas demand or, in unusual circumstances, import cargoes to help serve domestic markets, which happened during Winter Storm Fern in January 2026.11
Large power users could introduce a different source of regional volatility. Rapid electricity load growth could lead regional grid operators to increase reliance on gas-fired generation as renewable resources provide energy but limited dispatchable capacity during periods of system stress.12 Weather, transmission congestion, and pipeline deliverability may therefore exert greater influence on regional power and gas prices.
Deliverability is becoming a scarce asset
Because demand is concentrating in a few select areas, deliverability, including pipelines and storage, is becoming a binding constraint. Pipeline investment reflects the renewed importance of deliverability. Approximately 45 bcfd of new US pipeline capacity is expected to enter service during 2026 and 2027, the largest buildout in nearly a decade.13 However, more than 80% is designed to debottleneck Permian production or support LNG exports.14 Developers are also expanding to serve new large loads and debottleneck Appalachian production,15 but additional capacity will likely be needed in key markets.
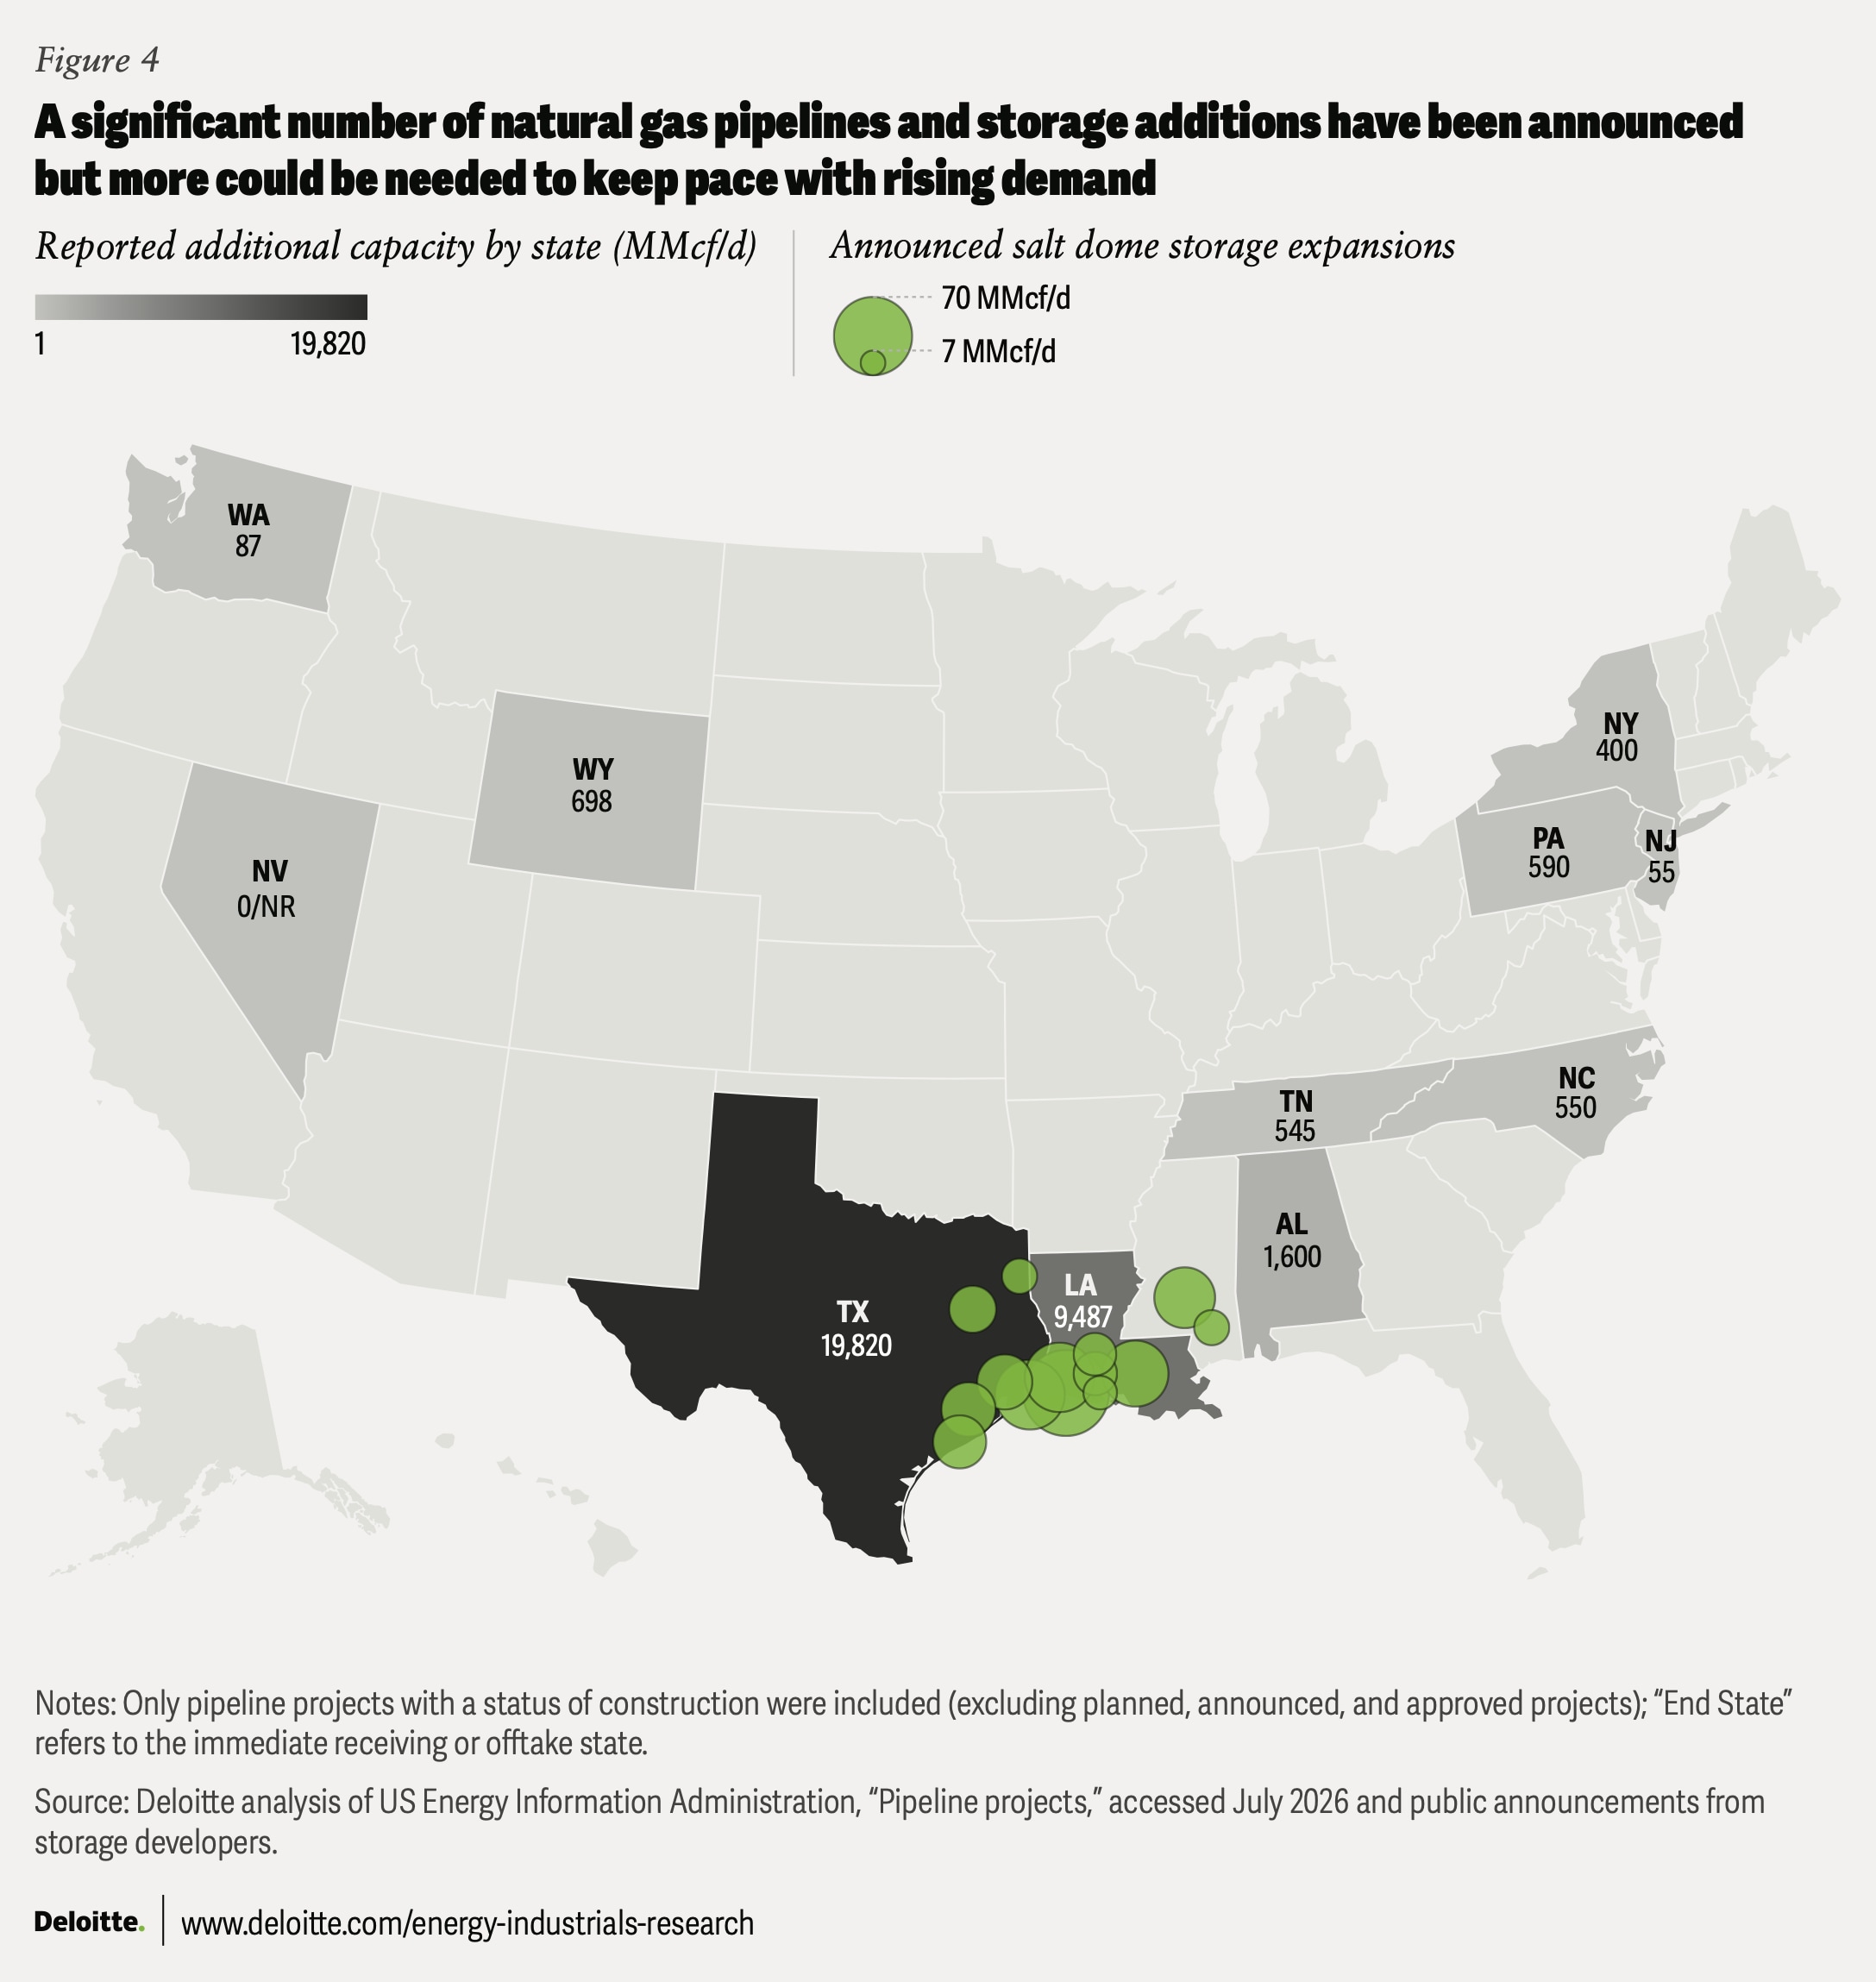
Underground storage is having its own revival as storage becomes increasingly important for balancing daily and seasonal differences between production and consumption. Yet US storage capacity has grown much more slowly relative to production, falling from 21% of total production in 2008 to 12% in 2025.16 Salt dome storage, which is almost exclusively located along the Gulf Coast, provides rapid cycling capability, rather than seasonal capability, meaning it can inject and withdraw at faster rates to help smooth some volatility.17 About 400 bcf of salt dome storage has been announced in recent months.18 While these additions only represent an 8% increase in total working gas storage capacity, they nearly double rapid-cycling salt dome storage through the early 2030s.19 Even so, more capacity may be needed to help protect against LNG outage–related swings as export capacity expands (figure 4). Depleted reservoirs and aquifer storage remain important for seasonal balancing but are less responsive during short-term stress.
Ways producers and midstream operators are repositioning
As infrastructure gaps drive price volatility in certain regions, competitive advantage is shifting from supply to flexibility. The ability to switch markets, respond to price signals, secure firm transport, and hedge uncertainty through contract structures has become important. Some companies across the value chain appear to be positioning themselves as owners of optionality rather than just suppliers, with producers and midstream operators collaborating more closely and moving nearer to buyers.
Producers
Today, many producers are rethinking how they market gas, structure contracts, allocate capital, and position portfolios. This shift is moving the industry from commodity suppliers toward integrated energy suppliers with more direct exposure to end-use demand. Producers often compete on supply reliability, contract certainty, emissions intensity, operational flexibility, and the ability to support 20-year projects.
Some producers are considering three approaches:
- Securing premium market access: Producers are moving to gain access to markets where realized prices are strongest by securing contracts, firm transportation, and acreage closer to demand. Some are selling natural gas under contracts linked to global gas prices or signing LNG offtake agreements to gain direct exposure to global markets.20 Others are signing deals with in-basin large loads.21 Moving downstream can create more stable demand and higher margins, but it also requires higher capital, more complex contracts, and greater exposure to new counterparties and markets.
- Contracting long-term demand: Some producers are locking in long-term demand with LNG and some large power customers. Traditionally, most domestic natural gas has been sold to local distribution companies, power plants, and industrial buyers through the spot market or through short-term contracts.22 However, longer contracts of 10 to 20 years could support drilling programs, reduce cash flow volatility, and justify infrastructure investments. These long-term contracts have been fixed, hybrid, and indexed to local or global hubs. The trade-off is less flexibility to benefit from the spot-market upside.
- Owning more optionality: Producers are also investing across the value chain, building integrated energy solutions. For instance, some companies are expanding downstream assets such as pipelines, storage, gathering or processing, and power generation.23 Others are building out a portfolio of flexible contracts, increasing their marketing capability, and working directly with customers and midstream partners rather than using middlemen.24 That optionality can increase synergies and efficiencies, but it can also come at a premium.
Midstream owners and operators
Midstream companies appear to be repositioning from transporting supply to aggregating demand. Rising demand from LNG and large power users is contributing to long-dated, contracted expansions in specific corridors. Companies are therefore working to ascertain that their systems are sitting where growth is durable, contracted, and expandable at attractive returns. Some midstream operators look to be considering three strategies.
- Prioritizing expandable brownfield corridors and system optimization. Many new pipelines are being built to debottleneck production in the Permian Basin and deliver gas to LNG facilities along the Gulf Coast.25 However, in the northeast, midwest, and southeast, about 85% of projects currently announced or under construction are brownfield expansions or upgrades aimed at debottlenecking Appalachia and serving growing demand.26
- Increasing investment in infrastructure in line with demand growth. Storage is moving up the strategy stack as demand becomes more variable. Addressing changing gas supply-demand patterns, LNG outages, and rising power demand will be important. Some large power users are also contracting with some midstream players closer to power infrastructure and behind-the-meter models.27
- Leaning into direct demand-linked contracting. Some companies are contracting directly against demand, rather than waiting for upstream volume growth. Midstream companies are signing gas supply and transport agreements directly with large power users, power generators, and LNG customers.28 They’re also working with these same players to identify where demand is bankable enough to support new infrastructure.
Looking ahead: Competition is shifting to access
The US natural gas market is not short on supply, but it is increasingly constrained by access issues. LNG and large power users are pulling demand into corridors where infrastructure, contracts, and reliability matter as much as production. As a result, value is shifting from volume to deliverability and from commodity exposure to customer access. The next era of US gas competition may not be won by those with the most molecules, but by those with access, a strong portfolio of contracts, and a clear corridor strategy.
Continue the conversation
Meet the industry leaders
Zillah Austin
Earl Stone
Kate Hardin
By
Zillah Austin
Kate Hardin
Ashlee Christian
The authors would like to thank Ankhi Biswas and Jaya Nagdeo for their contributions to this report, including research and analysis.
The authors would like to thank James Toups, Earl Stone, Steve Pankratz, and Julia Tavlas for their subject matter input and review.
The authors would also like to acknowledge the support of Clayton Wilkerson for orchestrating resources related to the report; Randy Brodeur, Katrina Drake Hudson, and Dario Failla for driving the marketing strategy and related assets to bring the story to life; Mariel Balaban and Kaitlin Pellerin for leading public relation efforts; Rithu Thomas and Aparna Prusty from the Deloitte Insights team for editing the report and supporting its publication; and Harry Wedel for creating the visual design.
Editorial (including production and copyediting): Rithu Thomas, Aparna Prusty, Pubali Dey, and Anu Augustine
Design: Harry Wedel, Sana Saifi, and Jim Slatton
Cover image by: Sanaa Saifi and Jim Slatton
Knowledge services: Agni Wagh
Visit the Deloitte Center for Energy & Industrials
Access more insights for the aerospace and defense, chemicals and specialty materials, engineering and construction, industrial manufacturing, mining and metals, oil and gas, power and utilities, and renewable energy sectors.